State Homeowners Insurance Key Factors And State Variations
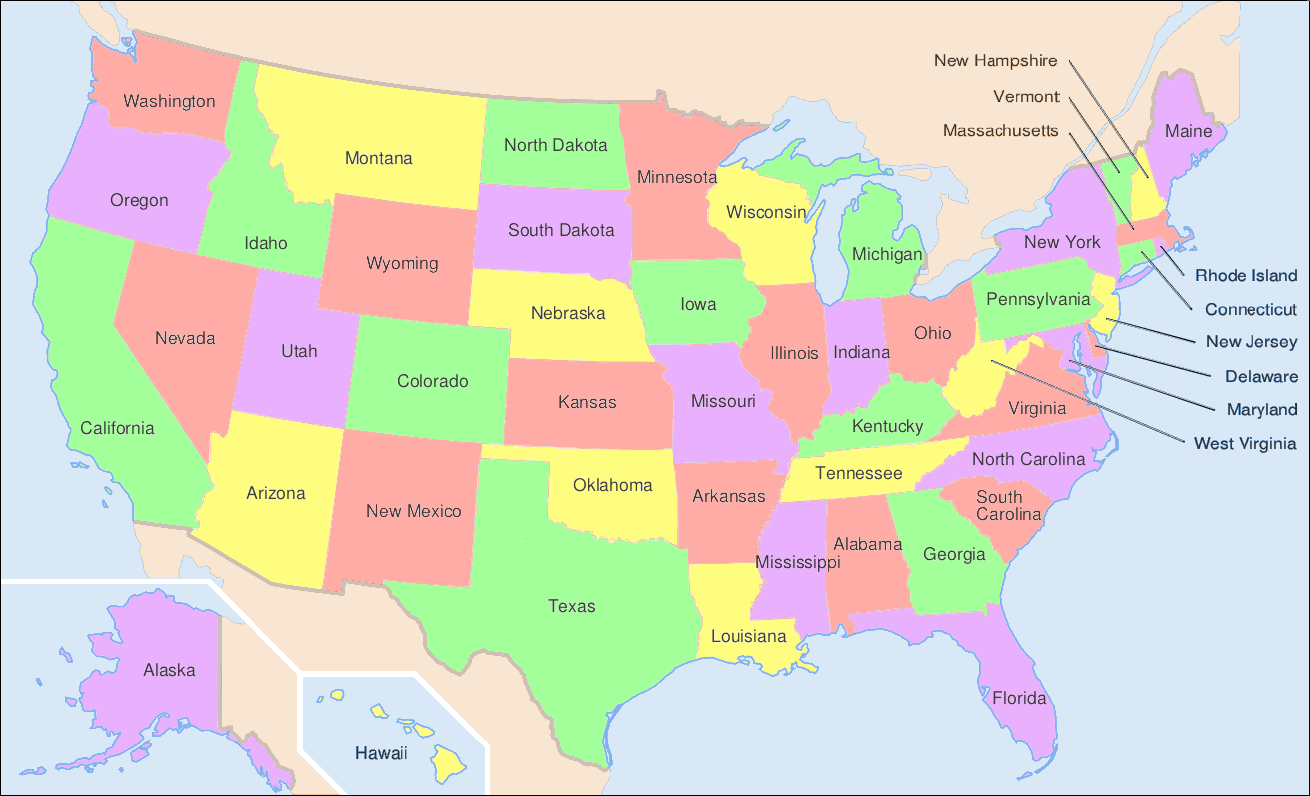
Table of Contents
- Definition and Core Components of State Homeowners Insurance
- Core Coverage Types in Standard Homeowners Policies
- State-Mandated Coverages and Exclusions
- Comparison of State-Specific Homeowners Insurance Policies
- Legal Distinctions Between Private Insurers and State-Run Programs
- Risk Factors and State-Specific Vulnerabilities in Homeowners Insurance
- Geographic and Climatic Patterns Influencing Natural Hazards
- Data-Driven Insights on Premium Correlations with Risk Exposure
- Five Underrated Risks and Insurer Mitigation Strategies
- State Government Interventions During Disasters and Their Impact on Claims Processing
- Policy Customization and Add-On Coverages in State Homeowners Insurance
- Five Optional Endorsements and Their State-Specific Applications
- Comparison of Standard vs. Premium Homeowners Policies Across States
- Filing a Claim for State-Specific Events: Process and Documentation
- Consumer Protections and State Regulations in Homeowners Insurance
- Regulatory Oversight and Enforcement by State Insurance Departments
- Three State-Specific Laws Shaping Policy Affordability and Availability
- Red Flags in Homeowners Insurance Policies and Regulatory Safeguards
- State-Run Insurance Marketplaces as Safety Nets
- Emerging Trends and Technological Influences in State Homeowners Insurance
- AI and Predictive Analytics in High-Risk Underwriting
- Smart Home Integrations and Insurer Discounts
- Traditional vs. Parametric Insurance Models in Disaster-Prone States
- Blockchain for Claims Verification in State-Specific Catastrophes
- FAQ
- state homeowners insurance florida?
- state homeowners insurance california?
- state house insurance?
- state house insurance quote?
- state house insurance calculator?
- state property insurance?
State homeowners insurance serves as a critical safeguard for property owners, yet its structure and protections vary dramatically across jurisdictions due to geographic risks, regulatory frameworks, and market dynamics. From hurricane-prone coastlines in Florida to wildfire-vulnerable regions in California, policyholders must navigate a complex landscape where state-specific mandates, optional endorsements, and emerging technologies collectively shape coverage outcomes. This exploration dissects the foundational elements of state-driven insurance policies, examines how natural hazards and legislative interventions influence premiums and exclusions, and highlights lesser-known customization options that can bridge coverage gaps. By analyzing data-driven risk correlations, claim processes, and technological innovations, the discussion equips stakeholders with actionable insights to secure tailored protection while mitigating financial exposure in an increasingly unpredictable environment.
The interplay between private insurers and state-run programs further complicates the equation, particularly in high-risk zones where market gaps persist. For instance, Florida’s Citizens Property Insurance Corporation and California’s FAIR Plan act as critical safety nets, yet their eligibility criteria and funding mechanisms often spark debates over affordability and sustainability. Meanwhile, advancements in AI-driven underwriting and parametric insurance models are redefining how claims are processed and payouts are triggered, offering both efficiency gains and new challenges in fraud detection. Understanding these nuances is essential for homeowners, insurers, and policymakers alike to adapt strategies that align with evolving risks and regulatory landscapes.
Definition and Core Components of State Homeowners Insurance
State homeowners insurance provides financial protection for residential property owners against specified risks, including damage to the dwelling, personal belongings, and liability for third-party injuries or property damage. Policies are standardized under the National Association of Insurance Commissioners (NAIC) model but are subject to state-specific regulations, which dictate mandatory coverages, exclusions, and policy terms. Core components typically include dwelling coverage, personal property coverage, liability protection, and additional living expenses (ALE). State laws further influence these policies by mandating supplementary coverages (e.g., flood insurance in high-risk zones) or imposing restrictions on deductibles, premiums, and insurer practices to address regional risks and market gaps.The structure of homeowners insurance policies reflects a balance between broad protection and risk management, with state-specific adaptations ensuring alignment with local hazards, economic conditions, and consumer needs. For instance, coastal states may require windstorm or hurricane deductibles, while regions prone to wildfires may enforce stricter building codes to qualify for coverage. Exclusions, such as earthquakes or mold, are often standardized but can vary by state, particularly in areas where these risks are endemic. Understanding these components and regulatory distinctions is critical for policyholders to assess adequacy, compliance, and potential gaps in protection.
Core Coverage Types in Standard Homeowners Policies
Standard homeowners insurance policies, typically categorized under HO-3 (Special Form), include four primary coverage types, each addressing distinct risks:- Dwelling Coverage: Protects the physical structure of the home, including attached garages, from perils such as fire, windstorms, vandalism, and certain water damage (excluding floods or earthquakes). Coverage limits are usually based on the home’s replacement cost, not market value, and may be adjusted by the insurer to reflect local construction costs or risk factors.
State-Mandated Coverages and Exclusions
State regulations introduce variations in mandatory coverages, exclusions, and policy terms to address regional risks and market inefficiencies. Key examples include:- Mandatory Coverages:
State laws also dictate deductible structures, such as percentage-based deductibles for hurricane damage in Florida or ordinance or law coverage (reimbursement for code-upgrade costs after a loss), which may be mandatory in certain jurisdictions.
Comparison of State-Specific Homeowners Insurance Policies
The following table compares key features of homeowners insurance policies in Florida, California, and Texas, highlighting coverage limits, premium averages, and common exclusions as of recent industry data (2023–2024). Variations reflect regional risks, regulatory frameworks, and insurer practices.| Feature | Florida | California | Texas |
|---|---|---|---|
| Average Annual Premium (HO-3) | $4,500–$7,000 (higher in coastal areas) | $1,200–$3,000 (varies by wildfire risk zone) | $2,500–$5,000 (higher in hurricane-prone regions) |
| Dwelling Coverage Limit | Replacement cost; state-mandated wind deductibles (5–10%) | Replacement cost; earthquake coverage often separate | Replacement cost; wind/hail deductibles (1–5% in high-risk zones) |
| Personal Property Coverage | 50–70% of dwelling limit; sub-limits for high-value items | 50–70% of dwelling limit; optional scheduled personal property | 50–70% of dwelling limit; standard exclusions apply |
| Liability Limits | $100,000–$500,000 (umbrella policies common) | $300,000 standard; higher limits available | $100,000–$300,000; TWIA policies may have lower limits |
| Additional Living Expenses (ALE) | 12–24 months; hurricane-related ALE may have separate limits | 12–24 months; wildfire-related ALE subject to endorsements | 12–24 months; windstorm-related ALE may be restricted |
| Common Exclusions | Floods, hurricanes (unless wind-related), mold (limited), sinkhole collapse (separate coverage) | Earthquakes, wildfires (unless wind-driven), water damage (unless sudden/accidental) | Floods, hurricanes (unless wind/hail), mold (limited), sewer backups (endorsement required) |
| State-Run Programs | Citizens Property Insurance Corporation (for high-risk properties) | California FAIR Plan (wind/wildfire coverage for high-risk areas) | Texas Windstorm Insurance Association (TWIA) (coastal windstorm coverage) |
Legal Distinctions Between Private Insurers and State-Run Programs
State homeowners insurance markets feature a dual system: private insurers and state-run programs, each serving distinct roles and addressing specific gaps in coverage. Private insurers dominate the market, offering standardized policies with optional endorsements, but they may withdraw from high-risk areas (e.g., coastal Florida or wildfire-prone California) due to unsustainable losses. In such cases, state-run programs (e.g., FAIR plans, wind pools) step in to provide basic coverage, though at higher premiums and with stricter underwriting.- Private Insurers:
Private insurers must comply with state laws on solvency, fair pricing, and consumer
Risk Factors and State-Specific Vulnerabilities in Homeowners Insurance
State homeowners insurance markets are shaped by geographic, climatic, and geological risks that vary significantly across regions. Natural hazards—such as hurricanes, wildfires, and earthquakes—create distinct vulnerabilities, influencing premiums, coverage exclusions, and insurer underwriting strategies. Data-driven analyses reveal correlations between risk exposure and insurance costs, with states like Louisiana, Colorado, and Alaska experiencing disproportionate financial burdens due to flood, wildfire, and permafrost-related damages. Additionally, underrated risks such as sinkholes and mudslides introduce further complexities, often leading to policy exclusions or specialized mitigation measures. State governments play a critical role in managing these risks through emergency declarations, reinsurance programs, and regulatory interventions, which directly impact claims processing and policyholder protections.Geographic and Climatic Patterns Influencing Natural Hazards
The distribution of natural hazards across the U.S. follows well-documented geographic and climatic trends, with coastal regions, mountainous areas, and fault lines presenting the highest risks. Hurricanes and storm surges dominate the Atlantic and Gulf Coasts, particularly in states like Florida, Louisiana, and North Carolina, where wind damage and flooding account for the majority of insurance claims. The Western U.S. is prone to wildfires, exacerbated by drought conditions, high temperatures, and dense vegetation, with California, Oregon, and Colorado experiencing severe annual losses. Earthquakes pose a significant threat in the Pacific Northwest, Alaska, and the New Madrid Seismic Zone, while tornadoes are prevalent in the Tornado Alley region, including Texas, Oklahoma, and Kansas. Flooding extends beyond coastal areas, affecting inland states such as Missouri, Arkansas, and Vermont due to riverine and flash flood events."The National Oceanic and Atmospheric Administration (NOAA) reports that the U.S. experienced 28 weather and climate disasters in 2023, each causing over $1 billion in damages, with hurricanes and wildfires contributing 60% of the total economic losses."Insurance premiums reflect these risks, with Florida homeowners paying an average of 2.5 times more for coverage than the national median due to hurricane exposure, according to the Insurance Information Institute (III). Similarly, California wildfire-prone regions see premiums 30–50% higher than state averages, while Alaska’s permafrost-related subsidence drives specialized policies with elevated costs. The Federal Emergency Management Agency (FEMA) categorizes flood risks into High-, Moderate-, and Low-Risk Zones, with premiums in High-Risk Zones exceeding $1,000 annually for standard policies, compared to $400–$600 in Low-Risk areas.
Data-Driven Insights on Premium Correlations with Risk Exposure
Empirical data demonstrates a direct correlation between natural hazard frequency, severity, and insurance premiums, with state-specific examples illustrating this relationship:- Louisiana: Flooding accounts for 40% of all insurance claims, with 80% of parishes designated as High-Risk by FEMA. The average flood insurance premium in Louisiana is $1,200 annually, compared to the national average of $700, driven by hurricane-induced storm surges and riverine flooding. The state’s Louisiana Floodplain Management Authority (LFMA) partners with insurers to offer discounts for mitigation measures, such as elevated foundations and flood-resistant materials, which can reduce premiums by 15–25%.
- Colorado: Wildfires have caused $2.1 billion in insured losses since 2010, with Denver and Boulder Counties experiencing the highest premium increases. Homeowners in Wildland-Urban Interface (WUI) zones pay $1,500–$3,000 more annually in premiums due to defensible space requirements and fire-resistant roofing mandates. Colorado’s FAIR Plan provides last-resort coverage for high-risk properties, though with limited liability caps.
- Alaska: Permafrost thaw and thermokarst subsidence (ground collapse) affect 60% of the state’s built environment, leading to foundation damage and structural instability. Insurers in Alaska often exclude permafrost-related claims or require specialized engineering reports before coverage. Premiums in Anchorage and Fairbanks exceed $2,500 annually, with 30% of policies including permafrost mitigation clauses that mandate regular soil stability assessments.
Five Underrated Risks and Insurer Mitigation Strategies
While high-profile hazards like hurricanes and wildfires dominate discussions, several lesser-known risks significantly impact homeowners insurance markets. These risks often lead to policy exclusions, elevated premiums, or specialized endorsements to manage insurer liabilities.-
Sinkholes (Florida, Alabama, Missouri, Texas, Tennessee)
Florida alone experiences 10–20 sinkholes annually, causing $300 million in damages since 2010. Insurers in Florida exclude sinkhole coverage under standard policies, requiring separate endorsements with $50,000–$100,000 deductibles. The Florida Sinkhole Research Institute collaborates with insurers to identify high-risk areas using LiDAR mapping and geological surveys. Mitigation includes avoiding construction over karst terrain and installing drainage systems to reduce groundwater infiltration. -
Mudslides and Debris Flows (California, Oregon, Washington, Hawaii)
California’s 2018 Camp Fire triggered 1,000+ mudslide incidents, costing insurers $1.5 billion in additional claims. Insurers in high-slope regions require geotechnical reports before issuing policies and may exclude mudslide damage unless the property complies with land-use zoning laws. Hawaii’s volcanic mudflows (lahars) lead to automatic policy cancellations in high-risk zones, with USGS hazard maps determining underwriting decisions. -
Hailstorms (Texas, Colorado, Nebraska, Kansas)
Texas hailstorms cause $10 billion in annual insured losses, with Dallas-Fort Worth experiencing 50% more hail events than the national average. Insurers in hail-prone states limit coverage for roof damage unless impact-resistant materials (e.g., Class 4 shingles) are installed. Texas’s Hail Research Institute provides insurers with storm verification data to reduce fraudulent claims, while reinsurance pools cap individual insurer losses. -
Coastal Erosion (North Carolina, South Carolina, Maine)
North Carolina loses 3–5 feet of coastline annually due to erosion, with Hatteras Island facing $200 million in annual property losses. Insurers exclude erosion-related claims unless the policyholder retains an erosion management plan approved by state agencies. South Carolina’s Beachfront Management Act requires dune restoration and setback lines, reducing premiums by 20% for compliant properties. -
Winter Storms and Ice Dams (Northern U.S., Midwest, Northeast)
Texas’s 2021 Winter Storm Uri caused $19 billion in insured losses, with ice dam damage in Minnesota and New York adding $500 million annually in claims. Insurers in cold climates mandate proper attic insulation, ice shields, and gutter guards to prevent damage. New York’s Ice Dam Prevention Law requires attic ventilation systems in new constructions, reducing claims by 35% in high-risk areas.
State Government Interventions During Disasters and Their Impact on Claims Processing
State governments play a pivotal role in mitigating insurance market disruptions following disasters through emergency declarations, reinsurance programs, and regulatory reforms. These interventions directly influence claims processing efficiency, policyholder affordability, and insurer solvency."The National Association of Insurance Commissioners (NAIC) reports that state-run reinsurance pools reduce insurer insolvency rates by 40% in disaster-prone states, while emergency declarations accelerate claims payments by 30–50 days."Key state-level interventions include:
-
Emergency Declarations and State of Emergency Orders
Governors can declare states of emergency, triggering mandatory insurer cooperation with claims processing. For example:
- Florida’s
- Florida and Texas see the largest premium jumps for premium policies due to hurricane/windstorm risks, with insurers often bundling endorsements (e.g., hurricane shutters) into higher-tier plans.
- California premiums reflect earthquake risk, where standard policies exclude quake damage entirely unless an endorsement is purchased.
- Illinois and Ohio prioritize water damage add-ons, as aging infrastructure increases backup risks.
- Liability limits are critical in urban areas (e.g., New York, Los Angeles) where lawsuits are more common, justifying premium upgrades.
- Deadline: Most states require claims to be filed within 30–60 days of the incident. For example:
- Kansas (hail): 30 days (state insurance regulations).
- North Carolina (windstorm): 60 days (hurricane season extensions may apply).
- Florida (hurricane): 14 days for catastrophic events (state law).
- Documentation Required:
- Police report (for vandalism/theft).
- Photographs/videos of damage (timestamped).
- Repair estimates (obtained before filing in some states).
- Proof of residence (e.g., mortgage statement, deed).
- The insurer assigns an adjuster, who may conduct an on-site inspection within 5–14 business days. In high-risk states (e.g., Louisiana post-hurricane), delays are common due to adjuster shortages.
- State-Specific Notes:
- Texas (windstorm): Adjusters must follow the Texas Department of Insurance (TDI) guidelines for wind vs. hail differentiation.
- Pennsylvania (flood): FEMA may require additional documentation if partial flood coverage is claimed.
- Approval timelines vary:
- Standard claims (e.g., fire): 15–30 days.
- Catastrophic events (e.g., tornado in Missouri): 60–90 days.
- Funds are typically issued as:
- Actual Cash Value (ACV): Standard policy payout (depreciation applied).
- Replacement Cost: Premium policy payout (no depreciation).
- Disputes: Homeowners may appeal denials within 30–60 days, with some states (e.g., Florida) offering independent appeals through the Office of Insurance Regulation.
- Insurers may direct repairs to approved contractors, especially in disaster zones (e.g., FEMA-designated areas).
- Lesser-Known Requirement: In North Carolina, wind
- Regulate rate filings with actuarial justification requirements.
- Cap premium increases based on inflation and underwriting costs.
- Mandate prior approval for insurer mergers or rate hikes exceeding 10%. Impact: While Proposition 103 stabilized rates in the 1990s, it led to insurer withdrawals from high-risk areas (e.g., wildfire zones), necessitating the California FAIR Plan as a last-resort marketplace.
- Expanded eligibility for private insurers to write policies in Citizens’ portfolio, reducing reliance on the state-backed insurer.
- Limited premium increases to 5% annually for existing Citizens policyholders.
- Required insurers to offer coverage in all counties, preventing market exits. Impact: Private insurer participation in Citizens’ market rose from 1% in 2021 to 40% in 2023, though affordability remains a challenge due to high reinsurance costs.
- Mandatory participation for insurers in flood-prone zones.
- Subsidized premiums for low-income policyholders.
- State-backed reinsurance to stabilize rates post-disaster. Impact: After Hurricane Sandy (2012), the program issued $1.2 billion in claims, preventing a statewide insurance crisis.
- Unjustified Non-Renewal or Cancellation Regulatory Basis: Most states require 30–60 days’ written notice for non-renewals, with prohibitions on cancellations due to minor claims or code violations unless remedied.
- Example: Texas Insurance Code §502.002 bars insurers from canceling policies for "nuisance" claims (e.g., $500 hail damage) without proof of fraud.
- Action: Policyholders can file a complaint with the state DOI and cite the insurer’s failure to provide a valid reason under §502.051.
- Example: Florida’s OIR found Geico violated claim handling laws in 2020 by denying mold damage claims without expert assessments, leading to a $1.2 million settlement.
- Model Dispute Language: > "Per [State Code §XXX], my claim (Claim #XXX) was denied without a reasonable investigation or explanation. I request a formal review under [State DOI’s Complaint Process], citing the insurer’s failure to comply with [statutory timeline/requirement]."
- Example: California’s Insurance Code §790.03 prohibits exclusions for "acts of God" in earthquake policies, as seen in disputes after the 2019 Ridgecrest earthquakes.
- Action: Policyholders can file a deceptive practices complaint with the state DOI, attaching the policy language in question.
- Example: Massachusetts’ Division of Insurance blocked Liberty Mutual’s 2022 rate hike in wildfire zones, citing lack of actuarial support.
- Model Dispute Language: > "The proposed rate increase of [X]% exceeds statutory limits under [State Code §XXX] and lacks sufficient justification. I request a hearing before the [State DOI] to challenge the filing."
- California’s FAIR Plan (Fair Access to Insurance Requirements) Purpose: Provides basic property insurance (dwelling and personal property) in areas where private insurers refuse coverage due to wildfire, earthquake, or urban decay risks.
- Residents of high-risk zones where private insurers have non-renewed or canceled policies in the past 12 months.
- Property owners who have applied for private coverage but been denied.
- Exclusions: Flood and earthquake risks (covered separately by Cal-EMA’s Earth
- Dynamic pricing adjustments based on real-time disaster alerts (e.g., NOAA hurricane tracks).
- Automated fraud detection in claims, reducing payout delays in high-volume catastrophe events.
- Personalized risk mitigation recommendations, such as Florida’s "Fortify Florida" program, which uses AI to suggest cost-effective upgrades.
- Leak detectors (e.g., Moen Smart Valves) that prevent water damage claims.
- Impact sensors (e.g., SolarGuard) for hail and wind detection, reducing false claims in states like Texas and Colorado.
- Smart thermostats (e.g., Nest) that optimize energy use, lowering fire risks in California and Oregon.
- Insurer-sponsored rebates for device installation (e.g., Florida’s "My Safe Florida Home" program).
- Usage-based pricing models, where discounts scale with device functionality (e.g., Allstate’s "Drivewise" for home safety).
- Regulatory incentives, such as California’s SB 800, which mandates insurance discounts for approved wildfire-hardening measures, including smart sprinkler systems.
- Texas: Hail claims processed via traditional adjuster visits, leading to backlogs.
- Florida: Hurricane claims delayed by disputes over wind vs. water damage.
- Oklahoma: Parametric earthquake insurance tied to USGS seismic alerts.
- California: Wildfire parametric policies triggered by CAL FIRE incident reports.
- Hailstorms in Texas, where parametric triggers based on Doppler radar data can expedite claims.
- Wildfires in Colorado, where policies tied to Red Flag Warnings provide immediate liquidity.
- Earthquakes in Alaska, where seismic sensor data replaces lengthy damage assessments.
- Drone imagery of storm-damaged roofs.
- IoT sensor data from impact detectors.
- Public weather records (e.g., NOAA storm reports).
- Regulatory skepticism: State insurance commissions (e.g., Texas Department of Insurance) require rigorous compliance with existing laws, such as unfair claims practices statutes.
- Interoperability challenges: Legacy insurance systems lack integration with blockchain networks, necessitating costly infrastructure upgrades.
- Data privacy concerns: Storing sensitive claim details on a public ledger raises compliance issues under GDPR-like state regulations (e.g., California’s CCPA).
Policy Customization and Add-On Coverages in State Homeowners Insurance
State homeowners insurance policies are rarely one-size-fits-all, particularly when accounting for regional risks, property values, and lifestyle factors. Policy customization allows homeowners to adapt coverage to their specific needs, whether mitigating high-risk exposures in hurricane-prone Florida or protecting high-value assets in urban centers like New York. Optional endorsements (or riders) extend standard policies to address gaps, while premium policies offer broader protection at a higher cost. Understanding these customization options—along with the claims process for state-specific events—ensures homeowners align their coverage with local vulnerabilities and financial realities.The relevance of add-on coverages varies significantly by geography. For instance, a home in coastal Texas may require windstorm endorsements, whereas a property in California might prioritize earthquake coverage. Below, five common endorsements are examined, followed by a comparative analysis of standard vs. premium policies across states. The claims process for state-specific events is detailed to highlight documentation and deadlines, while lesser-known add-ons are summarized to address niche but critical coverage gaps.
Five Optional Endorsements and Their State-Specific Applications
Optional endorsements allow policyholders to tailor coverage to regional risks, asset values, or unique exposures. Below are five widely used endorsements, with state-specific examples illustrating their importance.Scheduled Personal Property (Floater) Endorsement
This endorsement provides additional coverage for high-value items (e.g., jewelry, art, collectibles) that exceed standard policy limits. In states like New York or Massachusetts, where urban homes often contain expensive jewelry or electronics, this rider is essential. For example, a $50,000 diamond ring may require a separate floater, as standard policies typically cap personal property claims at $1,500–$2,500. In contrast, rural areas with lower asset concentrations may find this endorsement less critical unless specific valuables (e.g., antiques, firearms) are present.
Equipment Breakdown Coverage
This rider covers mechanical failures in home systems (e.g., HVAC, plumbing, electrical) caused by sudden accidents. In states with extreme temperature fluctuations—such as Minnesota (freezing pipes) or Arizona (AC malfunctions)—this add-on prevents costly repairs from being excluded under standard policies. For instance, a burst pipe in winter could lead to $10,000 in water damage, which may not be fully covered without this endorsement.
Water Backup and Sump Pump Overflow
Flooding from sewer backups or sump pump failures is excluded in most standard policies. States with aging infrastructure (e.g., Illinois, Ohio) or high rainfall (e.g., Louisiana, Washington) benefit significantly from this rider. A 2022 Insurance Information Institute report noted that water backup claims averaged $7,000 nationally, with some states experiencing higher frequencies due to outdated drainage systems.
Identity Theft Protection
While not directly tied to property damage, this endorsement reimburses costs associated with identity theft, such as legal fees, credit monitoring, and lost wages. Urban areas with higher crime rates (e.g., Los Angeles, Chicago) see greater demand for this coverage, whereas rural regions may prioritize it less unless cybersecurity risks (e.g., remote work setups) are present.
Hurricane Shutters and Reinforced Roofing
Exclusive to coastal and high-wind states (e.g., Florida, North Carolina, Texas), this endorsement covers the cost of installing permanent storm shutters or impact-resistant roofing. Standard policies may reimburse damage but rarely preemptive upgrades. For example, Florida’s Building Code requires reinforced roofs in hurricane zones, but insurers may offer discounts for proactive modifications, effectively subsidizing the endorsement through premium savings.
Comparison of Standard vs. Premium Homeowners Policies Across States
Standard and premium policies differ in coverage breadth, exclusions, and cost, with variations influenced by state regulations, risk profiles, and insurer practices. The table below compares identical home values ($400,000 dwelling, $100,000 personal property) in three high-risk states, highlighting key differences.| Feature | Standard Policy (HO-3) | Premium Policy (HO-5 or Enhanced HO-3) | Cost Differential (Annual Premium) |
|---|---|---|---|
| Coverage Breadth | Named-perils for dwelling; actual cash value for personal property. | Open-perils for dwelling; replacement cost for personal property. | +$1,200–$2,500 (Florida) |
| Windstorm/Hail | Limited coverage; may require separate endorsement. | Full coverage with higher sub-limits (e.g., $10,000 vs. $5,000). | +$800–$1,500 (Texas) |
| Water Damage | Excludes flood/sewer backup; limited for burst pipes. | Includes water backup; higher sub-limits for plumbing. | +$500–$1,200 (Illinois) |
| Liability Limits | $300,000 per occurrence. | $500,000–$1M per occurrence. | +$300–$800 (California) |
| Additional Living Expenses | 12-month limit at 20% of dwelling coverage. | 24-month limit at 30% of dwelling coverage. | +$400–$1,000 (Hurricane-prone states) |
| Exclusions | Earthquake, mold, sinkhole, ordinance/law updates. | Optional endorsements for earthquake/mold; higher ordinance coverage. | +$1,000–$2,000 (Florida/Texas) |
| Deductible Options | $1,000–$2,500 standard. | $500–$1,000 with higher coverage tiers. | Varies by insurer (often neutral). |
Filing a Claim for State-Specific Events: Process and Documentation
The claims process for state-specific events (e.g., hail in Kansas, windstorm in North Carolina) follows a structured workflow but includes regional variations in deadlines and required documentation. Below is a step-by-step breakdown, with state-specific nuances highlighted.1. Initial Reporting
2. Inspection and Assessment
3. Claim Approval and Disbursement
4. Repair Coordination

Consumer Protections and State Regulations in Homeowners Insurance
State insurance departments play a critical role in safeguarding homeowners by enforcing regulations that ensure fairness, transparency, and accountability in the insurance market. These departments—such as the Texas Department of Insurance (DOI), New York State Department of Financial Services (DFS), and California Department of Insurance (CDI)—monitor insurer practices, investigate consumer complaints, and implement laws that address systemic risks like rate hikes, policy cancellations, and claim denials. Their oversight ensures that insurers comply with statutory requirements while providing mechanisms for policyholders to challenge unfair practices. Below, the focus shifts to regulatory enforcement mechanisms, landmark state-specific laws, and tools available to consumers to navigate disputes, alongside the role of state-run insurance marketplaces as safety nets in high-risk areas.Regulatory Oversight and Enforcement by State Insurance Departments
State insurance departments employ a multi-layered approach to protect consumers, combining proactive monitoring, reactive complaint resolution, and corrective actions against non-compliant insurers. Key enforcement tools include:- Rate Review Processes
Departments evaluate proposed rate increases for actuarial soundness and affordability. For example, the New Jersey Department of Banking and Insurance (DOBI) requires insurers to justify rate hikes through public hearings, while Florida’s Office of Insurance Regulation (OIR) mandates a 90-day notice period for non-renewals tied to rate changes. In California, Proposition 103 (1988) grants the CDI authority to reject unreasonable rate filings, ensuring premiums align with market conditions rather than insurer profits.
- Complaint Resolution and Mediation
Most states operate complaint resolution systems where consumers can file grievances against insurers for delays, denials, or unfair practices. Texas DOI offers a Consumer Assistance Program to mediate disputes, while New York DFS provides a Consumer Bill of Rights outlining timelines for claim responses (e.g., 15 days for acknowledgment, 45 days for claim decisions). Failure to resolve complaints within statutory timelines can trigger fines or license suspensions.
- Market Conduct Examinations
Departments conduct random audits of insurers to verify compliance with licensing laws, advertising standards, and claims handling. Arizona’s Department of Insurance found that State Farm violated cancellation notice requirements in 2022, leading to a $1.5 million settlement for affected policyholders. Similarly, Massachusetts’ Division of Insurance imposed a $2 million penalty on Allstate in 2021 for improper non-renewal practices in wildfire-prone areas.
Three State-Specific Laws Shaping Policy Affordability and Availability
State legislatures and ballot initiatives have introduced reforms directly addressing homeowners insurance crises, particularly in disaster-prone regions. Three notable examples demonstrate their impact:- California’s Proposition 103 (1988)
This landmark initiative granted the California Department of Insurance authority to:
- Florida’s Citizens Property Insurance Corporation Reforms (2021–2023)
Following Hurricane Ian (2022), Florida enacted HB 1255 and SB 76, which:
- New Jersey’s Fair Access to Insurance Requirements (FAIR) Act (1974) and Flood Insurance Program (2019)
New Jersey’s Beach and Inland Flood Insurance Program provides coverage in high-risk coastal areas where private insurers refuse policies. Key provisions include:
Red Flags in Homeowners Insurance Policies and Regulatory Safeguards
State insurance codes prohibit deceptive or abusive practices, but policyholders must recognize warning signs and know how to challenge them. Below are common red flags regulated by state laws, along with model dispute language for policyholders to use when contesting violations.Regulated Red Flags in Homeowners Policies
- Delayed or Denied Claims Without Proper Justification
Regulatory Basis: States mandate timely claim processing (e.g., New York’s 45-day rule) and require insurers to provide written explanations for denials, including references to policy exclusions.
- Misleading Policy Exclusions or Fine Print
Regulatory Basis: Unconscionable contract clauses (e.g., waiving statutory rights) are void under Uniform Commercial Code §2-302 in many states.
- Excessive or Unjustified Rate Increases
Regulatory Basis: States like New Jersey require 120-day notice for rate hikes over 10%, while California’s Proposition 103 allows the CDI to reject filings deemed excessive.
State-Run Insurance Marketplaces as Safety Nets
In regions where private insurers withdraw due to high risk, state-run marketplaces provide last-resort coverage with standardized policies and subsidized rates. These programs are designed to stabilize markets during crises but often come with eligibility restrictions and higher premiums. Below are two key examples and their operational frameworks:Function and Eligibility of State Marketplaces
Eligibility Criteria:
Emerging Trends and Technological Influences in State Homeowners Insurance
The integration of advanced technologies is fundamentally transforming homeowners insurance, particularly in states vulnerable to high-frequency natural disasters. Artificial intelligence (AI) and predictive analytics now enable insurers to refine underwriting models with unprecedented precision, while smart home devices offer tangible risk mitigation strategies. Meanwhile, alternative insurance models like parametric coverage are gaining traction in disaster-prone regions, addressing the limitations of traditional indemnity-based policies. Blockchain technology, though still in early adoption, holds promise for streamlining claims processing in states with complex catastrophe risks, such as Texas hailstorms or Florida hurricanes."Technological innovation in insurance is not merely an efficiency upgrade—it represents a paradigm shift in risk assessment, claims handling, and policyholder engagement."
AI and Predictive Analytics in High-Risk Underwriting
AI-driven underwriting leverages machine learning to analyze vast datasets, including historical claim patterns, weather forecasts, and property-specific vulnerabilities. In Florida, insurers now use hurricane exposure models that integrate real-time wind speed data, flood zone revisions, and structural resilience scores to dynamically adjust premiums. For instance, companies like Florida Citizens Property Insurance Corporation employ AI to identify properties with outdated mitigation measures, offering incentives for upgrades such as reinforced roofs or impact-resistant windows.In California, wildfire risk assessment has evolved beyond proximity to wildland-urban interfaces (WUI). Predictive analytics now factor in vegetation density, ember susceptibility, and home hardening features (e.g., ember-resistant vents, fire-resistant roofing). Insurers like State Farm and Allstate use proprietary models to classify properties into risk tiers, with discounts for homes meeting California’s Wildfire Mitigation Guidelines. Similarly, Oklahoma insurers apply AI to earthquake risk scoring, cross-referencing seismic activity data with building codes to prioritize retrofitting for older structures.
Key applications of AI in state-specific underwriting include:
Smart Home Integrations and Insurer Discounts
The proliferation of IoT-enabled smart home devices is creating a feedback loop between risk reduction and insurance affordability. Insurers in Arizona and Nevada, where wildfires and extreme heat pose significant threats, now offer discounts of 5–15% for properties equipped with:In Arizona, Farmers Insurance partners with ADT to provide discounts for integrated security systems that include smoke alarms, CO detectors, and water leak sensors. Similarly, Nevada’s State Farm offers tiered discounts based on the number of connected devices, with the highest savings (up to 20%) for homes with comprehensive smart safety suites.
The adoption of these technologies is driven by:
Traditional vs. Parametric Insurance Models in Disaster-Prone States
Traditional homeowners insurance operates on an indemnity-based model, where claims are evaluated individually after a disaster, often leading to delays in payouts. In contrast, parametric insurance triggers automatic payments based on predefined conditions (e.g., earthquake magnitude, hurricane wind speed), offering faster relief. Below is a comparative analysis of the two models in disaster-prone states:| Feature | Traditional Indemnity Model | Parametric Insurance Model |
|---|---|---|
| Payout Trigger | Post-disaster assessment of actual damage (e.g., roof repairs after a hailstorm). | Predefined event thresholds (e.g., earthquake sensor detecting 5.0+ magnitude in Oklahoma). |
| Speed of Claims Processing | Weeks to months (e.g., Florida hurricane claims can take 6–12 months). | Hours to days (e.g., parametric payouts for California wildfires within 72 hours). |
| Coverage Scope | Limited to insured perils; exclusions apply (e.g., flood damage in Texas). | Broad event-based coverage (e.g., parametric policies for wind, hail, or seismic activity). |
| Cost to Policyholder | Higher premiums due to administrative overhead and fraud risks. | Lower premiums (often 20–40% cheaper) but may require separate purchase. |
| State-Specific Examples | ||
| Adoption Barriers | Complex claims process, moral hazard concerns. | Limited insurer offerings, regulatory uncertainty, and underwriting challenges for hybrid models. |
Blockchain for Claims Verification in State-Specific Catastrophes
Blockchain technology is being explored to enhance transparency, speed, and fraud prevention in catastrophe claims, particularly in states where traditional processes are overwhelmed. For example, Texas hailstorms generate millions of claims annually, often leading to disputes over damage severity. Blockchain-based solutions, such as those piloted by Lemonade and Etherisc, use smart contracts to automate claims verification by cross-referencing:In Florida, Blockchain for Disaster Resilience (B4DR) is testing a platform where hurricane damage claims are recorded on an immutable ledger, reducing fraudulent inflations of pre-storm property values. Similarly, California’s wildfire claims could benefit from blockchain’s ability to timestamp pre- and post-event satellite imagery, ensuring fair assessments for homes near burn scars.
Key barriers to widespread adoption include:
Despite these hurdles, pilot programs in Louisiana (hurricane claims) and Oregon (wildfire verification)
State homeowners insurance is not a one-size-fits-all solution but a dynamic ecosystem shaped by geography, legislation, and technological progress. The core components—dwelling protection, personal property coverage, and liability shields—remain constant, yet their application diverges sharply from one state to another, reflecting local vulnerabilities and political priorities. Whether grappling with the financial repercussions of a sinkhole in Florida or the logistical hurdles of filing a wildfire claim in Colorado, policyholders must proactively assess optional endorsements, state-specific exclusions, and emerging tools like smart home integrations to fortify their defenses. As AI and blockchain continue to reshape underwriting and claims processing, the industry stands at a crossroads where transparency, adaptability, and consumer education will determine the resilience of homeowners insurance in the face of escalating natural disasters. By leveraging data-driven insights and regulatory awareness, stakeholders can navigate this evolving terrain to secure policies that not only comply with state mandates but also anticipate future risks with precision.
FAQ
state homeowners insurance florida?
Q: What are the key details about Florida’s state-backed homeowners insurance programs?
state homeowners insurance california?
Q: Does California have a state-run homeowners insurance program, and how does it work?
state house insurance?
Q: What is state house insurance, and how does it differ from private homeowners insurance?
state house insurance quote?
Q: How do I get a quote for state house insurance?
state house insurance calculator?
Q: Is there an online calculator for estimating state house insurance costs?
state property insurance?
Q: What is state property insurance, and when would I need it?
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.