Modular Home Insurance Quotes Key Insights And Comparison Guide

Table of Contents
- Understanding Modular Home Insurance Basics
- Core Differences Between Modular and Traditional Home Insurance Policies
- Comparison of Five Key Modular Home Insurance Providers
- Three Common Misconceptions About Modular Home Insurance
- Factors Influencing Modular Home Insurance Quotes
- Six Non-Negotiable Variables in Modular Home Insurance Quotes
- Step-by-Step Self-Assessment of Modular Home Risk Profile
- Methods to Obtain and Compare Modular Home Insurance Quotes
- Side-by-Side Quote Comparison Template
- Automating Quote Comparisons with Free Tools
- Leveraging Modular Home Certifications for Lower Quotes
- Script Template for Emailing Insurers to Request Quotes
Securing accurate modular home insurance quotes demands a nuanced understanding of policy structures, risk assessments, and provider distinctions that often diverge from traditional home insurance frameworks. Unlike conventional dwellings, modular homes present unique underwriting challenges—from foundation vulnerabilities to manufacturer-specific liabilities—requiring homeowners to navigate exclusions, deductible tiers, and regional coverage gaps with precision. This guide dissects the critical variables insurers evaluate, from structural compliance to disaster-prone locations, while equipping readers with actionable tools to compare quotes, challenge misconceptions, and leverage certifications to optimize premiums.
The process begins with demystifying modular insurance basics, where coverage limits and add-ons vary sharply by provider, and common myths—such as assuming all modular homes carry lower premiums—can lead to costly oversights. A structured comparison of top insurers reveals how specialty add-ons for flood or wind damage, paired with location-specific exclusions, directly influence annual costs. Equally critical is the self-assessment of risk factors, where elements like steel framing versus wood construction or proximity to fire stations can shift quotes by tens of thousands annually. Real-world case studies further illustrate how modular home age, custom modifications, and certification adherence create divergent pricing landscapes.
Understanding Modular Home Insurance Basics
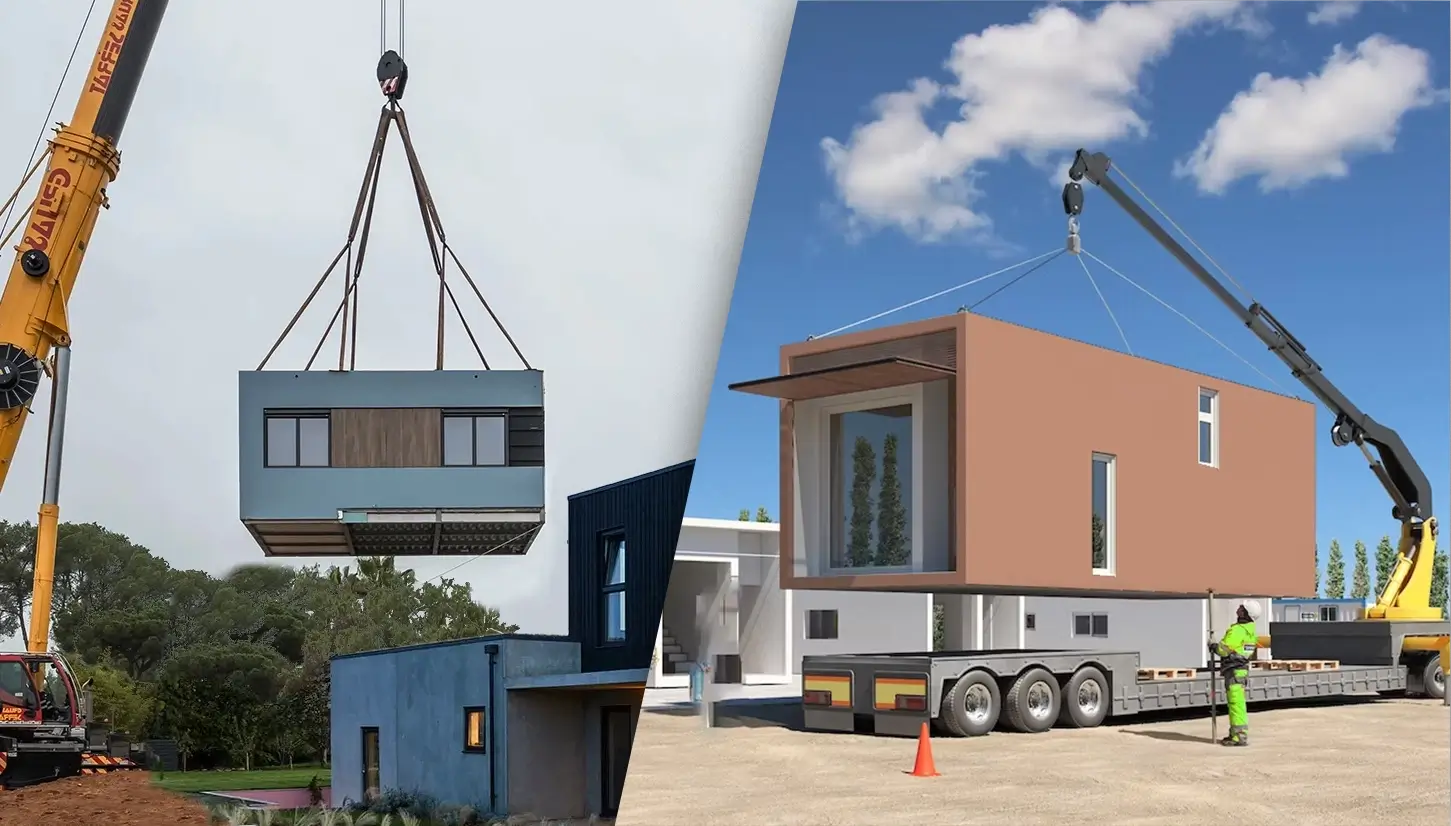
Modular home insurance differs fundamentally from traditional home insurance due to variations in construction, risk profiles, and regulatory frameworks. While conventional homes are typically built on-site, modular homes are prefabricated in controlled environments and assembled at the final location, which affects underwriting criteria. Insurers assess modular homes based on factors such as manufacturer certifications, foundation stability, and transportation risks—elements absent in traditional policies. Coverage exclusions often target assembly errors, transportation damage, or foundation-related claims, while deductibles may vary by module size and regional hazard exposure. Premium structures reflect these nuances, with modular policies occasionally offering lower costs for standardized construction but higher costs for custom or high-risk placements.Modular home insurance policies prioritize construction integrity and transportation safety, leading to distinct differences in coverage scope. Traditional policies focus on dwelling protection, personal property, and liability, whereas modular policies may exclude foundation failures unless explicitly added. Deductibles in modular insurance often correlate with module value rather than square footage, and premiums can fluctuate based on manufacturer reputation and assembly location risks. For instance, a modular home in a flood-prone area may incur higher premiums than a traditional home in the same zone due to perceived vulnerabilities in foundation design.
Core Differences Between Modular and Traditional Home Insurance Policies
Modular home insurance policies incorporate risk-specific adjustments that traditional policies overlook. Key distinctions include:- Coverage Exclusions:
Modular policies frequently exclude transportation-related damage (e.g., road accidents during module delivery) unless a specialized add-on is purchased. Traditional policies rarely address transportation risks, as construction occurs on-site. Another exclusion unique to modular insurance involves assembly defects, which may not be covered under standard dwelling policies.
- Deductible Structures:
Deductibles in modular insurance are often percentage-based (e.g., 2–5% of the home’s insured value) rather than flat-rate, reflecting the modular construction’s modular valuation approach. Traditional policies typically use fixed deductibles (e.g., $1,000–$5,000).
- Premium Calculation Factors:
Modular premiums consider manufacturer warranties, assembly timelines, and regional building codes, whereas traditional policies prioritize age of materials and local crime rates. For example, a modular home built by a HUD-code-certified manufacturer may qualify for lower premiums due to standardized quality controls.
- Additional Living Expenses (ALE):
Modular policies may impose stricter limits on ALE coverage if the home is deemed temporarily uninhabitable during assembly, unlike traditional policies that assume immediate occupancy.
Comparison of Five Key Modular Home Insurance Providers
The modular home insurance market features providers specializing in manufacturer-backed policies, regional risk mitigation, and customizable add-ons. Below is a structured comparison of five leading insurers, highlighting their coverage limits, specialty offerings, and geographic availability.| Provider Name | Base Coverage Type | Specialty Add-Ons | Average Annual Cost Range | Notable Exclusions |
|---|---|---|---|---|
| Progressive Modular Homes Program | Dwelling + Personal Property (HO-3 equivalent) |
|
$800–$2,500 (varies by module count and location) |
|
| USAA Modular Home Insurance | Comprehensive (HO-5 equivalent for military-affiliated) |
|
$1,200–$3,000 (military discounts apply) |
|
| State Farm Modular Homeowners Policy | HO-3 with modular-specific endorsements |
|
$900–$2,800 (bundling discounts available) |
|
| Allianz Modular Risk Solutions | Customizable (HO-3 or HO-5 with modular riders) |
|
$1,500–$4,000 (high-end modular projects) |
|
| Farmers Modular Homeowners Insurance | HO-3 with modular assembly coverage |
|
$750–$2,200 (rural/low-risk areas) |
|
Three Common Misconceptions About Modular Home Insurance
Modular home insurance is frequently misunderstood due to its niche nature and evolving market. Below are three persistent misconceptions, debunked with data-driven clarifications and real-world examples.Modular homes are always cheaper to insure than traditional homes.
Modular insurance costs are not inherently lower and depend on location-based risk factors, manufacturer reputation, and customization levels. A 2023 study by the Insurance Information Institute (III) found that modular homes in high-wind zones (e.g., Florida) incurred 15–20% higher premiums than traditional homes due to perceived vulnerabilities in roofing and wall connections. Conversely, in low-risk areas (e.g., Midwest), modular homes with HUD-certified manufacturers achieved 5–10% lower premiums than traditional builds, primarily due to standardized quality controls and reduced on-site labor risks.Modular policies automatically cover transportation damage.
Transportation damage is excluded by default in most modular policies unless a specialized add-on (e.g., Progressive’s "Module Transit Protection") is purchased
Factors Influencing Modular Home Insurance Quotes
Modular home insurance quotes are determined by a complex interplay of structural, locational, and construction-specific variables that differ significantly from traditional site-built homes. Insurers evaluate these factors to assess risk exposure, directly impacting premiums, coverage limits, and deductible structures. Unlike conventional homes, modular constructions—with their prefabricated components, varied foundation types, and customizable layouts—introduce unique risk profiles that require meticulous scrutiny. Understanding these non-negotiable variables allows homeowners to anticipate quote variations and proactively mitigate potential cost drivers before engaging with insurers.The six most critical variables insurers prioritize, ranked by their influence on premium calculations, include foundation type, geographic hazard exposure, manufacturer warranty terms, construction materials, home age, and custom modifications. These factors are not static; their interplay creates a dynamic risk assessment framework. For instance, a steel-framed modular home in a flood-prone area with a limited manufacturer warranty may yield a 30–50% higher quote than an identical structure in a low-risk zone with full warranty coverage. Below, these variables are explored in depth, alongside actionable steps for self-assessment and a prioritization framework for disclosure.
Six Non-Negotiable Variables in Modular Home Insurance Quotes
Insurers treat modular homes as distinct assets due to their prefabricated nature, transportation logistics, and assembly processes. The following six variables are universally scrutinized, with their impact ranked from highest to lowest based on industry underwriting standards and claims data. Each factor interacts with others—e.g., a wood-framed modular home in a wildfire-prone area with no fire-resistant modifications will incur higher premiums than a steel-framed counterpart in the same location.
Key Principle: Insurers apply a "layered risk model" where no single factor determines the quote, but their cumulative effect dictates underwriting decisions. For example, a modular home in a seismic zone with a concrete slab foundation may offset some earthquake risk, while the same home with wood framing and no retrofitting may negate that benefit entirely.
- Foundation Type and Structural Stability
The foundation anchors the modular home to the site and dictates resilience against natural forces. Insurers classify foundations into three tiers:
- Tier 1 (Lowest Risk): Reinforced concrete slabs or deep pilings (common in seismic zones).
- Tier 2 (Moderate Risk): Gravel pads or pier-and-beam systems (standard for most modular builds).
- Tier 3 (Highest Risk): Skid-mounted or shallow foundations (elevated risk of shifting or water damage).
Example: A modular home in California with a Tier 1 foundation may qualify for a 15% discount on earthquake coverage, whereas a Tier 3 foundation could increase premiums by 25% or more.- Distance from Emergency Services and Hazard Proximity
Proximity to fire stations, hospitals, and flood barriers directly influences response-time-based risk. Insurers use FEMA flood maps, wildfire threat indices, and emergency service radius data to adjust quotes. Key metrics include:
- Fire station distance: Homes within 5 miles of a fire station may see a 10–20% reduction in wildfire-related premiums.
- Flood zone classification: Properties in Zone X (undetermined risk) or Zone A (high risk) face 30–100% higher flood insurance costs.
- Windstorm exposure: Coastal modular homes within 1,500 feet of shorelines often require separate windstorm endorsements.
- Manufacturer Warranty Terms and Compliance Certifications
Warranties act as a risk transfer mechanism between the manufacturer and insurer. Longer warranties (e.g., 10–25 years for structural components) signal higher quality control, potentially lowering premiums by 5–15%. Critical warranty clauses include:
- Defect coverage duration: Warranties under 5 years may trigger higher inspections or exclusions for pre-existing conditions.
- Transportation and assembly guarantees: Insurers may exclude coverage for assembly errors if the warranty lacks explicit transport-related protections.
- Third-party certifications: Homes certified by HUD (U.S.), CSA (Canada), or EN 1990 (Europe) for seismic/wind resistance often qualify for underwriting discounts.
- Construction Materials and Framing Type
The choice between steel, wood, or hybrid framing materials alters fire resistance, rot susceptibility, and structural integrity. Insurers categorize materials as follows:
- Steel framing: Highest fire resistance; 20–30% lower premiums in wildfire-prone areas but may cost more upfront.
- Engineered wood (e.g., LVL beams): Moderate risk; common in modular builds due to cost efficiency.
- Traditional wood framing: Higher risk of termite damage, fire, and moisture-related claims; often requires additional endorsements.
Case Study: A 2,000 sq. ft. modular home in Texas with steel framing and impact-resistant roofing received a 25% discount on windstorm coverage, while an identical wood-framed home in the same area saw a 15% premium increase.- Home Age and Depreciation Factors
Age correlates with wear-and-tear risk, technological obsolescence, and claims frequency. Insurers apply age-based depreciation schedules to modular homes, often more aggressively than site-built homes due to perceived faster deterioration of certain components (e.g., roofing, HVAC systems). Key thresholds:
- 0–10 years: Minimal depreciation; full replacement cost coverage (RCV) available.
- 10–20 years: Partial depreciation (typically 10–20%); may require actual cash value (ACV) endorsements.
- Over 20 years: Significant depreciation (30–50%); insurers may exclude coverage for outdated systems (e.g., electrical panels).
- Custom Modifications and Non-Standard Features
Post-assembly modifications—such as solar panel installations, non-standard roof pitches, or basement additions—introduce variability that insurers treat as elevated risk. Common modifications and their impact:
- Renewable energy systems: Solar panels may reduce utility-related claims but require specialized endorsements (e.g., equipment breakdown coverage).
- Non-standard layouts: Open-concept designs with high ceilings or large windows increase liability risks (e.g., falling debris).
- Luxury finishes: High-end materials (e.g., marble countertops) may void standard coverage for theft or water damage unless explicitly added.
Step-by-Step Self-Assessment of Modular Home Risk Profile
Accurate self-assessment minimizes surprises during underwriting and ensures quotes reflect the home’s true risk profile. Below is a structured checklist to evaluate structural integrity, site hazards, and modifications before requesting quotes. This process should be documented with photographs, manufacturer specifications, and local hazard reports.
Critical Note: Insurers may request proof of compliance for items such as seismic retrofits or flood barriers. Retaining original build documents, warranty certificates, and hazard zone maps is essential.
- Structural Integrity Checklist
Verify compliance with local building codes and manufacturer guidelines for resilience against natural forces. Key areas:
- Foundation documentation: Confirm foundation type (slab, pier, skid) and depth (e.g., pilings must extend below frost line).
- Seismic/wind compliance: Check for engineered ties between modules, hurricane straps, or shear walls if required by local codes.
- Roofing materials: Asphalt shingles (Class 3/4 impact resistance) vs. metal roofing (Class 4) can affect windstorm premiums by 10–25%.
- Wall materials: Insulated concrete forms (ICFs) or steel studs reduce fire/wind risk compared to wood.
Example: A modular home in Florida with a Class 4 impact-resistant roof and hurricane straps may qualify for a 10% discount on windstorm insurance, while a home with standard shingles could face a 5% surcharge.- Site-Specific Hazard Assessment
Leverage FEMA flood maps, USGS wildfire risk tools, or local government hazard reports to evaluate exposure. Critical steps:
- Flood risk: Determine Zone A/B/C/X classification and elevation above base flood elevation (ABFE). Homes in Zone X (undetermined) may require mandatory flood insurance.
- Wildfire threat: Use Wildland-Urban Interface (WUI) maps to assess defensible space compliance (e.g., 30-foot clearance from vegetation).
- Earthquake risk: Check
Methods to Obtain and Compare Modular Home Insurance Quotes
Obtaining and comparing modular home insurance quotes requires a systematic approach to ensure comprehensive coverage while optimizing cost-efficiency. Modular homes, due to their construction methods and certifications, may qualify for unique discounts or exclusions that standard homes do not. Below are structured methods to gather, evaluate, and negotiate quotes effectively, including tools for automation and strategies to leverage certifications.
Side-by-Side Quote Comparison Template
A standardized template simplifies the evaluation of quotes from multiple providers by aligning critical coverage details. The following table organizes key fields for three providers, ensuring consistency in assessment.Purpose: This template standardizes the comparison of dwelling coverage, liability limits, deductibles, and optional endorsements, reducing oversight of critical exclusions or discounts.
Key Fields Explained:
Provider Policy Number & Effective Date Dwelling Coverage Limit Personal Property Limit Liability Coverage Limit Deductible Tiers (Standard/Optional) Optional Endorsements Included Discounts Applied Annual Premium Provider A POL-XXXX-1234 | 06/01/2024 $350,000 $150,000 $500,000 $1,000 (standard), $2,500 (optional) Equipment Breakdown, Identity Theft Bundling (20%), Claims-Free (15%) $1,250 Provider B POL-YYYY-5678 | 06/01/2024 $320,000 $120,000 $300,000 $1,500 (standard), $5,000 (optional) Identity Theft (only) New Homeowner (10%) $1,100 Provider C POL-ZZZZ-9012 | 06/01/2024 $375,000 $180,000 $1,000,000 $2,000 (standard), $3,000 (optional) None Modular Home Certification (12%) $1,350
- Policy Number & Effective Date: Ensures alignment with the coverage period.
- Coverage Limits: Dwelling coverage should reflect replacement cost, not market value. Personal property limits often default to 50–70% of dwelling coverage.
- Deductible Tiers: Higher deductibles lower premiums but increase out-of-pocket risk. Optional tiers may include separate deductibles for specific perils (e.g., windstorms).
- Optional Endorsements: Equipment breakdown coverage is critical for modular homes with integrated systems (e.g., HVAC, plumbing). Identity theft protection may be bundled with monitoring services.
- Discounts Applied: Certifications (e.g., HUD, ANSI) and claims history significantly impact premiums. Bundling with auto or umbrella policies can reduce costs by 10–30%.
Automating Quote Comparisons with Free Tools
Free comparison tools streamline the evaluation process by aggregating quotes, highlighting discrepancies, and flagging potential red flags. These tools typically offer the following features:Core Features:
- Batch Upload: Import quotes in standard formats (CSV, PDF) to populate the template automatically.
- Exclusion Scanner: Cross-references policy language against a database of common exclusions (e.g., manufacturer defects, relocation costs).
- Discount Analyzer: Identifies missed discounts by comparing applied credits against industry benchmarks.
- Certification Validator: Verifies whether insurers recognize modular home certifications (e.g., HUD Code, ANSI A252) and applies them to discount calculations.
Red Flags to Automate Detection:
- Manufacturer Defect Exclusions: Policies may exclude coverage for defects arising from factory errors unless the home is certified by a recognized body (e.g., HUD). Action: Require insurers to specify recourse for claims tied to uncertified components.
"Exclusions for manufacturer defects without clear recourse violate standard industry practices. Insurers should outline steps for claim submission, including third-party inspections."
Implementation Steps:
1. Export quotes as PDFs or CSV files from provider portals.
2. Upload files into the comparison tool, which parses text for keywords (e.g., "exclusion," "deductible," "certification").
3. Generate a report with color-coded alerts for discrepancies (e.g., red for exclusions, yellow for potential discounts).
4. Export the report to the template for manual review.
Leveraging Modular Home Certifications for Lower Quotes
Certifications from recognized bodies reduce perceived risk for insurers, often translating to lower premiums. The most influential certifications include:Prioritized Certifications and Their Impact:
Strategies to Present Certifications:
1. Bundle Certifications: Combine HUD and ANSI certifications in the quote request to signal comprehensive compliance.
2. Highlight Regional Relevance: Emphasize certifications tied to local hazards (e.g., ANSI for wind-prone areas, HUD for flood zones).
3. Provide Documentation Upfront: Attach certification letters or inspection reports with the initial quote request to expedite discount application.
4. Negotiate Based on Age: Older modular homes (pre-2000) may face higher premiums. Solution: Present recent renovations or retrofits that align with current standards.
Example Script for Certification Negotiation:
> "Our modular home is HUD Code-certified (Certificate #12345, issued 2023) and meets ANSI A252.0 standards for structural integrity. Given our region’s susceptibility to [specific peril, e.g., hail/wind], we’d like to confirm whether your underwriting guidelines allow for the full 15% certification discount applied to comparable properties in [state/county]. Additionally, we’ve included documentation of our [specific certification] to support this adjustment."
Script Template for Emailing Insurers to Request Quotes
A well-structured email ensures insurers provide accurate, comparable quotes by specifying modular home details and probing for hidden discounts. Below is a template with mandatory fields and tactical questions.Subject Line: *
Obtaining and comparing modular home insurance quotes transcends mere number-crunching; it requires strategic disclosure of risk factors, rigorous scrutiny of policy fine print, and the ability to negotiate based on certifications like HUD or ANSI compliance. By prioritizing high-impact variables—such as foundation type and site hazards—homeowners can streamline quote requests and avoid red flags, including vague exclusions for manufacturer defects or relocation costs. The ultimate goal is not just securing coverage but achieving a policy tailored to modular homes’ distinct vulnerabilities, ensuring financial protection aligns with structural realities. Armed with comparison templates, automated tools, and negotiation scripts, readers can transform the quote-obtaining process into a data-driven advantage, safeguarding both their investment and peace of mind.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.