Massachusetts Small Business Insurance Key Insights And Strategies
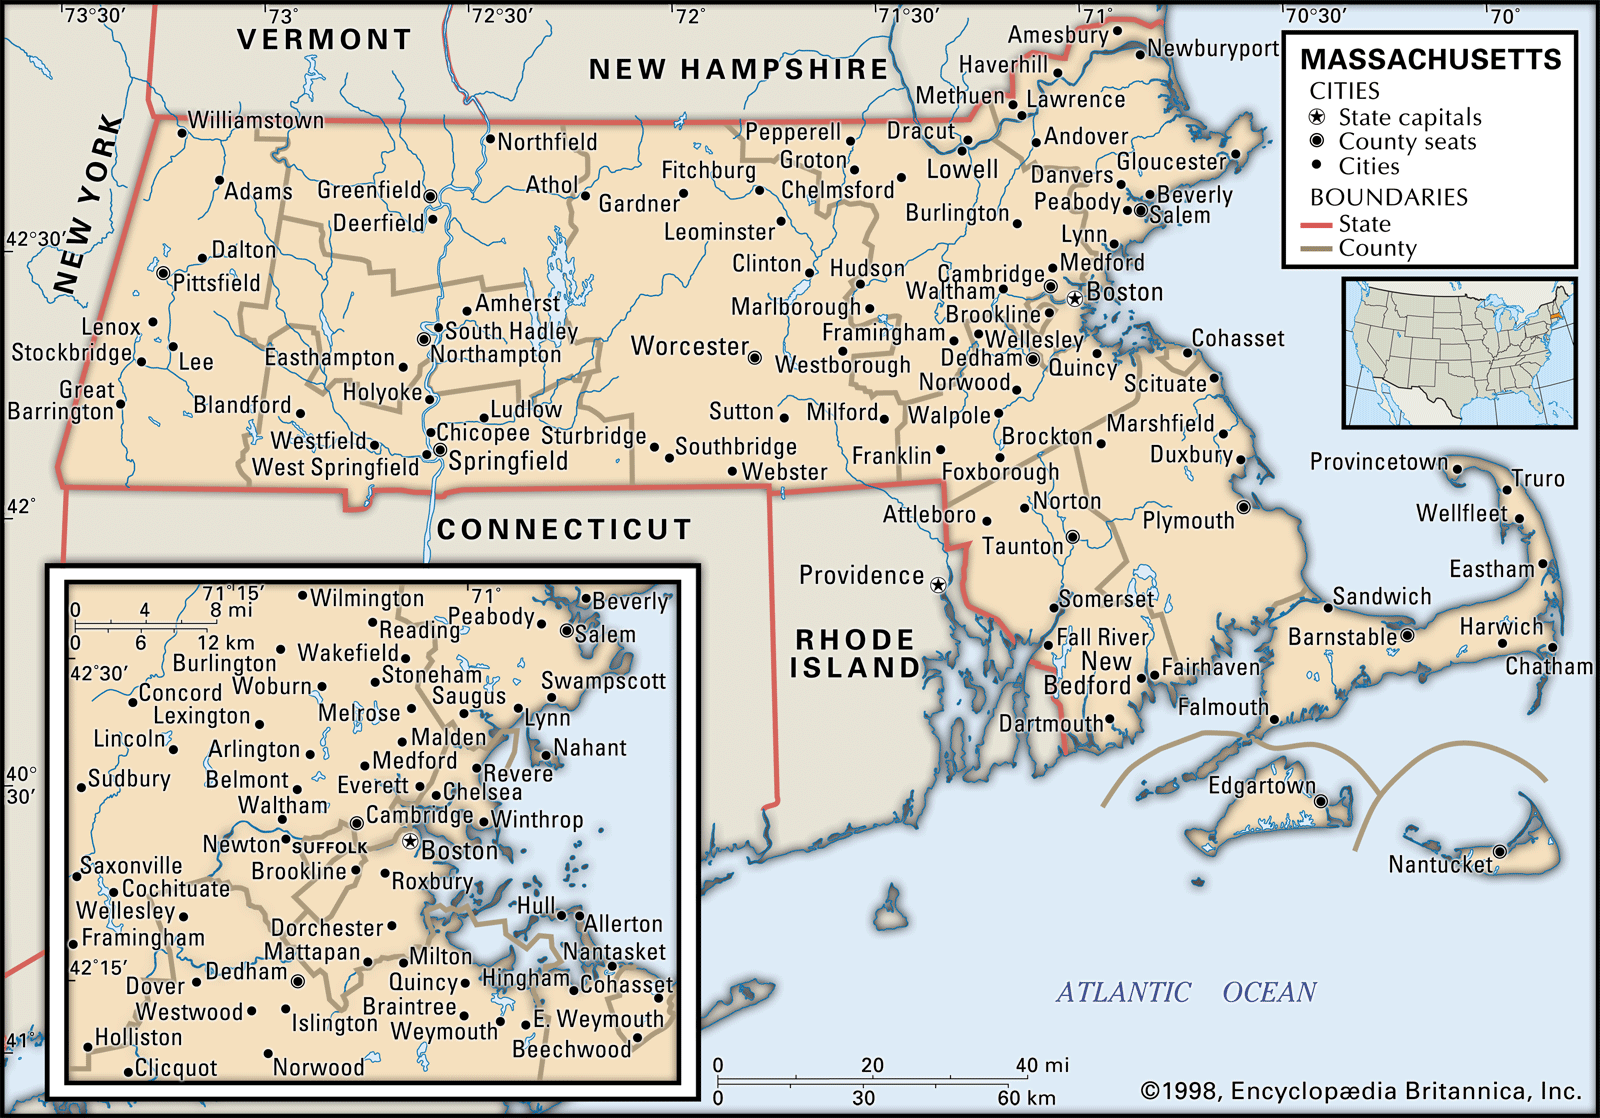
Table of Contents
- Overview of Small Business Insurance in Massachusetts
- Legal and Regulatory Requirements for Small Business Insurance
- Prevalence of Uninsured Small Businesses in Massachusetts
- Comparison of Massachusetts Insurance Mandates vs. National Averages
- Role of the Massachusetts Division of Insurance in Compliance and Consumer Protection
- Types of Insurance Policies for Massachusetts Small Businesses
- Five Essential Insurance Policies for Massachusetts Small Businesses
- Coverage Limits, Costs, and Exclusions for Key Policies
- Bundling Policies vs. Standalone Coverage
- Industry-Specific Risks and Tailored Insurance Solutions
- Cost Factors and Financial Planning for Small Business Insurance in Massachusetts
- Top Five Variables Influencing Insurance Premiums for Massachusetts Small Businesses
- Step-by-Step Procedure for Calculating Projected Annual Insurance Costs
- Legal and Liability Considerations for Compliance in Massachusetts Small Business Insurance
- Premises Liability and Employment-Related Claims Under Massachusetts Law
- Commercial General Liability (CGL) vs. Professional Liability Insurance in Massachusetts
- Checklist of Legal Documents for Massachusetts Small Business Compliance
- Massachusetts Workers’ Compensation Laws vs. Federal OSHA Standards
- Claims Process and Risk Mitigation Strategies for Massachusetts Small Business Insurance
- Step-by-Step Claims Process for Small Businesses in Massachusetts
- Negotiation Tactics for Successful Insurance Claims in Massachusetts
- Infographic: Most Frequent Insurance Claims by Massachusetts Small Businesses (Categorized by Industry)
- Emerging Trends and Future-Proofing Insurance for Massachusetts Small Businesses
- Three Emerging Trends in Massachusetts Small Business Insurance
- Adapting Insurance Strategies to Evolving Risks
- Insurance Marketplaces vs. Private Insurers: Pros and Cons for Massachusetts Small Businesses
- Technology’s Role in Shaping Future Insurance Solutions
- FAQ
- massachusetts small business insurance requirements?
- massachusetts small business health insurance requirements?
- massachusetts small business health insurance?
- massachusetts small business association health insurance?
- best small business insurance massachusetts?
- small business insurance requirements?
Navigating the complexities of insurance requirements is a critical yet often overlooked aspect of sustaining a small business in Massachusetts. With state-specific regulations, industry-specific risks, and evolving legal landscapes, entrepreneurs must balance compliance with cost-efficiency to safeguard their operations. This guide dissects the essential policies, financial planning strategies, and emerging trends shaping small business insurance in Massachusetts, ensuring owners can make informed decisions that mitigate risks while optimizing coverage.
The Commonwealth’s insurance framework demands precision—whether addressing mandatory workers’ compensation mandates, tailoring liability protections for unique industries, or leveraging technology to preempt future disruptions. By examining real-world case studies, regulatory nuances, and actionable cost-reduction tactics, this resource equips business owners with the tools to transform insurance from a compliance burden into a strategic asset. From seasonal cost fluctuations to cybersecurity threats, the insights provided here align with Massachusetts’ dynamic economic and legal environment, offering clarity for both newcomers and seasoned operators.
Overview of Small Business Insurance in Massachusetts
Massachusetts small businesses operate within a regulatory framework that mandates specific insurance coverages to mitigate financial risks associated with liability, property damage, and workforce-related incidents. Compliance with state and federal insurance requirements ensures legal protection while fostering operational resilience. Below is a structured analysis of the legal landscape, industry trends, and comparative mandates, alongside the oversight role of the Massachusetts Division of Insurance.
Legal and Regulatory Requirements for Small Business Insurance
Massachusetts enforces insurance mandates through state statutes and federal regulations, particularly under the Massachusetts Workers’ Compensation Act and Commercial Insurance Code. Key requirements include:
- Workers’ Compensation Insurance: Mandatory for businesses with one or more employees, including part-time workers. Sole proprietors without employees are exempt but may opt for coverage voluntarily. Penalties for non-compliance include fines and potential legal action.
Prevalence of Uninsured Small Businesses in Massachusetts
Despite regulatory obligations, a significant portion of Massachusetts small businesses operate without adequate coverage. Key statistics from Massachusetts Small Business Development Center (SBDC) reports (2022–2023) and Insurance Information Institute (III) data highlight industry-specific trends:- Overall Uninsured Rate: Approximately 15–20% of small businesses in Massachusetts lack workers’ compensation insurance, with higher rates in low-margin sectors (e.g., restaurants, personal services).
Comparison of Massachusetts Insurance Mandates vs. National Averages
Massachusetts imposes stricter insurance requirements than the national average, particularly for workers’ compensation and commercial auto policies. The following table contrasts state-specific mandates with U.S. benchmarks:| Requirement | Massachusetts Mandate | National Average (U.S.) | Key Differences |
|---|---|---|---|
| Workers’ Compensation Coverage | Mandatory for all businesses with ≥1 employee; no employee count exemption. | Mandatory in 49 states; Texas exempts employers with <3 employees. | Massachusetts has no minimum employee threshold, unlike 20+ states. |
| Commercial Auto Insurance | Required for all business-owned vehicles; personal policies invalid for commercial use. | Required in 48 states; 2 states (New Hampshire, Virginia) have no mandate. | Massachusetts enforces stricter vehicle classification rules (e.g., delivery vans vs. passenger cars). |
| General Liability Limits | No state-mandated minimum; recommended limits: $1M per occurrence. | No federal mandate; national average recommended: $500K–$1M. | Massachusetts courts often award higher damages in liability cases (e.g., medical malpractice). |
| Professional Liability Insurance | Not legally required but mandated by contracts (e.g., government, healthcare providers). | Not federally mandated; 15 states require it for licensed professionals (e.g., architects). | Massachusetts contracts frequently specify $2M+ limits for high-risk industries. |
| Cyber Liability Insurance | Not legally required but encouraged for businesses handling customer data. | No federal mandate; 12 states recommend it for data breaches. | Massachusetts enforces 239C Data Security Regulations, increasing exposure risks. |
Role of the Massachusetts Division of Insurance in Compliance and Consumer Protection
The Massachusetts Division of Insurance (DOI) oversees small business insurance compliance through regulatory oversight, enforcement, and consumer education. Key functions include:- Licensing and Market Conduct: The DOI licenses insurers operating in Massachusetts and monitors unfair trade practices, such as misrepresentation or policy cancellations without notice.
The Massachusetts Division of Insurance emphasizes that "compliance is not optional—it is a legal and financial safeguard." Businesses failing to meet mandates risk operational shutdowns, lawsuits, and reputational damage, particularly in industries with high litigation rates (e.g., healthcare, construction).

Types of Insurance Policies for Massachusetts Small Businesses
Small businesses in Massachusetts operate within a regulatory and risk landscape that demands strategic insurance planning. Selecting the right policies mitigates financial exposure to liabilities, property damage, employee injuries, and industry-specific risks. Below are the five most essential insurance policies for Massachusetts-based businesses, supported by tailored coverage frameworks, cost considerations, and industry-specific recommendations.Five Essential Insurance Policies for Massachusetts Small Businesses
Massachusetts small businesses must prioritize policies that align with state laws, industry risks, and operational scale. The following five policies form a foundational risk management strategy:-
General Liability Insurance
Protects against third-party claims for bodily injury, property damage, or advertising injuries (e.g., slander/libel). Mandatory for businesses with physical premises or public interactions, including retail, restaurants, and professional services. -
Professional Liability Insurance (Errors and Omissions - E&O)
Shields businesses from claims of negligence, errors, or omissions in professional services (e.g., consulting, legal, or healthcare). Critical for service-based industries where advice or expertise is central to operations. -
Workers’ Compensation Insurance
Required by Massachusetts law for businesses with one or more employees. Covers medical expenses and lost wages for work-related injuries or illnesses, while protecting employers from lawsuits. -
Commercial Property Insurance
Safeguards physical assets (buildings, equipment, inventory) against risks like fire, theft, or natural disasters. Essential for businesses with tangible assets, including manufacturers, retailers, and office-based operations. -
Cyber Liability Insurance
Addresses financial losses from data breaches, ransomware, or cyberattacks. Increasingly vital for tech firms, healthcare providers, and businesses handling customer data, given Massachusetts’ strict data privacy laws (e.g., 201 CMR 17.00).
Coverage Limits, Costs, and Exclusions for Key Policies
The following table outlines typical coverage parameters for three core policies in Massachusetts, based on industry benchmarks and state-specific regulations. Costs vary by business size, location, and risk profile.| Policy Type | Coverage Limits (Annual) | Average Cost (Annual) | Key Exclusions |
|---|---|---|---|
| General Liability Insurance |
|
$500–$3,000 (varies by industry) |
|
| Professional Liability (E&O) |
|
$1,000–$10,000 (tech/consulting: higher end) |
|
| Workers’ Compensation Insurance |
|
$500–$5,000+ (based on payroll and industry classification) |
|
Bundling Policies vs. Standalone Coverage
Massachusetts small businesses often face the decision between purchasing individual policies or bundling them into a Business Owner’s Policy (BOP). Each approach offers distinct advantages:Business Owner’s Policy (BOP) Benefits:Standalone Policies:Limitations:
- Cost Efficiency: Bundles general liability, property, and business interruption coverage at a 10–20% discount compared to standalone policies.
- Simplified Management: Single premium, policy renewal, and claims process.
- Comprehensive Risk Transfer: Covers interconnected perils (e.g., property damage leading to business interruption).
- Industry Restrictions: BOPs are unavailable for high-risk sectors (e.g., construction, manufacturing) or businesses with unique liabilities.
- Limited Customization: May exclude specialized coverages (e.g., cyber liability, professional liability).
Recommendation: Businesses with standard risks (e.g., retail, professional services) should evaluate BOPs for cost savings. High-risk or specialized industries should consult insurers to combine essential policies (e.g., general liability + workers’ comp) while adding standalone policies for gaps.
Industry-Specific Risks and Tailored Insurance Solutions
Massachusetts’ diverse economy exposes businesses to unique vulnerabilities. Below are industry-specific risks and recommended insurance solutions:-
Healthcare Providers (Hospitals, Clinics, Home Care)
- Key Risks: Medical malpractice, HIPAA violations, equipment theft, and cyberattacks on patient data.
- Recommended Policies:
- Medical Malpractice Insurance: Covers claims of negligence (e.g., surgical errors, misdiagnosis).
- Cyber Liability Insurance: Addresses ransomware, data breaches, and regulatory fines (e.g., Massachusetts Health Information Privacy Law).
- Employment Practices Liability Insurance (EPLI): Protects against wrongful termination or discrimination lawsuits.
-
Technology and Software Companies
- Key Risks: Intellectual property theft, software bugs causing client losses, and cyber extortion.
- Recommended Policies:
- Errors and Omissions (E&O): Covers failures in software delivery or service agreements.
- Cyber Insurance: Includes first-party costs (e.g., ransom payments) and third-party liabilities (e.g., client lawsuits).
- Intellectual Property Insurance: Protects against infringement claims or theft of proprietary code.
-
Hospitality (Hotels, Restaurants, Event Venues)
-
Cost Factors and Financial Planning for Small Business Insurance in Massachusetts
Understanding the financial implications of insurance is critical for small business owners in Massachusetts, where regulatory requirements, regional risks, and industry-specific exposures create unique cost dynamics. Premiums are not arbitrary; they reflect quantifiable variables tied to risk assessment, operational scale, and external economic conditions. This section examines the primary drivers of insurance costs, provides a structured methodology for projecting annual expenses, and outlines actionable strategies to optimize premiums while accounting for seasonal and environmental fluctuations that disproportionately impact Massachusetts businesses.
Top Five Variables Influencing Insurance Premiums for Massachusetts Small Businesses
Insurance premiums for small businesses in Massachusetts are determined by a combination of intrinsic and extrinsic factors, with some variables carrying significantly more weight than others. The following elements, ranked by their typical impact on premiums, serve as the foundation for underwriting decisions and financial planning.
-
Business Location and Property Risk
The geographic footprint of a business—particularly its proximity to high-risk zones such as floodplains, urban crime hotspots, or areas prone to winter storms—directly correlates with property and liability costs. For example, businesses in coastal regions (e.g., Cape Cod, Boston’s waterfront) face elevated flood and windstorm exposure, while urban areas (e.g., Somerville, Worcester) may incur higher theft or vandalism premiums. Massachusetts’ municipal classifications (e.g., fire protection class ratings) further refine risk assessments, with businesses in Class 10 municipalities (highest risk) paying up to 30% more for property insurance than those in Class 1 (lowest risk).Premium Adjustment Formula (Simplified): Base Premium × (Location Risk Factor × 1.0 – 2.5) × (Fire Protection Class Multiplier)
-
Industry Classification and Occupational Hazards
The nature of operations dictates the type and severity of risks insurers must mitigate. High-risk industries such as construction, manufacturing, or food service incur higher premiums due to elevated claims potential. For instance:- Construction businesses in Massachusetts face general liability premiums 40–60% higher than retail due to equipment damage, worker injuries, and third-party property risks.
- Restaurants with commercial kitchens pay 2–3 times more for property insurance than office-based businesses because of fire hazards (e.g., grease fires, electrical faults).
- Professional services (e.g., law firms, accountants) typically pay 15–25% lower premiums for general liability but may require errors and omissions (E&O) insurance, adding $1,500–$10,000 annually depending on revenue.
-
Revenue and Payroll Size
Insurance premiums scale with business size, as larger operations generate higher exposure to claims. Underwriters use gross annual revenue and payroll as primary metrics:- General Liability Insurance: Typically $500–$3,000 annually for businesses under $500K revenue; $3,000–$10,000+ for revenues exceeding $1M, with commercial auto and workers’ comp adding $2,000–$15,000 for payrolls over $500K.
- Cyber Liability Insurance: Costs rise exponentially with employee count; a 10-employee firm may pay $1,200–$2,500/year, while a 50-employee firm could exceed $10,000.
- Massachusetts-specific: Businesses with 50+ employees must comply with M.G.L. c. 151B, which may increase workers’ comp premiums by 10–20% due to stricter reporting requirements.
Payroll-Based Premium Estimate (Workers’ Comp): Annual Premium = Payroll × Classification Rate × Experience Modifier
(Example: A $1M payroll in retail (Class Code 8810, rate: $0.0025) with a 0.9 EM = $2,250/year.) -
Claims History and Risk Management Practices
A business’s loss history is the most direct predictor of future premiums. Insurers in Massachusetts analyze:- Past 3–5 years of claims: Frequent or high-severity claims (e.g., $50K+ property damage) can increase premiums by 25–50% or trigger policy non-renewal.
- Experience Modifier (EM): A score below 1.0 (indicating better-than-average safety) reduces costs; above 1.0, premiums rise. For example, a 1.2 EM adds 20% to workers’ comp premiums.
- Safety Certifications: Businesses with OSHA compliance or ISO 31000 risk management may qualify for 5–15% discounts on general liability.
-
Seasonal and Environmental Exposure
Massachusetts’ climate introduces cyclical cost fluctuations, particularly for businesses in tourism, retail, and outdoor sectors. Key seasonal factors include:- Winter Storms and Snow Insurance: Property policies in Northern MA (e.g., North Adams, Pittsfield) may include winter storm deductibles (e.g., 2% of policy limit) or separate wind/hail coverage, adding $300–$1,500 annually. Businesses in Boston or coastal areas face higher flood insurance costs (NFIP premiums average $700–$2,000/year).
- Tourism Peaks (Summer/Fall): Retail and hospitality businesses in Cape Cod, Martha’s Vineyard, or the Berkshires see 30–50% higher liability premiums during peak seasons due to increased foot traffic and alcohol-related incidents.
- Agricultural and Outdoor Risks: Greenhouses, farms, and outdoor event venues in Western MA require crop insurance (average $1,000–$5,000/year) or special event liability coverage, which spikes 20–40% during festival seasons.
Step-by-Step Procedure for Calculating Projected Annual Insurance Costs
Accurate cost projection requires a systematic approach that integrates revenue, location, industry benchmarks, and Massachusetts-specific regulations. Below is a five-phase methodology to estimate annual insurance expenditures with ±10% accuracy.
-
Gather Business and Operational Data
Compile the following metrics from financial records and operational assessments:Data Point Source Example Value (MA Small Business) Annual Revenue Profit & Loss Statement $450,000 Payroll (Annual) Payroll Reports $320,000 Number of Employees HR Records 12 Business Location (City/Town) Lease Agreement Somerville (Fire Protection Class 5) Industry NAICS Code Business License 722511 (Full-
Legal and Liability Considerations for Compliance in Massachusetts Small Business Insurance
Massachusetts small businesses operate within a complex regulatory framework that mandates compliance with state-specific liability laws, insurance requirements, and employment protections. Failure to adhere to these obligations exposes businesses to financial penalties, lawsuits, and operational disruptions. This section examines the key legal and liability risks unique to Massachusetts, distinguishes between critical insurance policies, and provides structured compliance tools to mitigate exposure.
Premises Liability and Employment-Related Claims Under Massachusetts Law
Massachusetts imposes strict liability on business owners for injuries or damages occurring on their premises, governed by Massachusetts General Laws (MGL) Chapter 231 and Chapter 149. Premises liability claims commonly arise from:
- Slip-and-fall accidents due to wet floors, uneven surfaces, or inadequate lighting.
- Inadequate security measures leading to theft, assault, or property damage.
- Failure to warn customers or employees of known hazards (e.g., construction zones, icy walkways).
Employment-related claims under Massachusetts law include:
- Workers’ compensation disputes (covered under MGL Chapter 152), where employees may sue for unpaid benefits or retaliation.
- Wage and hour violations (e.g., unpaid overtime under MGL Chapter 149, Section 148), which can trigger collective lawsuits.
- Discrimination or harassment claims under Title VII of the Civil Rights Act and MGL Chapter 151B, often leading to settlements exceeding $50,000 per case.
Key Statute Highlights:
- MGL Chapter 231, Section 85K: Requires businesses to maintain commercial general liability (CGL) insurance with minimum limits of $1 million per occurrence for premises-related claims.
- MGL Chapter 149, Section 105A: Mandates workers’ compensation insurance for businesses with one or more employees, including part-time workers.
- Massachusetts Consumer Protection Act (MGL Chapter 93A): Holds businesses liable for deceptive practices, including misrepresented insurance coverage or failure to disclose material risks.
Commercial General Liability (CGL) vs. Professional Liability Insurance in Massachusetts
Massachusetts businesses must differentiate between CGL and professional liability insurance based on the nature of their operations. Both policies address third-party claims but serve distinct purposes.Commercial General Liability (CGL) Coverage
CGL policies protect against bodily injury, property damage, and personal/advertising injury arising from business operations. Common claims include:
- A customer slipping on a wet floor in a retail store.
- A contractor accidentally damaging a client’s property during a renovation.
- Defamation from a false advertising campaign.
Exclusions in Massachusetts CGL Policies:
- Professional errors or omissions (e.g., an accountant providing incorrect tax advice).
- Intentional acts (e.g., fraud or criminal negligence).
- Pollution-related damages (unless endorsed separately).
Professional Liability Insurance (Errors and Omissions - E&O)
Required for service-based businesses (e.g., consultants, lawyers, architects), this policy covers negligent acts, errors, or omissions in professional services. Examples include:
- A Massachusetts-licensed architect whose design flaws cause structural damage.
- A financial advisor whose investment recommendations lead to client losses.
- A marketing agency accused of trademark infringement in a campaign.
Key Differences:
When to Purchase Both:Feature Commercial General Liability (CGL) Professional Liability (E&O) Primary Coverage Bodily injury, property damage, advertising injury Errors, omissions, negligent services Industries Required Retail, manufacturing, construction Healthcare, legal, financial, consulting Claim Examples Slip-and-fall, product defects Misdiagnosis (medical), breach of contract (legal) Massachusetts Statute MGL Ch. 231, §85K (insurance requirement) No state mandate; industry-specific needs
Businesses offering both physical services and professional advice (e.g., a construction firm providing design consultations) should carry both CGL and E&O policies to avoid coverage gaps.
Checklist of Legal Documents for Massachusetts Small Business Compliance
Maintaining accurate and up-to-date legal documents is essential for compliance with Massachusetts insurance regulations and liability mitigation. Below is a structured checklist categorized by business function.1. Insurance and Risk Management Documents
- Certificates of Insurance (COIs): Issued by insurers (e.g., CGL, workers’ comp, cyber liability) to verify coverage limits and policy details.
- Endorsements/Riders: Additional coverage modifications (e.g., umbrella liability policies under MGL Ch. 175, §105C).
- Loss Runs: Historical claim data provided by insurers to assess risk profiles.
2. Employment and Workplace Safety Records
- Workers’ Compensation Insurance Policy: Proof of compliance with MGL Ch. 152, including Division of Insurance (DOI) filings.
- OSHA 300 Logs: Required for businesses with 11+ employees under federal OSHA, documenting workplace injuries.
- Massachusetts Safety Committee Records: Mandatory for construction and manufacturing firms under MGL Ch. 149, §100B.
- Employee Handbooks: Must include anti-discrimination policies, whistleblower protections, and workers’ comp claim procedures.
3. Contractual and Liability Waivers
- Service Agreements: Include limitation of liability clauses compliant with MGL Ch. 93A (avoiding unfair contract terms).
- Liability Waivers: Signed by clients for high-risk activities (e.g., gyms, adventure tours) with Massachusetts-specific disclaimers.
- Independent Contractor Agreements: Specify workers’ comp exclusions for 1099 employees under IRS and Massachusetts DOR rules.
4. Premises and Public Safety Compliance
- Building Permits and Inspection Reports: Required for commercial properties under Massachusetts State Building Code (780 CMR).
- ADA Compliance Certificates: For businesses serving the public, ensuring accessibility under Title III of the ADA.
- Security System Logs: Mandatory for retail and hospitality businesses in high-theft areas (e.g., Boston’s Commercial District Safety Ordinance).
5. Consumer Protection and Advertising Records
- Massachusetts Consumer Protection Act (MGL Ch. 93A) Compliance Files: Documentation of disclosure statements for insurance products or service agreements.
- Endorsement Logs for Advertising: Proof of truth-in-advertising compliance under FTC and Massachusetts Attorney General guidelines.
Storage and Retention Requirements:
- Insurance documents: Retain for 6 years post-policy expiration.
- Employment records: Keep 4 years after termination (per Massachusetts Department of Labor Standards).
- Safety logs and permits: Maintain indefinitely for OSHA and state audits.
Massachusetts Workers’ Compensation Laws vs. Federal OSHA Standards
Massachusetts enforces dual compliance for workplace safety, requiring businesses to adhere to state-specific workers’ compensation laws and federal Occupational Safety and Health Administration (OSHA) regulations. Below is a comparative analysis and step-by-step compliance guide.Key Differences Between Massachusetts Workers’ Comp and Federal OSHA
Aspect Massachusetts Workers’ Compensation (MGL Ch. 152) Federal OSHA (29 CFR 1910) Coverage Scope Mandatory for all employers with 1+ employees (including part-time). Applies to businesses with 11+ employees (varies by state plan). Claim Process No-fault system: Employees file claims with the Department of Industrial Accidents (DIA). Right-to-sue: Employees can sue under state workers’ comp or OSHA retaliation claims. Medical Benefits No cost to employee: Employer pays for all medical treatment approved by DIA. Employer-controlled: Medical costs may be disputed under OSHA’s medical leave rules. Penalties for Non-Compliance $1,000–$10,000 per violation (MGL Ch. 152, §35). $13,653 Claims Process and Risk Mitigation Strategies for Massachusetts Small Business Insurance
Understanding the claims process and implementing proactive risk mitigation strategies are critical components of managing small business insurance in Massachusetts. The state’s regulatory framework, combined with industry-specific risks, requires businesses to navigate claims efficiently while minimizing financial exposure. Below is a structured breakdown of the claims process, negotiation tactics, common claim categories, risk assessment methodologies, and communication templates for disputes.
Step-by-Step Claims Process for Small Businesses in Massachusetts
The claims process in Massachusetts follows a standardized sequence, with strict adherence to deadlines and documentation requirements. Small business owners must initiate claims promptly to avoid delays in coverage or disputes with insurers.Key Steps in Filing a Claim:
- Immediate Notification: Report the incident to the insurance provider within the policy’s specified timeframe (typically 30–60 days for property damage, 24–72 hours for theft or liability incidents). Failure to comply may void coverage.
- Documentation Collection: Gather evidence including:
- Police reports (for theft, vandalism, or accidents).
- Photographs/videos of damage or injuries.
- Witness statements and medical records (for liability claims).
- Invoices/receipts for damaged property or lost income.
- Claim Submission: Submit the claim via the insurer’s preferred method (online portal, phone, or mail) with a completed claim form. Include a detailed description of the incident, timeline, and supporting documents.
- Adjuster Assignment: The insurer assigns a claims adjuster to investigate. The adjuster may request additional documentation or conduct an on-site inspection.
- Claim Evaluation: The adjuster assesses the claim based on policy terms, coverage limits, and liability. This phase may include negotiations over settlement amounts.
- Settlement or Dispute: If approved, the insurer issues payment. If disputed, the business may appeal or seek mediation, with deadlines typically ranging from 15–30 days for responses.
Common Pitfalls in the Claims Process:
- Delayed Reporting: Procrastination can lead to denied claims, especially for time-sensitive events like data breaches or natural disasters.
- Incomplete Documentation: Missing critical evidence (e.g., lack of witness statements for slip-and-fall incidents) weakens the claim.
- Miscommunication with Adjusters: Vague descriptions or emotional responses during claims discussions can hinder fair settlements.
- Assuming Coverage: Businesses often overlook exclusions (e.g., flood damage in standard property policies) until after filing.
Massachusetts-Specific Considerations:
- Acts of God: Coverage for events like blizzards or hurricanes may require additional endorsements (e.g., Massachusetts Windstorm Act compliance for coastal properties).
- Workers’ Compensation: Claims must be filed with the Massachusetts Department of Industrial Accidents (DIA) within 3 years of the incident, with insurers typically requiring notification within 24 hours.
Negotiation Tactics for Successful Insurance Claims in Massachusetts
Small businesses in Massachusetts have successfully negotiated higher settlements or expedited claims by leveraging strategic communication and legal knowledge. Below are real-world examples and tactics used in disputes.Real-World Examples of Successful Negotiations:
1. Retail Store – Slip-and-Fall Liability:
- A Cambridge boutique faced a $250,000 claim after a customer slipped on a wet floor. The insurer initially offered $50,000, citing the customer’s failure to use handrails. The business retained a public adjuster to:
- Present security camera footage showing the store’s prior negligence in mopping procedures.
- Highlight Massachusetts’ comparative negligence statute (M.G.L. c. 231, § 85), which allows partial fault allocation.
- Result: Settlement increased to $180,000.
2. Restaurant – Fire Damage:
- A Boston eatery suffered $1.2 million in damages from a kitchen fire. The insurer denied coverage for "negligent grease buildup," citing a policy exclusion. The business:
- Hired a fire investigator to prove the blaze originated from an electrical fault, not grease.
- Cited Massachusetts’ fair claims practices (105 CMR 180.000), requiring insurers to justify denials.
- Result: Full coverage approved for $1.15 million after mediation.
Negotiation Tactics:
- Leverage Policy Language: Highlight specific clauses (e.g., "sudden and accidental" damage) to argue for coverage.
- Document Pre-Loss History: Provide records of prior inspections or maintenance to disprove negligence claims.
- Engage Third-Party Experts: Use public adjusters, engineers, or legal counsel to challenge lowball offers.
- Appeal to State Regulations: Reference Massachusetts’ Division of Insurance (DOI) guidelines, which prohibit unfair claim practices.
- Set Deadlines: Politely insist on written responses to avoid insurer delays under M.G.L. c. 176D, § 3(9) (unfair claims settlement practices).
When to Escalate:
- If the insurer fails to respond within 15–30 days of a reasonable request.
- If the offer is <50% of the claim’s documented value without justification.
- If the insurer cites bad faith (e.g., ignoring clear policy coverage).
Infographic: Most Frequent Insurance Claims by Massachusetts Small Businesses (Categorized by Industry)
The following table summarizes the top 5 claim types filed by small businesses in Massachusetts, based on data from the Massachusetts Division of Insurance (2022–2023) and industry reports. Claims are categorized by industry to illustrate exposure patterns.
Visualization Notes (Descriptive):Industry Top Claim Type Frequency (%) Average Claim Cost Key Risk Factors Retail/Wholesale Slip-and-Fall Liability 42% $75,000 Wet floors, poor lighting, obstructed walkways. Theft/Vandalism 28% $42,000 Unsecured entrances, lack of surveillance. Restaurants/Cafés Fire Damage 55% $310,000 Grease buildup, faulty wiring, kitchen equipment malfunctions. Foodborne Illness Liability 22% $120,000 Improper storage, cross-contamination, staff training gaps. Construction Property Damage (Third-Party) 60% $280,000 Accidental demolition, equipment failure, subcontractor errors. Workers’ Compensation 30% $150,000 Falls from heights, repetitive motion injuries, lack of PPE compliance. Professional Services Cyber Liability 45% $180,000 Data breaches, phishing attacks, inadequate encryption. Errors & Omissions (E&O) 35% $95,000 Contract disputes, misrepresented services, intellectual property infringement. Healthcare (Clinics) Medical Malpractice 70% $450,000 Misdiagnosis, medication errors, lack of informed consent. HIPAA Violations 20% $110,000 Unauthorized data access, improper disposal of records. Manufacturing Equipment Breakdown 50% $220,000 Lack of preventive maintenance, power surges, obsolete machinery. Product Liability 30% $190,000 Defective products, failure to warn of hazards.
- Bar Graph: Frequency percentages stacked by industry, with color-coded segments for each claim type.
- Pie Charts: Breakdown of average claim costs by industry (e.g., construction claims dominate in dollar value).
- Icons: Symbols for high-risk areas (e.g., a flame icon for restaurant fires, a hacker silhouette for cyber claims).
- Callout Boxes: Highlight Massachusetts-specific risks, such as:
- "Winter Hazards" for retail (ice-related slips).
- "Coastal Flood Exclusions" for construction near Boston Harbor.
Data Sources:
- Massachusetts Division of Insurance (DOI) Annual Reports.
- National Federation of Independent Business (NFIB) Massachusetts Small Business Survey (
Emerging Trends and Future-Proofing Insurance for Massachusetts Small Businesses
Massachusetts small businesses face an evolving risk landscape shaped by technological advancements, regulatory shifts, and global disruptions. Proactive adaptation to emerging trends—such as cyber threats, climate vulnerabilities, and supply chain instability—is critical for maintaining resilience. This section examines three key trends influencing small business insurance in Massachusetts, strategies for mitigation, and the role of technology in future-proofing coverage. Additionally, a regulatory projection table outlines potential impacts of upcoming state laws on insurance requirements by 2025.
Three Emerging Trends in Massachusetts Small Business Insurance
The insurance needs of Massachusetts small businesses are increasingly influenced by three dominant trends: cyber liability risks, climate-related exposures, and remote work and hybrid workforce liabilities. Each trend introduces unique challenges that traditional insurance models may not fully address, necessitating tailored solutions.
"By 2025, cyber incidents will account for 60% of all claims in the SME sector, with ransomware attacks rising by 40% annually." — Massachusetts Insurance Division Risk Report (2023)
-
Cyber Liability and Data Privacy Compliance
Massachusetts small businesses, particularly those handling customer data (e.g., healthcare providers, e-commerce, or SaaS firms), are prime targets for cyberattacks. The Massachusetts Data Security Regulations (201 CMR 17.00) impose strict requirements for data protection, and breaches can trigger lawsuits under the Consumer Protection Act (MGL c. 93A). Cyber insurance policies now often include first-party coverage for business interruption, third-party liability for regulatory fines, and crisis management services. -
Climate-Related Risks and Property Damage
Rising sea levels, extreme weather (e.g., Nor’easters, flooding), and infrastructure vulnerabilities pose significant threats to businesses in coastal and urban areas like Boston and Worcester. The Massachusetts Climate Resilience Act (2022) mandates climate risk assessments for state-funded projects, indirectly pressuring insurers to refine underwriting for flood-prone properties. Parametric insurance—which pays out based on predefined triggers (e.g., rainfall thresholds)—is gaining traction as a supplement to traditional property policies. -
Remote Work and Hybrid Workforce Liabilities
The shift to remote work has expanded liability exposures, including workers’ compensation claims for home office injuries, data leaks from unsecured devices, and compliance gaps under the Massachusetts Wage Act (MGL c. 149) for misclassified employees. Insurers now offer remote work endorsements that cover equipment damage, cyber risks from personal devices, and legal defense costs for wage disputes.
Adapting Insurance Strategies to Evolving Risks
Massachusetts small businesses must align their insurance portfolios with emerging risks through proactive risk management, policy customization, and regulatory compliance. Strategies include diversifying coverage, leveraging technology for real-time monitoring, and collaborating with brokers to fill gaps in standard policies.
"A single cyber incident can cost a small business an average of $1.4 million in direct and indirect losses, with 60% of affected businesses closing within six months." — Massachusetts Small Business Development Center (MSBDC) Cybersecurity Survey (2023)
-
Remote Work Policies and Workers’ Compensation
Businesses should:
- Update workers’ compensation policies to include remote work endorsements covering home office injuries (e.g., ergonomic claims).
- Implement cybersecurity protocols for remote devices, such as multi-factor authentication (MFA) and endpoint detection tools.
- Clarify employment classifications under the Massachusetts Independent Contractor Law (MGL c. 149 § 148B) to avoid misclassification penalties.
-
Supply Chain Disruption Coverage
To mitigate risks from global trade delays, supplier bankruptcies, or natural disasters, businesses can:
- Purchase supply chain business interruption insurance, which compensates for lost revenue when key suppliers fail.
- Partner with trade credit insurers to protect against non-payment by international vendors.
- Diversify suppliers across regions to reduce single-point failure risks (e.g., avoiding over-reliance on ports in New York or New Jersey).
-
Climate Resilience Planning
Proactive measures include:
- Flood zone assessments using FEMA’s Flood Insurance Rate Maps (FIRMs) to determine eligibility for National Flood Insurance Program (NFIP) policies.
- Retrofit investments (e.g., reinforced roofs, backup generators) to qualify for preferred insurer discounts.
- Parametric insurance add-ons for rapid payouts after extreme weather events, complementing traditional property coverage.
Insurance Marketplaces vs. Private Insurers: Pros and Cons for Massachusetts Small Businesses
Massachusetts offers state-run insurance programs (e.g., Massachusetts Small Business Insurance Pool) alongside private insurers, each with distinct advantages and limitations. The choice depends on coverage needs, budget, and risk profile.
"State-run pools often fill gaps left by private markets but may impose stricter underwriting or higher premiums for high-risk industries." — Massachusetts Insurance Division (2023)
Criteria State-Run Insurance Marketplaces (e.g., Massachusetts Small Business Pool) Private Insurers (e.g., Travelers, Chubb, local brokers) Coverage Scope - Mandated coverage for high-risk industries (e.g., construction, healthcare) rejected by private markets.
- Standardized policies with limited customization.
- Highly customizable policies (e.g., cyber-specific, niche liability).
- Access to emerging products like parametric insurance.
Cost - Potentially higher premiums due to risk pooling.
- Subsidies or grants may be available for eligible businesses.
- Competitive pricing with discounts for bundling (e.g., BOP + cyber).
- Loyalty programs or loss-prevention incentives.
Claims Process - Standardized but slower due to state oversight.
- Limited 24/7 support for complex claims.
- Faster resolution with dedicated claims adjusters.
- Advanced tools (e.g., AI-driven fraud detection).
Regulatory Compliance - Automatic adherence to state mandates (e.g., workers’ comp).
- No need for broker oversight.
- Broker guidance ensures compliance with local laws (e.g., MGL c. 176D for data privacy).
- Flexibility to adjust coverage as regulations evolve.
Best For Businesses in high-risk sectors or those unable to secure private coverage. Businesses with specialized needs (e.g., tech startups, professional services). Technology’s Role in Shaping Future Insurance Solutions
Artificial intelligence (AI), Internet of Things (IoT) sensors, and blockchain are transforming how Massachusetts small businesses assess, purchase, and manage insurance. These technologies enable real-time risk mitigation, dynamic pricing, and automated claims processing, reducing reliance on manual underwritingSmall business insurance in Massachusetts is not merely a regulatory obligation but a proactive investment in resilience. By prioritizing the five core policies—general liability, professional liability, workers’ compensation, commercial property, and cyber coverage—entrepreneurs can construct a robust defense against financial setbacks. Strategic bundling, risk assessments, and compliance with state-specific mandates further enhance protection, while emerging trends like AI-driven risk tools and climate-adaptive policies signal the future of insurance. As businesses adapt to remote work, supply chain vulnerabilities, and evolving consumer expectations, the insights shared here serve as a roadmap to future-proofing operations. Ultimately, a well-structured insurance strategy ensures continuity, fosters growth, and secures peace of mind in an increasingly unpredictable marketplace.
FAQ
massachusetts small business insurance requirements?
Q: What are the insurance requirements for small businesses in Massachusetts?
massachusetts small business health insurance requirements?
Q: What are the health insurance requirements for small businesses in Massachusetts?
massachusetts small business health insurance?
Q: How does small business health insurance work in Massachusetts?
massachusetts small business association health insurance?
Q: Does the Massachusetts Small Business Association offer health insurance for small businesses?
best small business insurance massachusetts?
Q: What is the best small business insurance in Massachusetts for my industry?
small business insurance requirements?
Q: What are the general small business insurance requirements nationwide?
-
Business Location and Property Risk
-
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.