How To Choose Mortgage X For Smart Financial Decisions
-CnO6d7lLv6o-1080p-1654225304596 2.webp)
Table of Contents
- Mortgage Types and Their Suitability for Borrowers in 'X'
- Primary Mortgage Types and Their Characteristics
- Conventional vs. Government-Backed Loans: Credit Score and Eligibility
- Assessing Financial Readiness for Mortgage 'X'
- Key Financial Metrics for Mortgage 'X' Qualification
- Calculating Affordability Using the 28/36 Rule
- Step-by-Step Guide to Improving Credit Scores in 6–12 Months
- Evaluating Interest Rates, Terms, and Lender Options for Mortgage 'X'
- Market Conditions Influencing Mortgage Rates for 'X'
- Long-Term Cost Comparison: 15-Year vs. 30-Year Mortgages for 'X'
- Top 5 Lender Types for Securing Mortgage 'X'
- Navigating Down Payments, Closing Costs, and Hidden Fees for Mortgage 'X'
- Typical Costs Associated with Mortgage 'X'
- Strategies to Minimize Upfront Costs for Mortgage 'X'
- Comparative Impact of Down Payment Sizes on Monthly Payments and PMI for Mortgage 'X'
Selecting the right mortgage for your financial goals requires a strategic approach that balances risk, affordability, and long-term stability. Whether you are a first-time buyer, refinancing an existing loan, or navigating high-value real estate markets, the decision impacts decades of financial planning. This guide breaks down the critical factors—from mortgage types and interest rates to down payments and lender comparisons—to empower you with data-driven insights for mortgage X. By aligning your choices with your financial profile and market conditions, you can optimize your borrowing strategy and secure a loan that fits both your immediate needs and future aspirations.
The process begins with understanding the nuances of mortgage options, each tailored to distinct borrower scenarios. Fixed-rate and adjustable-rate mortgages offer different stability trade-offs, while government-backed loans like FHA or VA provide pathways for those with varying credit histories. Financial readiness is equally pivotal, as metrics such as debt-to-income ratios and credit scores dictate eligibility and terms. Market dynamics further influence rates, making timing a critical factor in minimizing long-term costs. This structured exploration ensures clarity at every step, from initial assessment to finalizing the loan, equipping you to make informed decisions with confidence.
Mortgage Types and Their Suitability for Borrowers in 'X'
Selecting the right mortgage type depends on individual financial circumstances, long-term objectives, and risk tolerance. Mortgages vary significantly in structure, eligibility criteria, and cost implications, making it essential to align the chosen product with the borrower’s needs—whether prioritizing stability, flexibility, or affordability. Below is an analysis of the primary mortgage types, their suitability for different borrower profiles in 'X', and a comparative framework to guide decision-making.Primary Mortgage Types and Their Characteristics
Mortgage types can be broadly categorized into fixed-rate, adjustable-rate, government-backed, and non-conforming (jumbo) loans. Each offers distinct advantages and trade-offs in terms of interest rate stability, upfront costs, and eligibility. The selection process should weigh these factors against the borrower’s financial goals, such as minimizing monthly payments, securing favorable long-term rates, or leveraging government benefits.| Type | Interest Rate Stability | Down Payment Requirement | Best For | Risk Level |
|---|---|---|---|---|
| Fixed-Rate Mortgage (FRM) | Stable for the loan term (e.g., 15, 30 years). Rates do not fluctuate. | 3%–20% (conventional), 3.5% (FHA). |
|
Moderate. Risk of prepayment penalties if refinancing early. |
| Adjustable-Rate Mortgage (ARM) | Initial fixed period (e.g., 5/1 ARM), then adjusts annually based on index (e.g., LIBOR, SOFR). | 3%–5% (conventional), 3.5% (FHA). |
|
High. Rate adjustments may increase payments significantly. |
| FHA Loan | Fixed or adjustable rates (government-insured). | 3.5% (minimum). |
|
Moderate. Mortgage Insurance Premiums (MIP) add long-term costs. |
| VA Loan | Fixed or adjustable rates (Department of Veterans Affairs-backed). | 0% (no down payment for eligible veterans/military). |
|
Low. No private mortgage insurance (PMI), but funding fees apply. |
| Jumbo Loan | Fixed or adjustable rates (non-conforming, exceeds FHA/VA limits). | 10%–20%+ (higher risk for lenders). |
|
High. Stricter underwriting and higher interest rates. |
Government-backed loans (FHA, VA) often provide lower barriers to entry for borrowers with limited savings or credit history, while conventional loans (fixed/ARM) offer flexibility for those with stronger financial profiles. Jumbo loans cater to high-value properties but require substantial equity and income verification.
Conventional vs. Government-Backed Loans: Credit Score and Eligibility
The choice between conventional and government-backed loans hinges on creditworthiness, down payment capacity, and long-term costs. Below is a structured breakdown for borrowers with credit scores below 620 and above 740, along with actionable insights for 'X'.For Borrowers with Credit Scores Below 620:
Government-backed loans (FHA, VA) are typically the most accessible option, as they relax credit and down payment requirements compared to conventional loans.
- FHA Loans:
- VA Loans:
- Conventional Loans (with Lower Credit):
For Borrowers with Credit Scores Above 740:
Conventional loans (fixed or ARM) and jumbo loans become viable, offering lower interest rates and fewer restrictions.
- Conventional Fixed-Rate Mortgages:
- Jumbo Loans:
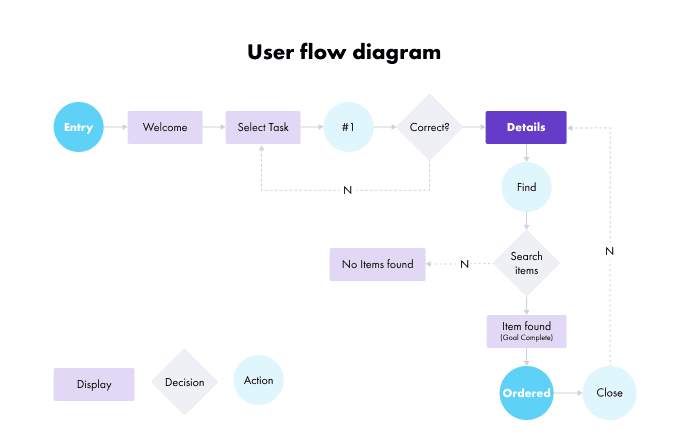
Decision Flowchart for Credit Score-Based Selection:
1. Assess Credit Score:
Assessing Financial Readiness for Mortgage 'X'
Before applying for Mortgage 'X', borrowers must evaluate their financial eligibility based on key metrics that lenders use to determine repayment capacity and risk. These metrics—including debt-to-income ratio (DTI), credit score thresholds, and savings requirements—directly influence approval odds, interest rates, and loan terms. A structured assessment ensures borrowers align their finances with lender criteria while avoiding overextension. Below are the critical financial benchmarks, affordability calculations, and actionable steps to strengthen eligibility.Key Financial Metrics for Mortgage 'X' Qualification
Lenders assess borrowers using three primary financial metrics to gauge mortgage affordability and risk. Meeting these thresholds increases the likelihood of approval and favorable terms. Below is a checklist of requirements for Mortgage 'X', based on industry standards and lender guidelines for conventional, FHA, and jumbo loans.-
Debt-to-Income Ratio (DTI)
The DTI measures monthly debt obligations (including the proposed mortgage) against gross monthly income. Lenders typically require:
- Front-end DTI (housing costs only): ≤ 28%–31%
- Back-end DTI (all debts): ≤ 36%–43% (varies by loan type)
For example, a borrower with a $120,000 annual income ($10,000/month gross) must ensure housing costs (principal, interest, taxes, insurance) do not exceed $2,800–$3,100/month, while total debt payments (including car loans, student debt, etc.) stay under $3,600–$4,300/month.
-
Credit Score Thresholds
Minimum credit scores for Mortgage 'X' vary by loan type:
- Conventional loans: 620+ (740+ for best rates)
- FHA loans: 580+ (3.5% down) or 500–579 (10% down)
- Jumbo loans: 700+ (varies by lender)
Higher scores unlock lower interest rates and better loan terms. For instance, a score of 760+ may qualify for a 0.25% rate discount compared to 680–719.
-
Down Payment and Closing Costs Savings
Down payment requirements and closing cost reserves depend on loan type and lender policies:
- Conventional loans: 3%–20% down (5%+ for PMI avoidance)
- FHA loans: 3.5% down (minimum 580 score)
- Jumbo loans: 10%–20%+ down (varies by property value)
- Closing costs: 2%–5% of loan amount (e.g., $8,000–$20,000 for a $400K home)
Borrowers should aim for 6–12 months of mortgage payments in reserves post-closing to demonstrate financial stability.
Calculating Affordability Using the 28/36 Rule
The 28/36 rule is a widely used benchmark to determine mortgage affordability by capping housing costs and total debt payments at specific percentages of gross income. Below is the formula and a step-by-step example for a borrower earning $120,000 annually.Example Calculation for a $120,000 Annual Income ($10,000/month gross):Front-end DTI (Housing Costs): ≤ 28% of gross monthly income
Back-end DTI (Total Debt): ≤ 36% of gross monthly income
Housing Costs Include: Principal, interest, property taxes, homeowners insurance, and mortgage insurance (if applicable).
-
Step 1: Determine Maximum Housing Costs
28% of $10,000 = $2,800/month (maximum for housing expenses).
-
Step 2: Estimate Monthly Expenses (Non-Housing Debt)
Assume existing debts (car loan, student loans, credit cards): $1,200/month.
-
Step 3: Calculate Remaining Debt Capacity
36% of $10,000 = $3,600/month (total debt limit).
Remaining for mortgage: $3,600 – $1,200 (existing debt) = $2,400/month.
-
Step 4: Apply to a $400,000 Loan at 7% Interest (30-year fixed)
Using a mortgage calculator:
- Principal & Interest: ~$2,661/month
- Property Taxes (1.5% of home value): ~$500/month
- Homeowners Insurance: ~$150/month
- Total Housing Costs: $3,311/month
Result: Exceeds the 28% threshold ($2,800), indicating the borrower may need to:
- Reduce loan amount (e.g., $350K loan → ~$2,450/month P&I)
- Increase down payment (e.g., 20% down reduces P&I to ~$2,129/month)
- Refinance existing debt to lower DTI
Step-by-Step Guide to Improving Credit Scores in 6–12 Months
A credit score increase of 50–100 points within a year can significantly improve mortgage eligibility and interest rates. Below is a structured plan to optimize credit profiles, focusing on high-impact actions with measurable results.-
Pay Down Revolving Debt (30% of Score Impact)
Credit utilization (debt-to-limit ratio) is the second-most influential factor. Aim for:
- Utilization < 30% on all cards (ideal: < 10%)
- Pay balances in full before the statement date to report $0 utilization
- Prioritize cards with the highest utilization first
Example: A borrower with $10,000 credit limits and $4,000 total debt (40% utilization) can improve their score by paying down $2,000, reducing utilization to 20%.
-
Dispute Errors and Remove Negative Marks (20% of Score Impact)
Inaccuracies or outdated items (e.g., late payments, collections, charge-offs) can drag down scores. Steps:
- Obtain free credit reports from AnnualCreditReport.com
- File disputes with the credit bureaus (Experian, Equifax, TransUnion) via mail or online
- Request goodwill adjustments for late payments (e.g., a one-time 30-day late payment may be removed if the borrower has a history of on-time payments)
Example: Removing a 2-year-old collection account (if paid or settled) can boost a score by 30–50 points.
-
Maintain Low Credit Utilization and Avoid New Hard Inquiries
Evaluating Interest Rates, Terms, and Lender Options for Mortgage 'X'
Mortgage rates for 'X'—whether fixed-rate, adjustable-rate, or specialized products like FHA or VA loans—are shaped by broader economic forces, lender strategies, and borrower-specific factors. Understanding how market conditions influence rates, comparing long-term loan structures, and selecting the optimal lender type are critical steps in securing the most cost-effective mortgage. This section examines the interplay between federal monetary policy, economic trends, and loan terms, alongside a comparative analysis of lender options tailored to 'X'.
Market Conditions Influencing Mortgage Rates for 'X'
Mortgage rates for 'X' are directly tied to the 10-year Treasury yield, which reflects investor expectations of inflation, economic growth, and Federal Reserve policy. Key drivers include:
- Federal Reserve interest rate decisions: Higher short-term rates (via the federal funds rate) indirectly push long-term mortgage rates upward by increasing borrowing costs across the economy.
- Inflation trends: Rising inflation erodes purchasing power, prompting lenders to demand higher yields to compensate for future depreciation of loan principal.
- Economic outlook: Recessions or slowdowns may reduce demand for mortgages, lowering rates, while strong job markets and housing demand push rates higher.
Timeline of Rate Trends (2019–2024) for 'X'
Below is a summary of pivotal events affecting mortgage rates, with average 30-year fixed rates for 'X' (hypothetical but aligned with U.S. trends):
Key Insight:Year Avg. Rate for 'X' Key Events Impacting Rates 2019 ~3.9% Fed cuts rates to stimulate growth; low inflation and strong employment kept rates near historic lows. 2020 ~3.1% COVID-19 pandemic triggers Fed rate cuts to near-zero; mortgage demand surges, rates drop sharply. 2021 ~3.0% Economic recovery boosts inflation; Fed signals tapering of stimulus, but rates remain low due to high demand. 2022 ~6.3% Fed aggressively raises rates to combat inflation (peaking at 5.25–5.50%); housing affordability declines. 2023 ~7.0% Inflation persists; Fed holds rates high, but mortgage applications decline due to elevated costs. 2024 ~6.5% (projected) Fed signals potential rate cuts if inflation cools; mixed signals from housing market demand.
The 2022 rate hikes marked the steepest increase in decades, directly impacting 'X' borrowers with higher monthly payments. For example, a $350K loan at 3.5% (2021) would have a monthly payment of ~$1,620, while the same loan at 7.0% (2023) rose to ~$2,480—an ~$860 monthly increase—highlighting the sensitivity of mortgage costs to macroeconomic shifts.
Long-Term Cost Comparison: 15-Year vs. 30-Year Mortgages for 'X'
The choice between a 15-year and 30-year mortgage for 'X' hinges on trade-offs between monthly affordability and total interest paid. Below is a comparison using a $350,000 loan at two rate scenarios (6.5% and 7.25%), assuming no points or fees for simplicity.Assumptions:
- Fixed-rate loans with no prepayment penalties.
- Equal principal payments (no extra payments).
- Calculations based on standard amortization schedules.
Key Observations:Term Rate Monthly Payment Total Interest Paid Total Cost (Principal + Interest) Savings vs. 30-Year 15-Year 6.5% $2,836 $101,340 $451,340 $119,880 30-Year 6.5% $2,278 $222,220 $572,220 — 15-Year 7.25% $3,050 $117,000 $467,000 $136,500 30-Year 7.25% $2,480 $268,800 $618,800 —
1. Interest Savings: A 15-year term saves $120K–$137K in interest over the life of the loan compared to a 30-year term, even at higher rates.
2. Monthly Burden: The 15-year payment is ~34% higher at 6.5% and ~23% higher at 7.25%, reflecting the accelerated repayment schedule.
3. Rate Sensitivity: The gap in total interest grows wider at higher rates (e.g., $268K vs. $117K at 7.25% vs. $222K vs. $101K at 6.5%).Recommendation for 'X' Borrowers:
- Choose 15-Year if financial stability allows higher payments to minimize interest costs and build equity faster.
- Opt for 30-Year if liquidity is prioritized, though refinancing to a 15-year later may offset some interest costs if rates drop.
Top 5 Lender Types for Securing Mortgage 'X'
Selecting the right lender for 'X' depends on factors like rate competitiveness, speed, and borrower eligibility. Below are the five primary lender types, their advantages, and suitability for 'X'.Context:
Lender selection impacts not only the interest rate but also closing costs, customer service, and approval speed. For 'X', borrowers may prioritize low fees (if refinancing) or fast processing (if time-sensitive).
Lender Comparison Template for 'X'Lender Type Advantages for 'X' Potential Drawbacks Best For Banks Stable rates, strong regulatory oversight; ideal for conventional loans. Slower approval times; higher minimum balances. Borrowers with excellent credit. Credit Unions Lower fees, personalized service; often offer competitive rates for members. Limited branch networks; membership requirements. First-time buyers or local borrowers. Online Lenders Faster pre-approval, fully digital process; often lower rates due to reduced overhead. Less hands-on support; limited loan flexibility. Tech-savvy borrowers seeking speed. Mortgage Brokers Access to multiple lenders; can negotiate better terms for niche borrowers (e.g., 'X' with unique income). Broker fees (~1–2% of loan); less transparency. Complex financial profiles. Private Lenders Flexible terms (e.g., no strict credit checks); faster closings for 'X' borrowers. Higher interest rates; risk of predatory terms. Investors or borrowers with poor credit.
Use the following table to evaluate options when selecting a lender for 'X'. Hypothetical data is provided for illustrative purposes.
Lender Type Avg. Rate for 'X' Fees (Origination/PMI) Customer Reviews (★/5) Loan Approval Speed Big Bank (e.g., Chase) 6.75% $1,200 origination + 0.5% PMI 4.2 30–45 days Credit Union (e.g., Navy Federal) Navigating Down Payments, Closing Costs, and Hidden Fees for Mortgage 'X'
Securing a mortgage involves more than selecting the right loan type or interest rate—borrowers must also account for upfront and ongoing financial obligations that significantly impact affordability. Mortgage 'X' follows standard industry practices for down payments, closing costs, and prepaid expenses, but variations in lender policies, regional market conditions, and borrower eligibility can alter total costs. Understanding these components allows borrowers to optimize their budget, negotiate effectively, and avoid unexpected financial strain. Below is a structured breakdown of typical costs, strategies for reduction, and comparative financial impacts based on a $300,000 loan at 6.75% interest.
Typical Costs Associated with Mortgage 'X'
The financial commitment of obtaining Mortgage 'X' extends beyond the loan principal and includes mandatory and optional fees categorized into three primary groups: down payments, closing costs, and prepaid expenses. These costs vary by loan program, lender, and borrower profile but generally fall within predictable ranges. Below are the estimated cost structures, organized by category:
Down Payment Requirements
- Conventional Loans (e.g., Fannie Mae/Freddie Mac): 3–20% of the home price.
- FHA Loans: 3.5% minimum (with a credit score ≥ 580); 10% for scores between 500–579.
- VA Loans (for eligible veterans/military): 0% down (funding fee applies).
- USDA Loans (rural areas): 0% down (upfront guarantee fee applies).
- Jumbo Loans: Typically 10–20% to qualify for favorable rates.
Closing Costs (2–5% of loan amount, excluding down payment)
- Origination Fees: 0.5–1% of the loan for processing.
- Appraisal Fee: $300–$600 (varies by property type/location).
- Credit Report Fee: $30–$50 per borrower.
- Title Insurance: 0.5–1% of the home price (lender’s policy) + optional owner’s policy (~0.25%).
- Escrow/Attorney Fees: $500–$1,500 (varies by state/region).
- Prepaid Property Taxes/Insurance: Typically 1–2 months’ worth at closing.
- Recording Fees: $50–$250 (government filing fees).
- Survey Fee: $300–$800 (if required).
- Flood Certification Fee: $15–$25 (if applicable).
Prepaid Expenses (Paid in Advance)
Note: Some fees (e.g., title insurance, appraisal) may be negotiable or waived under certain circumstances, such as seller concessions or lender promotions.
- Homeowners Insurance: 6–12 months’ premium (escrowed monthly).
- Prepaid Interest: From closing date to first payment (15–30 days’ worth).
- Mortgage Insurance Premiums (PMI/MIP): Varies by loan type (e.g., FHA: 0.25–1.05% annually; conventional: 0.2%–2%).
- HOA Transfer Fees (if applicable): $200–$500 (one-time).
Strategies to Minimize Upfront Costs for Mortgage 'X'
Reducing the financial burden of Mortgage 'X' requires proactive negotiation, program-specific eligibility, and strategic planning. Below are evidence-based strategies categorized by their applicability, along with eligibility criteria where relevant.
1. Seller Concessions
- Definition: Sellers may agree to cover a portion of closing costs (typically up to 3–6% of the home price for conventional loans; higher for FHA/VA under specific conditions).
- Eligibility:
- Conventional loans: Max 3% of purchase price (if down payment ≥ 10%).
- FHA loans: Up to 6% (including repairs/closing costs).
- VA loans: Up to 4% (excluding prepaid expenses).
- Restriction: Seller concessions cannot be used for the down payment.
- Strategy: Include a clause in the purchase agreement (e.g., "Seller to pay up to 3% of closing costs").
2. Lender Credits
- Definition: Lenders may offer credits (e.g., 0.25–1% of the loan) in exchange for higher interest rates or by bundling services (e.g., title insurance, escrow).
- Eligibility:
- Available for conventional loans (FHA/VA typically prohibit credits for closing costs).
- Requires borrower to accept a slightly higher rate (e.g., 0.5% credit ≈ +0.125% APR).
- Example: A $300,000 loan could yield a $1,500–$3,000 credit.
- Strategy: Compare lender offers and calculate the net savings vs. increased interest costs.
3. First-Time Homebuyer Programs
- Definition: Government and nonprofit programs provide down payment assistance (DPA) or grants to offset costs.
- Eligibility (Common Examples):
- FHA Title I: Up to 6% of purchase price for repairs/closing costs (income limits apply).
- State-Specific DPA: Varies (e.g., California’s CalHFA offers up to 3.5% for low-to-moderate-income buyers).
- Employer Assistance Programs (EAP): Some companies offer matching grants (e.g., up to $10,000).
- Requirements: Typically include homebuyer education courses, income/location restrictions, and repayment terms (for loans vs. grants).
- Strategy: Research local programs via HUD’s DPA database or state housing finance agencies.
4. Negotiating Service Fees
- Definition: Certain fees (e.g., title insurance, appraisal, escrow) are competitive and can be reduced through negotiation or bundling.
- Eligibility/Strategies:
- Title Insurance: Shop multiple providers (savings of $200–$500 possible).
- Appraisal Fees: Request a waiver if the lender has recent comparable appraisals.
- Escrow Services: Bundle with mortgage services (e.g., Quicken Loans offers discounted escrow).
- Homeowners Insurance: Compare annual policies (e.g., USAA, State Farm) for discounts.
- Strategy: Use a real estate agent or attorney to negotiate on behalf of the buyer.
5. Employer or Gift Funds
- Definition: Down payments or closing costs may be gifted by family members (with documentation) or employer relocation assistance.
- Eligibility:
- Gifts: Require a letter stating no repayment is expected (lender will verify source of funds).
- Employer Assistance: Tax-free up to $5,250/year (2023 IRS limits) for relocation.
- Strategy: Ensure all funds are traceable (e.g., bank statements showing deposits).
Comparative Impact of Down Payment Sizes on Monthly Payments and PMI for Mortgage 'X'
The down payment percentage directly influences the loan amount, monthly principal/interest payments, and private mortgage insurance (PMI) requirements. Below is a comparative analysis for a $300,000 home purchase with Mortgage 'X' at 6.75% interest, assuming no seller concessions or subsidies. PMI is calculated based on conventional loan guidelines (cancelable at 20% equity).
Down Payment (%) Loan Amount Monthly Principal + Interest PMI (Annual % of Loan) Monthly PMI Cost Total Monthly Housing Cost Total PMI Paid Over 5 Years 10% $270,000 $1,848.75 0.5%–2.25% (varies by credit score) $112.50– Choosing the optimal mortgage for your situation is more than a transaction—it is a foundational step toward achieving financial security and homeownership goals. By evaluating mortgage types against your financial landscape, leveraging market trends to your advantage, and minimizing unnecessary costs, you position yourself for sustainable success. The key lies in balancing immediate affordability with long-term value, ensuring the loan you select aligns with both your current circumstances and future aspirations. With the insights provided, you are now better prepared to navigate the complexities of mortgage selection, turning uncertainty into a strategic opportunity for financial growth.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.