Flood Insurance T X Key Regulations Policies Costs
Table of Contents
- State-Specific Flood Insurance Regulations in Texas
- Comparison of NFIP vs. Private Flood Insurance in Texas
- Legal Framework Governing Flood Insurance in Texas
- Role of the Texas Department of Insurance (TDI) in Flood Insurance Regulation
- High-Risk Zones and Flood Mapping in Texas
- Methodology for Flood Zone Classification in Texas
- Texas Counties with Highest Flood Risk Exposure
- Impact of Base Flood Elevations (BFEs) and Floodway/Fringe Designations on Insurance Premiums
- Cost and Affordability of Flood Insurance in Texas
- Average Annual Premiums for NFIP Policies in Texas by Flood Zone
- Discounts for Flood Mitigation Measures and Their Impact on Premiums
- Case Study: Premium Spike After a FIRM Update and the Appeal Process
- Cost-Benefit Analysis of Common Flood Mitigation Strategies in Texas
- Financial Assistance Programs for Flood Insurance in Texas
Flood insurance in Texas presents a critical intersection of regulatory compliance, financial risk management, and adaptive resilience against an evolving threat landscape. With over 20% of properties in the state exposed to significant flood risk, understanding the distinctions between the National Flood Insurance Program and private insurers becomes essential for homeowners, businesses, and local governments. Texas’s unique blend of federal mandates, state-specific enforcement, and dynamic flood mapping—exacerbated by climate change and rapid urbanization—requires a structured approach to mitigate exposure while navigating complex claims processes and premium disparities.
The state’s legal framework, governed by the Texas Department of Insurance and FEMA-mapped flood zones, imposes mandatory coverage requirements for high-risk properties, often accompanied by strict waiting periods and exclusions that demand careful scrutiny. Meanwhile, private insurers offer tailored endorsements and mitigation incentives, creating a fragmented yet competitive market where policyholders must weigh cost, coverage limits, and long-term savings. From interpreting flood zone designations to challenging disproportionate premiums, Texas residents face a multifaceted challenge that extends beyond insurance to physical infrastructure and financial preparedness.
State-Specific Flood Insurance Regulations in Texas
Texas implements a dual framework for flood insurance, integrating federal guidelines under the National Flood Insurance Program (NFIP) with private market alternatives tailored to state-specific risks. While the NFIP sets baseline requirements for coverage in high-risk zones (Special Flood Hazard Areas, or SFHAs), Texas expands regulatory oversight through the Texas Department of Insurance (TDI) to address local flood vulnerabilities, such as urbanization-related flooding in Houston or coastal storm surges along the Gulf Coast. Key distinctions arise in coverage limits, exclusions, and mandatory enrollment, particularly for properties in FEMA-designated high-risk zones (A or V zones) or those subject to local ordinances requiring flood insurance. Private insurers in Texas often offer supplementary endorsements and faster claim processing but may impose stricter underwriting criteria for high-risk properties.The interplay between federal and state regulations ensures compliance with Texas Insurance Code §502.053 and FEMA’s Flood Insurance Rate Maps (FIRMs), while TDI enforces additional consumer protections, such as dispute resolution timelines and provider licensing. Below, structured comparisons and procedural frameworks clarify how homeowners navigate these requirements.
Comparison of NFIP vs. Private Flood Insurance in Texas
The National Flood Insurance Program (NFIP) and private flood insurance providers in Texas differ primarily in coverage scope, cost, and accessibility. While the NFIP is federally backed and mandatory for properties with mortgages in high-risk zones, private insurers offer competitive alternatives with potential for broader coverage or lower premiums, depending on risk assessment. Below is a comparative table outlining key policy distinctions relevant to Texas homeowners:| Policy Feature | NFIP (Federal) | Private Insurers (Texas) |
|---|---|---|
| Coverage Limits (Dwelling) | Up to $250,000 for building property; $100,000 for personal belongings (as of 2023). Limits apply per policy. | Varies by provider; some offer up to $500,000+ for high-value properties (e.g., coastal mansions). Limits may exclude certain high-risk items. |
| Coverage Limits (Secondary Residences) | Same as primary residence, but NFIP excludes rental income or business use without additional endorsements. | Often limited to $100,000–$200,000 for secondary homes; some insurers require primary residence coverage first. |
| Waiting Period for New Policies | 30-day waiting period for new policies (except for policy renewals or lapses <30 days). Late purchases exclude coverage for the waiting period. | Typically 10–30 days, with some insurers offering immediate coverage for existing risks (e.g., pre-storm policies). |
| Special Endorsements Available |
|
|
| Mandatory Enrollment Requirements | Required for mortgaged properties in SFHAs (FEMA Zones A or V) under Biggert-Waters Flood Insurance Reform Act (2012). Non-compliance risks mortgagee enforcement. | Not federally mandated, but lenders may require private flood insurance for high-risk properties. Some insurers offer "preferred provider" programs for mortgage holders. |
| Exclusions |
|
|
Legal Framework Governing Flood Insurance in Texas
Flood insurance in Texas operates under a multi-layered regulatory system combining federal NFIP mandates, state-specific statutes, and local ordinances. The primary legal pillars include:1. Federal Requirements (NFIP and FEMA)
2. Texas State Regulations
3. Interaction Between Federal and State Rules
Key Statute:
Texas Insurance Code §541.155: "An insurer may not refuse to issue or renew a policy of flood insurance in this state solely because the property is located in an area designated as having undetermined flood risk by the Federal Emergency Management Agency."
Role of the Texas Department of Insurance (TDI) in Flood Insurance Regulation
The Texas Department of Insurance (TDI) serves as the primary state regulator for flood insurance, ensuring consumer protection, provider accountability, and compliance with both federal and state laws. TDI’s oversight includes:1. Provider Licensing and Market Conduct
High-Risk Zones and Flood Mapping in Texas
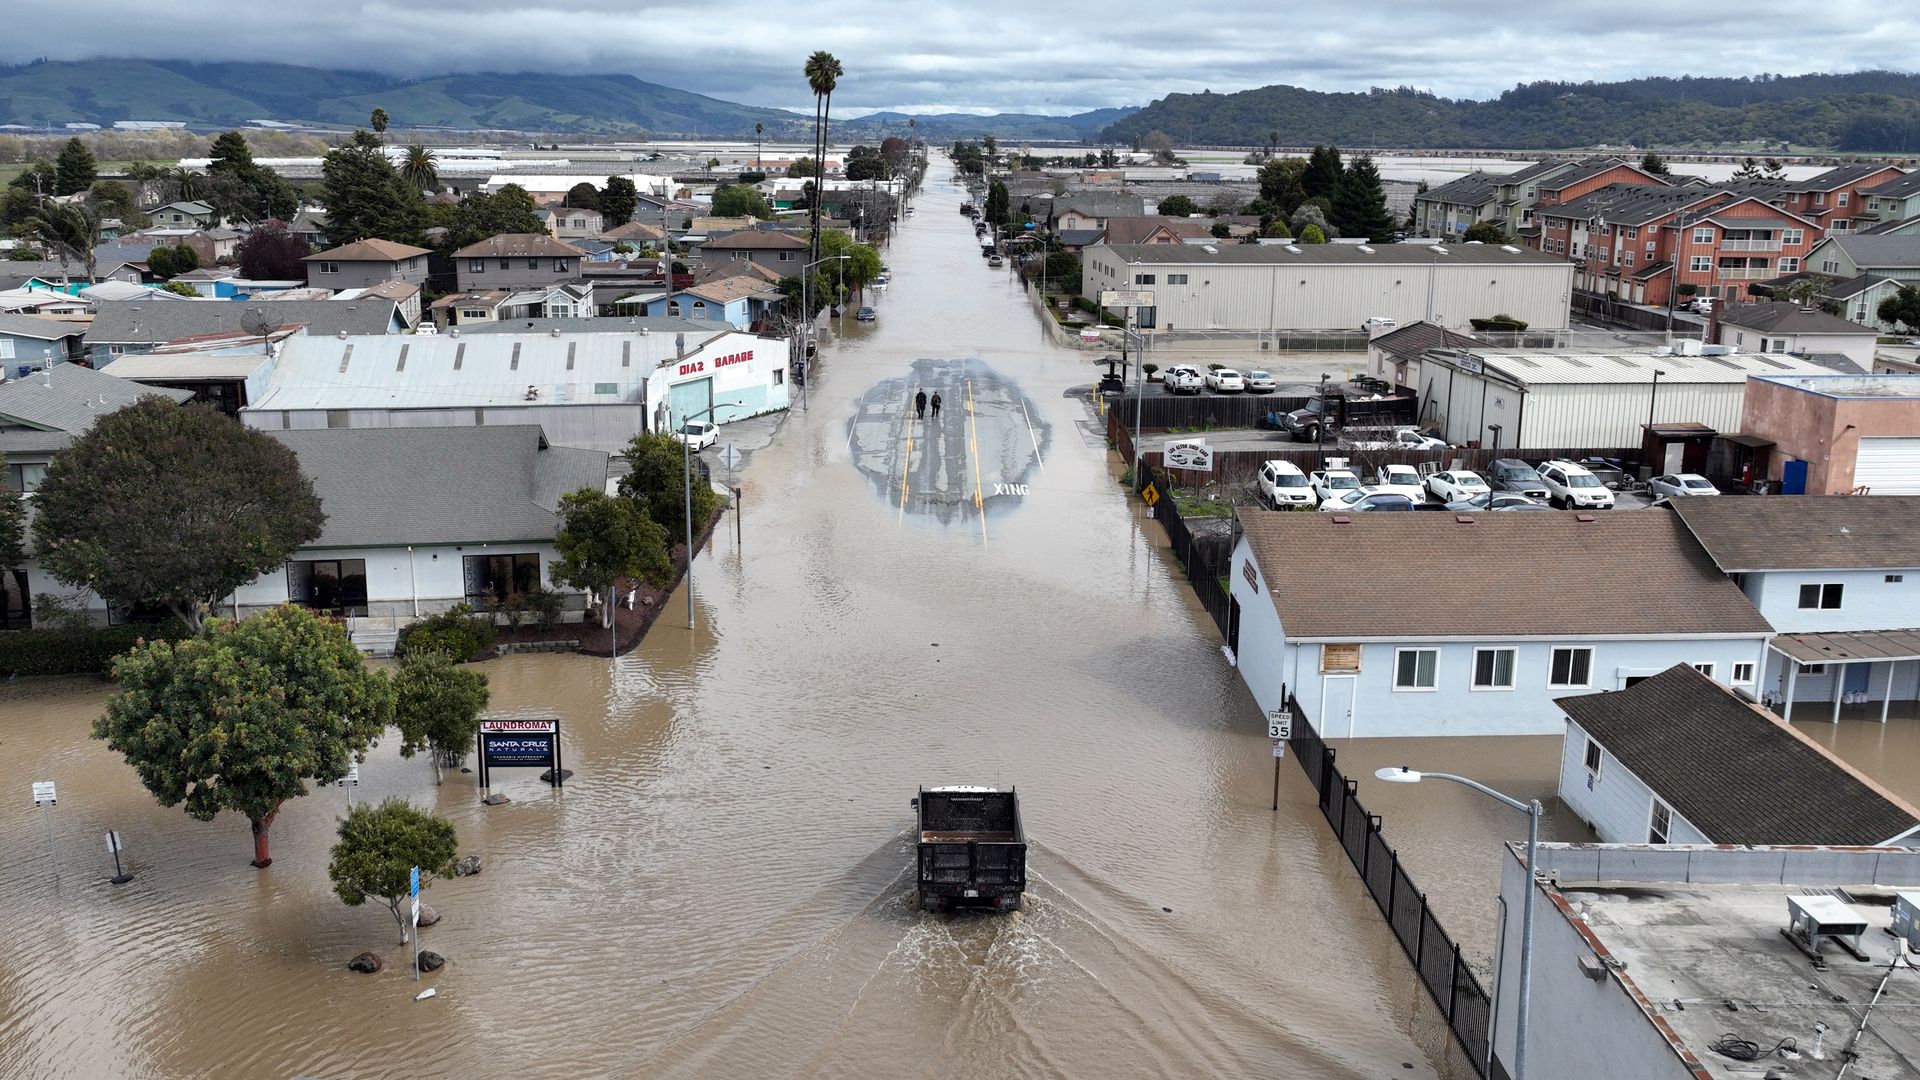
Texas utilizes a structured methodology to classify flood risk zones, primarily through collaboration between the Federal Emergency Management Agency (FEMA) and the Texas Water Development Board (TWDB). FEMA’s National Flood Insurance Program (NFIP) establishes standardized flood zone designations based on hydraulic modeling, historical flood data, and topographic analysis. The TWDB supplements this with state-specific hydrological studies, particularly in regions with limited FEMA data or rapidly changing flood risks. These classifications—Zone A (undetermined risk), AE (base flood elevation-defined), VE (coastal high-velocity flow), X (minimal risk), and unnumbered zones (outside regulatory floodways)—are derived from Flood Insurance Rate Maps (FIRMs), which integrate Digital Flood Insurance Rate Maps (DFIRMs) and Flood Insurance Study (FIS) reports. Private flood risk assessments, often conducted by insurers or engineering firms, may differ due to proprietary models or localized data, but they must align with FEMA’s baseline criteria for regulatory compliance.Methodology for Flood Zone Classification in Texas
FEMA’s flood zone classification in Texas follows a three-tiered approach:1. Hydrologic and Hydraulic Modeling: FEMA employs Hydrographic (HEC) models to simulate floodplain inundation, incorporating rainfall intensity, terrain, and drainage systems. The Texas Flood Plain Mapping Program, managed by the TWDB, enhances these models with high-resolution LiDAR data and real-time river gauge measurements, critical for regions like the Brazos River Basin or Houston’s Addicks and Barker Reservoirs.
2. Historical Flood Data Integration: FEMA cross-references past flood events (e.g., Hurricane Harvey (2017), Tropical Storm Imelda (2019), or the 2002 Brazos River floods) to validate model accuracy. The TWDB augments this with state-specific flood databases, including Texas Floodplain Atlas records.
3. Regulatory Zoning:
Private assessments may refine these zones by incorporating site-specific soil permeability tests or localized drainage studies, but FEMA’s classifications remain the legal standard for insurance and building permits.
Texas Counties with Highest Flood Risk Exposure
The following table highlights Texas counties where ≥30% of properties lie in high-risk zones (A/AE/VE), based on FEMA’s 2023 DFIRMs and TWDB reports. Average annual flood loss estimates are derived from FEMA’s Risk Mapping, Assessment, and Planning (Risk MAP) program and Texas A&M University’s Hazard Reduction and Recovery Center (HRRC).| County Name | Total Properties in High-Risk Zones (A/AE/VE) | Average Annual Flood Loss (USD) | Notable Historical Flood Events |
|---|---|---|---|
| Harris (Houston) | 120,000+ | $1.2 billion |
|
| Galveston | 35,000+ | $450 million |
|
| Brazos | 22,000+ | $300 million |
|
| Jefferson (Beaumont/Port Arthur) | 28,000+ | $280 million |
|
| Fort Bend (Sugar Land/Missouri City) | 32,000+ | $400 million |
|
Impact of Base Flood Elevations (BFEs) and Floodway/Fringe Designations on Insurance Premiums
Flood insurance premiums in Texas are directly tied to a property’s flood zone, BFE, and floodway/fringe status, as outlined in the National Flood Insurance Program (NFIP). The Flood Insurance Manual (FIM) provides tiered risk-based pricing:1. Zone AE/VE (High-Risk):
2. Zone X (Moderate/Low Risk):
Cost and Affordability of Flood Insurance in Texas
Flood insurance costs in Texas vary significantly based on flood zone classification, property characteristics, and mitigation efforts. The National Flood Insurance Program (NFIP) and private insurers offer distinct pricing models, with premiums influenced by risk exposure, historical claim data, and regulatory updates such as Flood Insurance Rate Map (FIRM) revisions. Understanding these dynamics is critical for homeowners to manage financial risks effectively, particularly in high-risk zones where premiums can escalate sharply. This section examines premium comparisons, mitigation discounts, financial assistance programs, and a case study illustrating the impact of FIRM updates on policyholder costs.Average Annual Premiums for NFIP Policies in Texas by Flood Zone
The cost of NFIP flood insurance in Texas is determined by flood zone designation, property value, and coverage limits. Premiums for Zone A (undetermined risk) and Zone AE (base floodplain) typically range from $500 to $2,500 annually for residential properties, while Zone VE (coastal high-velocity hazard areas) can exceed $10,000 due to extreme risk. Private insurers often offer competitive rates but may exclude coverage for certain high-risk properties or impose stricter underwriting criteria.Key factors influencing premiums include:
Comparison of NFIP vs. Private Insurer Premiums (2023 Estimates)
| Flood Zone | NFIP Average Annual Premium | Private Insurer Average Annual Premium | Notes |
|---|---|---|---|
| Zone A | $800–$1,500 | $600–$1,200 | Private insurers may require additional risk assessments. |
| Zone AE | $1,200–$2,500 | $900–$2,000 | Discounts available for mitigation measures (e.g., flood vents). |
| Zone VE | $3,000–$15,000+ | Limited availability (high-risk surcharges) | Private coverage often excludes windstorm or coastal flood exclusions. |
Discounts for Flood Mitigation Measures and Their Impact on Premiums
The NFIP and some private insurers provide premium reductions for homeowners who implement approved mitigation strategies. These discounts reflect reduced risk exposure and may apply retroactively upon completion of eligible improvements. Common mitigation measures and their potential savings include:- Flood vents and dry floodproofing: Installing vents in crawl spaces or sealing basements can reduce premiums by 10–25%.
Example of Mitigation Discount Application
A homeowner in Zone AE with a $2,000 annual NFIP premium installs flood vents ($3,000 cost) and receives a 20% discount, lowering their premium to $1,600 annually. Over 5 years, the savings ($2,000) offset the mitigation cost, with additional long-term protection benefits.
Case Study: Premium Spike After a FIRM Update and the Appeal Process
In 2022, a Houston homeowner in Zone X (previously considered low-risk) faced a 400% premium increase after their property was reclassified to Zone AE due to a FIRM update. The annual cost rose from $600 to $2,800, prompting an appeal through the Texas Department of Insurance (TDI) and FEMA. Below is the process they followed:Step 1: Request a Flood Insurance Rate Map (FIRM) ReviewKey Takeaways for Homeowners:
The homeowner submitted a Letter of Map Amendment (LOMA) to FEMA, providing evidence (e.g., elevation certificates, historical flood data) that their property was incorrectly rezoned. TDI assisted in gathering local engineering reports to support the appeal.Step 2: Appeal to FEMA’s Regional Office
FEMA reviewed the documentation and conducted a site visit. After 90 days, they denied the LOMA request, citing updated floodplain modeling. The homeowner then escalated the appeal to FEMA’s National Appeals Board.Step 3: Negotiate with the NFIP
While awaiting the appeals decision, the homeowner applied for temporary mitigation measures (e.g., installing a sump pump) to qualify for a 15% premium reduction, lowering their cost to $2,380. They also explored private insurance alternatives, securing a policy at $2,100 annually with broader coverage.Outcome:
The appeals process took 18 months, but the homeowner successfully reduced their premium to $1,900 by combining mitigation discounts and private insurance options. FEMA later approved a partial LOMA, reclassifying the property to Zone A, further stabilizing costs.
Cost-Benefit Analysis of Common Flood Mitigation Strategies in Texas
Mitigation measures reduce both flood damage and long-term insurance costs. Below is a 5–10-year cost-benefit analysis for typical strategies, assuming a $2,000 annual NFIP premium and a 3% annual discount compounding for approved improvements.| Mitigation Strategy | Upfront Cost (2024) | Estimated Annual Premium Reduction | Net Savings Over 5–10 Years | Additional Benefits |
|---|---|---|---|---|
| Retrofitting (flood doors, sump pumps) | $5,000–$15,000 | 10–20% ($200–$400) | $6,000–$24,000 | Reduces water damage; may qualify for tax credits (e.g., FEMA’s ICC program). |
| Elevating structures (foundation, utilities) | $10,000–$50,000+ | 25–35% ($500–$700) | $15,000–$42,000 | Extends property lifespan; may increase resale value. |
| Installing flood barriers (e.g., sandbags, permanent walls) | $2,000–$10,000 | 5–15% ($100–$300) | $3,000–$18,000 | Deployable barriers offer temporary protection; permanent walls require permits. |
| Landscaping adjustments (permeable pavements, berms) | $1,000–$8,000 | 5–10% ($100–$200) | $3,000–$12,000 | Improves drainage; may reduce erosion and property flooding. |
Financial Assistance Programs for Flood Insurance in Texas
Texas residents facing high flood insurance costs can access federal, state, and nonprofit programs to offset expenses. Below are key resources:Federal Programs
Navigating flood insurance in Texas demands a proactive and informed strategy, balancing immediate protection against potential financial devastation with long-term resilience investments. Whether through leveraging elevation certificates to reduce premiums, advocating for accurate flood zone classifications, or exploring mitigation grants, property owners hold the key to minimizing risk while adhering to regulatory obligations. As climate models project intensified flood frequencies and urban sprawl reshapes risk profiles, the interplay between federal programs, state oversight, and private innovation will continue to define the landscape. By prioritizing transparency, mitigation, and strategic planning, stakeholders can transform flood insurance from a reactive expense into a proactive tool for safeguarding Texas’s communities and economy.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.