Flood Insurance Florida Requirements And Solutions
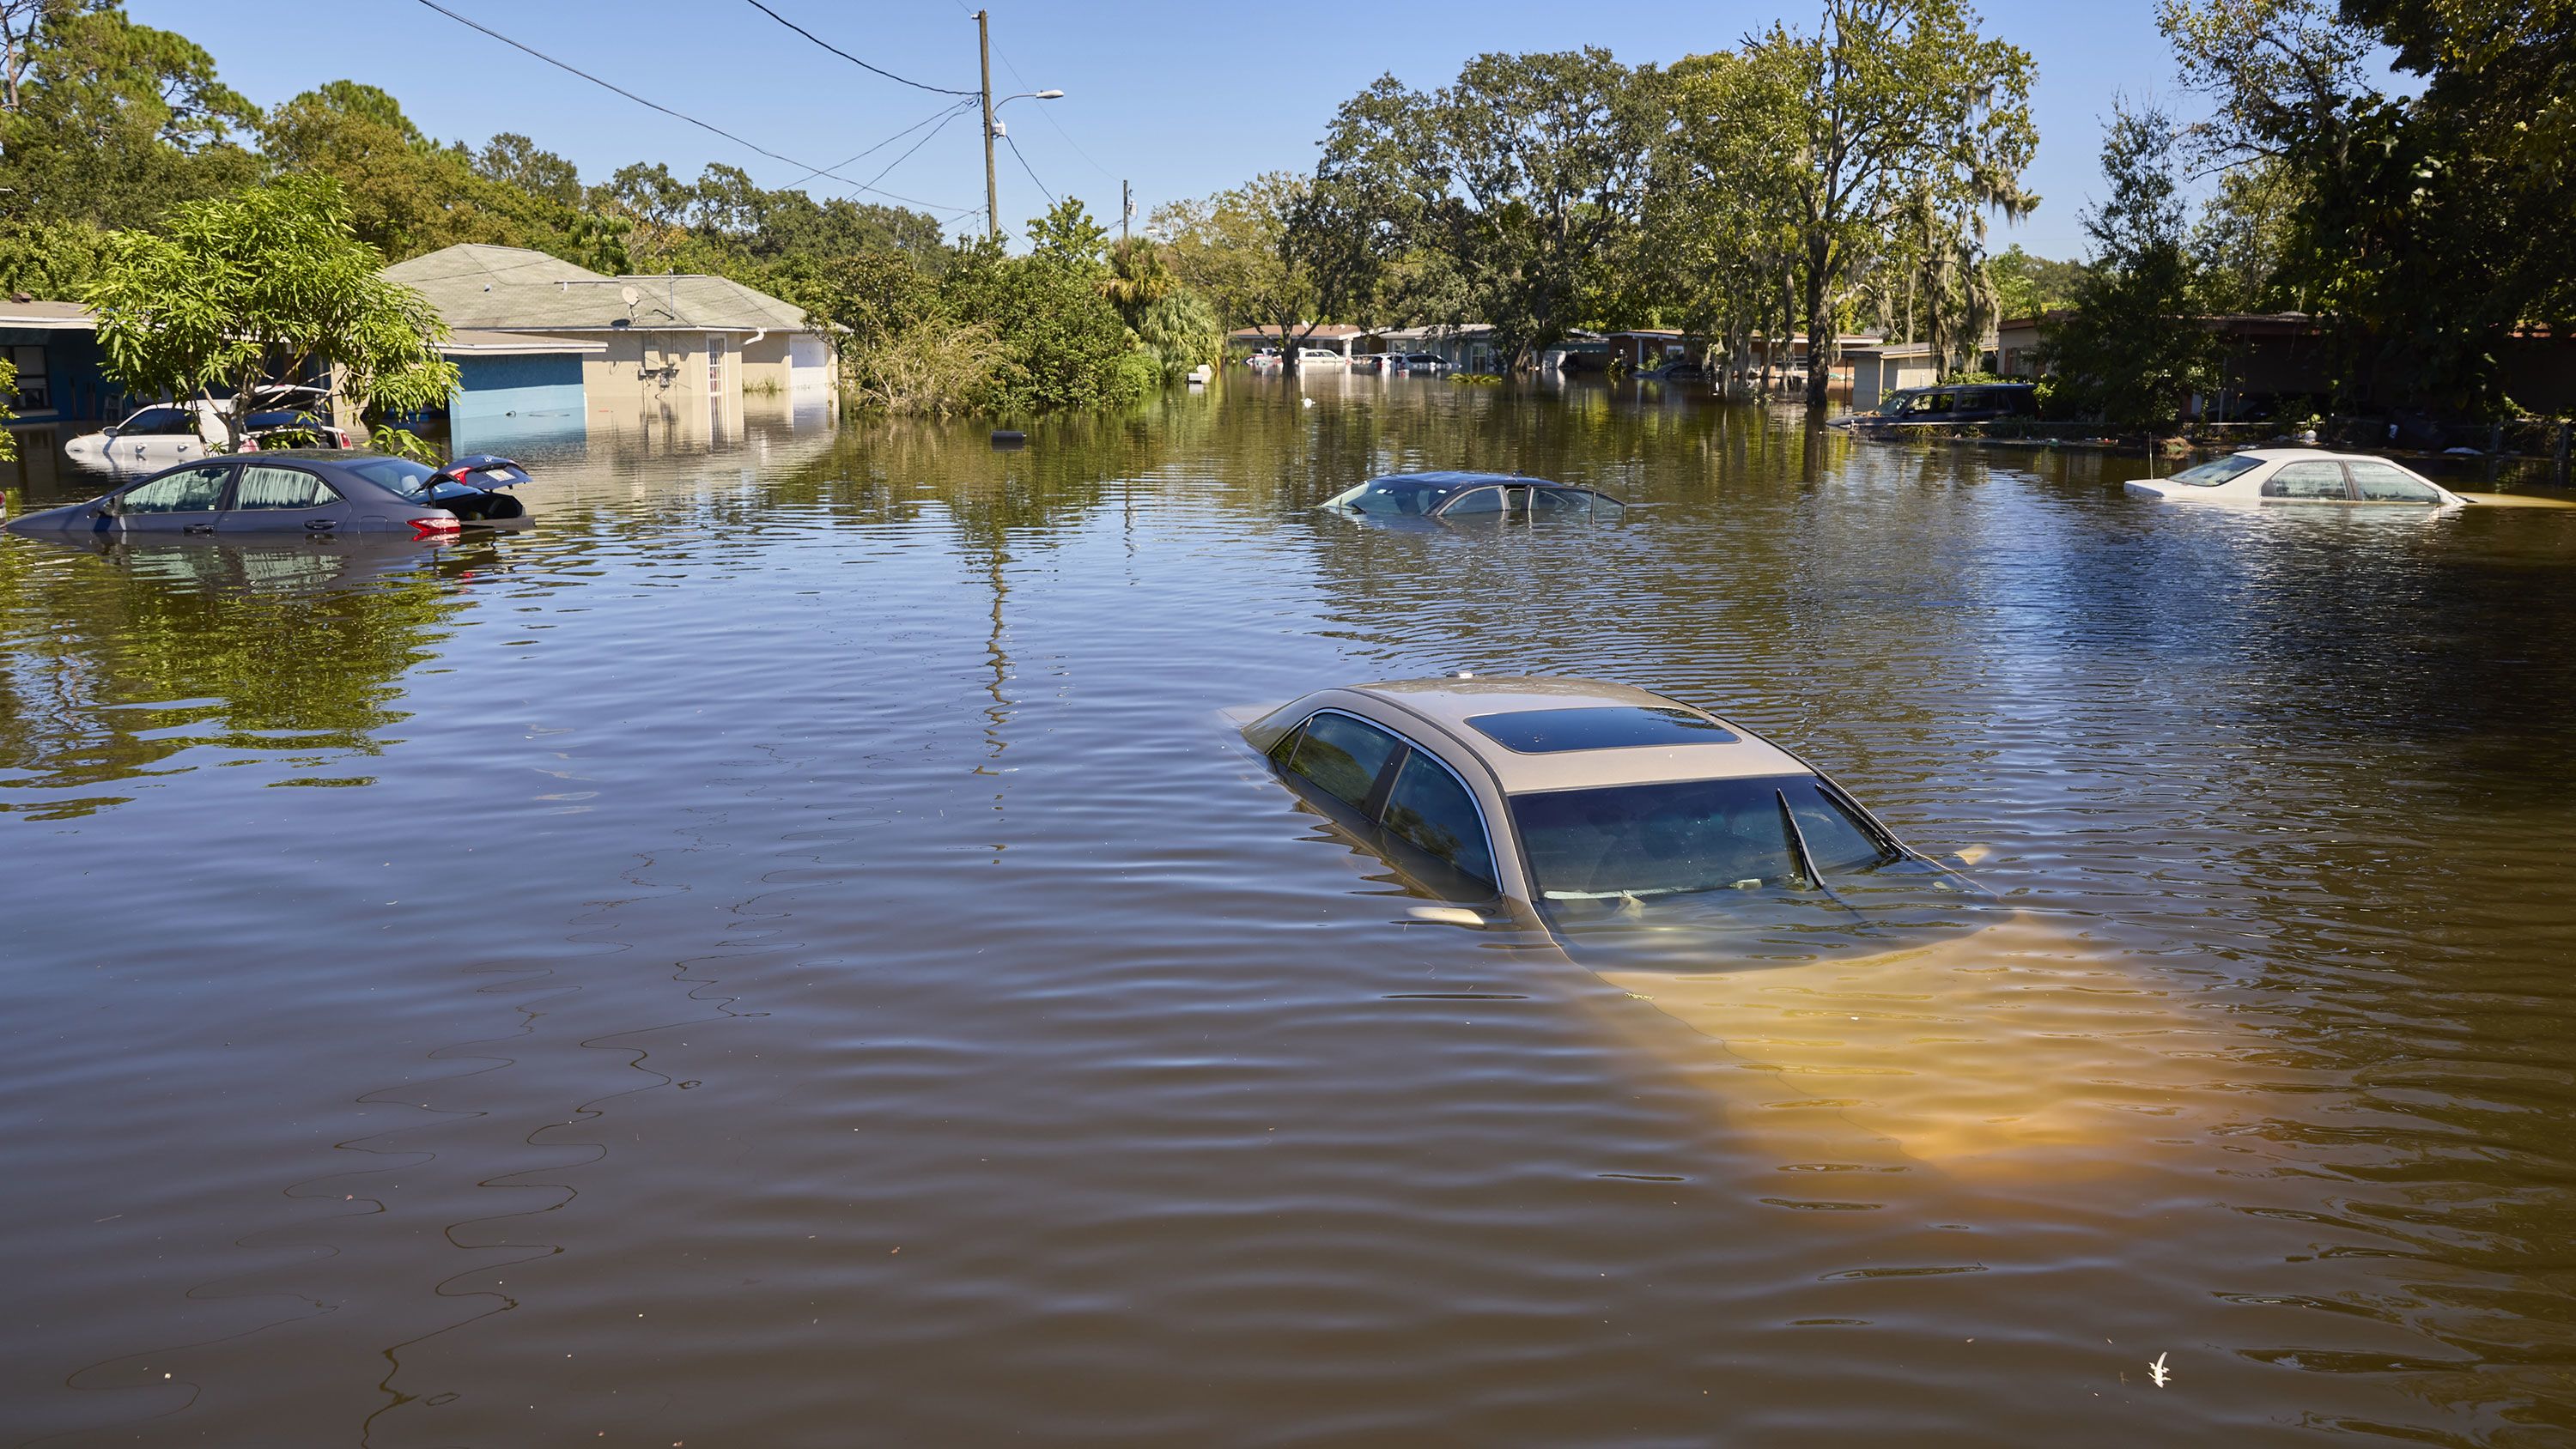
Table of Contents
- Current State of Flood Insurance in Florida
- Flood Risk Breakdown in Florida and Corresponding NFIP Coverage
- Comparison of Flood Insurance Premiums by County
- Demographic and Geographic Trends in NFIP vs. Private Insurance Adoption
- Regulatory and Policy Influences on Florida Flood Insurance
- Role of the Florida Office of Insurance Regulation (OIR) in Flood Insurance Oversight
- Impact of Florida Building Codes on Flood Insurance Requirements
- Financial Mechanisms: Assessments and Their Effect on Flood Insurance Premiums
- Legislative Updates and Their Direct Effects on Flood Insurance
- Challenges and Gaps in Florida’s Flood Insurance Framework
- Top Three Uninsured Flood Risks in Florida
- Affordability Crisis in Florida Flood Insurance
- Emerging Trends and Innovations in Flood Insurance
- AI and Machine Learning in Flood Risk Assessment
- Parametric Flood Insurance in Florida
- Flood Mitigation Incentives and Their Impact on Insurability
- Practical Steps for Florida Residents to Navigate Flood Insurance
- Assessing Flood Risk Using FEMA’s Flood Insurance Rate Maps (FIRMs) and NFIP’s Assistance Tool
- Comparing Flood Insurance Quotes: NFIP vs. Private Market
- Documenting Flood Damage for Insurance Claims
Florida’s flood insurance landscape reflects a critical intersection of regulatory complexity, financial vulnerability, and evolving climate risks. With nearly 40 percent of properties in high-risk flood zones, the state’s reliance on both the National Flood Insurance Program (NFIP) and private insurers underscores the urgency of understanding coverage gaps, premium disparities, and emerging mitigation strategies. From coastal communities grappling with storm surge to inland regions facing intensified rainfall, the financial and structural challenges demand proactive measures—whether through policy reforms, technological innovations, or individual preparedness.
The dynamics of Florida’s flood insurance market are further complicated by legislative shifts, such as Senate Bill 76, which redefines resiliency standards, and the growing adoption of parametric insurance models that promise faster payouts for predefined flood events. Meanwhile, affordability crises in high-risk counties like Miami-Dade and Monroe expose systemic inequities, while climate projections reshape risk assessments, forcing insurers to adapt. For residents, navigating this landscape requires a clear grasp of flood risk assessments, policy comparisons, and claim processes—each step critical to securing adequate protection in an environment where traditional models are increasingly inadequate.
Current State of Flood Insurance in Florida
Florida’s flood insurance landscape reflects a complex interplay of regulatory frameworks, market dynamics, and escalating climate risks. As of 2024, the state remains the most flood-prone in the U.S., with 67% of policyholders relying on the National Flood Insurance Program (NFIP)—a figure that underscores both the program’s dominance and the persistent gaps in private market penetration. Urban areas like Miami-Dade and Broward exhibit higher adoption rates (72–78%) due to stricter building codes and mandatory purchase requirements, while rural counties such as Liberty and Gilchrist lag behind (45–50%), driven by lower property values and limited awareness. Coastal regions, particularly those in FEMA’s high-risk zones (Zone V), account for 83% of NFIP policies in Florida, though inland communities face growing exposure to rainfall-induced flooding, which now accounts for 40% of all claims statewide.The division between NFIP and private insurers has stabilized but remains uneven. NFIP holds a 62% market share in Florida, with 1.8 million policies active as of 2023, while private insurers cover 38% of properties, primarily in lower-risk zones (X and B). Policyholders under NFIP skew older (median age 65+) and lower-income (42% earn <$50K annually), whereas private insurance attracts younger, higher-income demographics (median age 42; 58% earn >$75K). This disparity highlights affordability barriers and the NFIP’s role as a safety net for vulnerable populations.
Flood Risk Breakdown in Florida and Corresponding NFIP Coverage
Florida’s flood risks are categorized by source, frequency, and severity, each influencing coverage limits and exclusions under the NFIP. The three dominant risks—hurricane storm surge, riverine flooding, and rainfall-induced flooding—account for 95% of claims in the state. Below is an organized analysis of these risks, their geographic prevalence, and NFIP response mechanisms.Key Flood Risk Types and NFIP Coverage Parameters
Florida’s flood risks are not uniformly distributed; hurricane storm surge dominates coastal counties (e.g., Monroe, Hillsborough), while riverine flooding affects inland regions (e.g., Orange, Polk), and rainfall-induced flooding has surged in recent years due to urbanization and climate change. The NFIP’s Standard Flood Insurance Policy (SFIP) provides $250,000 for building property and $100,000 for personal belongings, but exclusions and sub-limits vary by risk type. For instance, wind damage from storm surge is excluded unless accompanied by floodwater entry through a wall or foundation—a critical distinction given Florida’s hurricane vulnerability.
Comparison of Flood Insurance Premiums by County
Flood insurance costs in Florida vary significantly by county, influenced by risk zone classification, historical claim data, and mitigation efforts. Below is a responsive table comparing average annual premiums, deductible ranges, and claim payout trends for select counties, based on 2023–2024 NFIP and private insurer data. Premiums are presented as annual costs for a $250K building policy, with deductibles expressed as percentages of claim amounts.Table: Flood Insurance Premiums and Claim Trends by County
| County | Risk Zone Dominance | Avg. Annual Premium (NFIP) | Private Insurer Avg. Premium | Deductible Range | 5-Year Claim Payout Trend (2019–2023) | Key Risk Drivers |
|---|---|---|---|---|---|---|
| Miami-Dade | V (Coastal), A (Surge) | $4,200 | $3,800–$5,500 | 2–10% | ↑ 180% (Surge claims) | Hurricane storm surge, sea-level rise |
| Broward | V, A | $3,900 | $3,500–$5,200 | 2–8% | ↑ 120% (Rainfall + surge) | Urban drainage failures, high density |
| Hillsborough | A, B (Inland) | $2,800 | $2,200–$3,900 | 1–5% | ↑ 90% (Riverine flooding) | Tampa Bay surge, heavy rainfall events |
| Orange | A, C (Moderate) | $2,100 | $1,800–$3,200 | 1–4% | ↑ 75% (Rainfall-induced) | Lake Okeechobee overflow, urban sprawl |
| Monroe | V (Keys), D (Low) | $1,500 (Keys) / $800 (Inland) | $1,200–$2,500 | 1–3% | ↓ 10% (Keys) / ↑ 60% (Inland) | Hurricane direct hits, coral reef erosion |
| Polk | B, C (Inland) | $1,900 | $1,500–$2,800 | 1–5% | ↑ 85% (Riverine + rainfall) | Lake Wales ridgeline flooding |
| Lee | V, A (Coastal) | $3,500 | $3,100–$4,800 | 2–10% | ↑ 150% (Storm surge + rainfall) | Caloosahatchee River overflow |
| Pinellas | V, A | $4,000 | $3,600–$5,300 | 2–8% | ↑ 130% (Tidal flooding) | Tampa Bay vulnerability |
"The NFIP’s risk rating 2.0 model, implemented in 2021, has increased premiums by 20–50% in high-risk zones to reflect true flood exposure. However, 40% of Florida policyholders remain in subsidized rates, primarily due to grandfathered policies or political resistance to rate hikes."
Demographic and Geographic Trends in NFIP vs. Private Insurance Adoption
The divide between NFIP and private flood insurance in Florida is shaped by economic, geographic, and regulatory factors. NFIP policies are concentrated in older, lower-income households and high-risk coastal properties, while private insurers cater to younger, affluent demographics in moderate-risk zones. Below is a breakdown of key policyholder characteristics and adoption trends.NFIP Policyholder Demographics (Florida-Specific)
Private Insurance Policyholder Demographics
Regulatory and Policy Influences on Florida Flood Insurance
Florida’s flood insurance landscape is shaped by a complex interplay of state regulations, legislative mandates, and financial mechanisms designed to balance risk mitigation with policyholder affordability. The Florida Office of Insurance Regulation (OIR) plays a central role in overseeing compliance, while building codes enforce structural resilience. Meanwhile, financial assessments from the Citizens Property Insurance Corporation (Citizens) directly influence premium structures, creating a dynamic system where policy availability, cost, and risk management are continually recalibrated. Recent legislative actions, such as the Hurricane and Flood Resiliency Act (Senate Bill 76), have further refined these interactions, introducing stricter underwriting standards and incentives for flood-resistant construction.The following sections examine the regulatory framework governing flood insurance, the technical and financial underpinnings of policy requirements, and the legislative updates that redefine accessibility and sustainability in Florida’s flood-prone regions.
Role of the Florida Office of Insurance Regulation (OIR) in Flood Insurance Oversight
The Florida Office of Insurance Regulation (OIR) serves as the primary state agency responsible for regulating flood insurance policies issued by private insurers and the Citizens Property Insurance Corporation. Its authority extends to policy approval, rate filings, market conduct examinations, and enforcement actions to ensure compliance with state and federal laws, including the National Flood Insurance Program (NFIP) standards. The OIR’s oversight is critical in addressing gaps in private market coverage, particularly in high-risk zones where insurers may withdraw due to profitability concerns.Recent rule changes by the OIR have focused on:
The OIR also collaborates with the Florida Catastrophic Storm Risk Management Center (FCSRMC) to analyze flood risk trends and recommend adjustments to regulatory frameworks. For example, post-Hurricane Ian, the OIR issued Emergency Order 2022-104, temporarily suspending certain policy cancellation rules to stabilize the market during recovery efforts.
Impact of Florida Building Codes on Flood Insurance Requirements
Florida’s Florida Building Code (FBC), particularly Chapter 627 (Residential Construction in Coastal High Hazard Areas), integrates floodplain management requirements that directly influence flood insurance eligibility and premiums. The code establishes minimum elevation standards, flood-resistant materials, and structural design criteria to reduce flood damage, thereby lowering long-term insurance costs. Compliance with these codes is often a prerequisite for obtaining flood insurance, especially in Special Flood Hazard Areas (SFHAs) designated by FEMA.Key provisions of the FBC that affect flood insurance include:
- Flood-Resistant Materials and Design:
- Permitting and Inspection:
Example: In Miami-Dade County, where sea-level rise exacerbates flood risks, the county has adopted even stricter local amendments to the FBC, requiring structures in Zone VE (coastal high-hazard areas) to be elevated 2 feet above the BFE by 2025. This proactive measure aims to reduce insurance claims and property damage, aligning with FEMA’s Community Rating System (CRS) incentives for flood mitigation.
Financial Mechanisms: Assessments and Their Effect on Flood Insurance Premiums
Florida’s flood insurance system relies on a multi-layered funding model, where assessments from Citizens Property Insurance Corporation, reinsurance markets, and federal backstop programs collectively determine premium costs. Citizens, the state-run insurer of last resort, plays a pivotal role in stabilizing the market by absorbing high-risk policies that private insurers reject. However, its financial sustainability depends on assessment fees levied on all Florida property insurance policies, which indirectly inflate premiums for flood coverage.Key financial mechanisms include:
- Reinsurance and Federal Backstops:
- Risk-Based Pricing Models:
Table: Financial Impact of Key Mechanisms on Flood Insurance
| Mechanism | Direct Effect on Premiums | Example Scenario |
|---|---|---|
| Citizens Assessments | Increases base policy costs | Post-Ian assessment hike led to +$300/year for a $500k home in Lee County. |
| Risk Rating 2.0 | Higher for high-risk properties | A home in Zone V (coastal) saw premiums rise from $1,200 to $3,500 annually. |
| Mitigation Discounts | Reduces premiums for compliant properties | Elevating a home in Zone A saved $800/year after retrofitting. |
| Reinsurance Shortfalls | May lead to private insurer exits | After Hurricane Michael (2018), some insurers exited Panhandle markets due to reinsurance costs. |
Legislative Updates and Their Direct Effects on Flood Insurance
Recent legislative actions in Florida have sought to address gaps in flood insurance availability, affordability, and resilience. The most impactful measures include Senate Bill 76 (2022), part of the Hurricane and Flood Resiliency Act, which introduced sweeping reforms to flood risk management and insurance markets. Below are key legislative updates and their direct consequences:Senate Bill 76 (2022) – Hurricane and Flood Resiliency Act
Challenges and Gaps in Florida’s Flood Insurance Framework
Florida’s flood insurance system faces persistent structural vulnerabilities, exacerbated by rapid urbanization, climate-induced risks, and regulatory inconsistencies. Despite mandatory purchase requirements under the National Flood Insurance Program (NFIP), significant gaps remain in coverage adoption, affordability, and policy design. These challenges disproportionately affect high-risk properties—including secondary residences, commercial real estate, and low-income households—while insurers grapple with evolving risk models that no longer align with observed climate trends. Addressing these issues requires a multipronged approach targeting compliance enforcement, premium transparency, and adaptive risk assessment frameworks.
Top Three Uninsured Flood Risks in Florida
Florida’s flood insurance market excludes or underinsures approximately 40% of at-risk properties, with secondary homes, commercial properties, and condominiums representing the highest uninsured risks. These gaps stem from voluntary participation in NFIP, misclassification of flood zones, and the absence of mandatory coverage for non-primary residences or businesses in lower-risk areas. Below are the three most critical uninsured risks, supported by data from FEMA’s 2023 Risk Mapping, Assessment, and Planning (Risk MAP) program and Florida’s Office of Insurance Regulation (OIR).
- Secondary Homes and Vacation Properties
Florida’s 1.5 million secondary residences—many located in coastal counties like Brevard, Palm Beach, and Collier—often lack flood insurance due to owner assumptions that primary policies cover all risks or that flood events are improbable. Studies from the Florida Catastrophic Storm Risk Management Center (FCSRMC) indicate that 60% of secondary homes in V-Zones (highest-risk areas) remain uninsured, partly because NFIP does not mandate coverage for non-primary dwellings. Additionally, private insurers frequently exclude flood risks in these properties, leaving owners vulnerable to $100 billion+ in potential losses from a Category 4 hurricane striking Miami or Tampa Bay.- Commercial Properties with Understated Risk Profiles
Commercial real estate, particularly warehouses, retail outlets, and hospitality venues in flood-prone regions (e.g., Miami-Dade’s Redland area, Monroe County’s Keys), often underreport flood exposure to secure lower premiums. The Florida Department of Economic Opportunity (DEO) reports that 35% of commercial properties in Special Flood Hazard Areas (SFHAs) lack NFIP coverage, citing misclassified flood zones or reliance on private flood insurance that excludes business interruption losses. For example, a 2022 study by the R Street Institute found that hotels in Fort Lauderdale faced $2.3 billion in uninsured flood claims during Hurricane Ian, as their policies excluded secondary perils like storm surge or sewer backups.- Condominiums and Multi-Unit Buildings
Condominium associations in Florida frequently fail to maintain master flood policies or distribute coverage equitably among unit owners, leading to systemic gaps. The Florida Condominium Association Act does not mandate flood insurance for associations, and 28% of condos in Miami-Dade lack adequate coverage, per a 2023 analysis by the Urban Land Institute (ULI). High deductibles (often $5,000–$10,000 per unit) and disputes over shared liability further deter participation. During Hurricane Irma (2017), $1.5 billion in condominium flood claims were filed, with 40% denied or underpaid due to policy exclusions or non-compliance with NFIP’s Condominium Building Ordinance (CBO).Key Driver of Non-Compliance:
"The voluntary nature of NFIP for non-primary residences and commercial properties creates a moral hazard, where property owners assume risks they cannot afford to mitigate." — FEMA’s 2023 National Mitigation FrameworkAffordability Crisis in Florida Flood Insurance
Florida’s flood insurance premiums have surged by over 200% since 2017, driven by rising claims, climate risk adjustments, and reinsurance costs. High-premium areas—particularly Miami-Dade, Monroe County, and Pinellas County—experience premiums exceeding $10,000 annually for high-value properties, pricing out homeowners and small businesses. Below is a structured analysis of the affordability crisis, including case studies and mitigation strategies.
- Premium Spikes in High-Risk Counties
Case Study: Miami-Dade
County Average Annual Premium (2024) Key Risk Factors Uninsured Rate Miami-Dade $8,500–$15,000 Sea-level rise (10mm/year), hurricane surge, aging infrastructure 38% Monroe (Keys) $7,200–$12,000 Subsidence, storm surge, limited evacuation routes 42% Pinellas (St. Petersburg) $6,800–$11,000 Urban flooding, tidal flooding, NFIP zone misclassifications 35%
A 2023 report by the Miami Herald highlighted that homeowners in South Miami faced premium increases of 300–500% after FEMA reclassified their properties from Zone X (moderate risk) to Zone V (highest risk) due to updated flood models. The Miami-Dade County Mayor’s Office estimates that 12,000 properties became uninsurable under private markets, forcing reliance on FEMA’s Biggert-Waters Act reforms, which capped premium subsidies.- Mitigation Strategies Reducing Premiums
Florida’s Residential Property Inspections for Mitigation (RPIM) program and Community Rating System (CRS) offer discounts of 5–45% for properties implementing risk-reducing measures. Effective strategies include:
- Elevation and Retrofitting
Properties in Miami-Dade and Monroe County that elevated foundations by 2+ feet above Base Flood Elevation (BFE) saw premium reductions of 20–30%. The Florida Building Code (FBC) 2023 now mandates flood-resistant materials (e.g., waterproof drywall, elevated HVAC systems) in new constructions, reducing long-term claims by 15% (per Florida International University’s Severe Storm Prediction, Education, and Evacuation from Disasters (STORM) lab).- Drainage and Wetland Restoration
Pinellas County’s "Rainwater Solutions" initiative invested $40 million in green infrastructure, including bioretention ponds and permeable pavements, which lowered flood insurance premiums for participating properties by up to 25%. Similar projects in Tampa Bay reduced NFIP claims by 18% between 2020–2023.- Subsidy Programs for Low-Income Households
The Florida Hurricane Catastrophe Fund (FHCF) and NFIP’s Risk Rating 2.0 introduced premium caps for incomes below 80% of the area median, though uptake remains low due to complex application processes. For example, Monroe County’s Low-Income Energy Assistance Program (LIEAP) extended flood insurance subsidies to 500 households, reducing average premiums by $1,200/year.- Economic Barriers to Affordability
Despite mitigation efforts, 30% of Florida homeowners cannot afford flood insurance due to:
- High Deductibles: NFIP policies require $1,000–$10,000 deductibles, which exceed the annual premiums for 40% of condominiums in Fort Lauderdale.
- Lack of
Emerging Trends and Innovations in Flood Insurance
Florida’s flood insurance landscape is undergoing rapid transformation, driven by technological advancements, shifting regulatory priorities, and evolving risk management strategies. Insurers, government agencies, and private innovators are deploying cutting-edge solutions to enhance risk assessment, streamline claims processing, and incentivize proactive flood mitigation. These developments aim to address the limitations of traditional flood insurance models—particularly in high-risk coastal and urban areas—while improving affordability and accessibility for policyholders.The integration of artificial intelligence (AI) and machine learning (ML) has revolutionized flood risk evaluation, enabling insurers to move beyond static flood maps toward dynamic, property-specific risk modeling. Concurrently, parametric insurance products are gaining traction as a faster, more transparent alternative to traditional indemnity-based policies. Additionally, flood mitigation incentives—such as state-funded retrofits and ecosystem-based solutions—are reshaping insurability by reducing exposure and lowering premiums for compliant properties. Below, the key innovations reshaping Florida’s flood insurance ecosystem are examined, including their operational mechanisms, benefits, and real-world applications.
AI and Machine Learning in Flood Risk Assessment
AI and ML are enabling insurers to refine flood risk modeling with unprecedented granularity, moving beyond the limitations of the Federal Emergency Management Agency’s (FEMA) static Flood Insurance Rate Maps (FIRMs). Traditional flood zone designations, which rely on historical data and broad geographic averages, often fail to account for localized vulnerabilities such as drainage system inefficiencies, soil saturation levels, or microclimate variations. Florida insurers, including Citizens Property Insurance Corporation and private carriers like Everglades Insurance Group, are leveraging AI-driven tools to analyze satellite imagery, LiDAR data, and real-time weather patterns to generate hyper-localized flood risk profiles for individual properties or neighborhoods.For example, Insurance Institute for Business & Home Safety (IBHS) collaborates with insurers to deploy Fortified Home standards, which use AI to assess structural resilience against floodwaters. Machine learning algorithms evaluate factors such as foundation elevation, flood venting, and waterproofing materials to assign risk scores that directly influence underwriting decisions. State Farm and Allstate have piloted similar models in Florida, where AI predicts flood depths for specific addresses during storm events, allowing insurers to offer tailored premiums or discounts based on mitigated risk. Additionally, Florida International University’s (FIU) Applied Research Center partners with insurers to integrate hydrodynamic models with ML, simulating flood inundation in real time for high-risk zones like Miami-Dade and Broward counties.
AI-driven flood risk models reduce underwriting uncertainty by up to 40% in urban coastal areas, according to a 2023 study by the Florida Catastrophic Storm Risk Management Center (FCSRMC).Key applications include:
- Predictive Flood Modeling for Individual Properties
AI tools such as Aon’s FloodRe and Verisk’s Hazus-ML combine historical flood data with predictive analytics to estimate a property’s susceptibility to flooding during specific storm scenarios. For instance, a home in Fort Lauderdale with a basement may receive a higher risk score than an elevated structure in Tampa, even if both are in the same FEMA flood zone.- Neighborhood-Level Risk Stratification
Insurers use ML to identify "hotspots" where drainage infrastructure is inadequate, such as Jacksonville’s urban core or Naples’ low-lying barrier islands. These insights inform community-wide mitigation strategies, such as stormwater management upgrades, which can qualify residents for premium discounts.- Dynamic Policy Adjustments
Some insurers, like Lemonade, adjust premiums in real time based on AI-generated risk updates. For example, a policyholder in Miami Beach may see their premium increase temporarily if a tropical storm approaches but decrease if their property’s flood defenses (e.g., elevated doors) are verified through drone inspections.Parametric Flood Insurance in Florida
Parametric insurance represents a paradigm shift from traditional indemnity-based flood policies, where payouts are triggered by predefined, measurable events rather than lengthy damage assessments. In Florida, this model is particularly advantageous given the state’s high frequency of rapid-onset flood events, such as hurricane storm surges or intense rainfall-induced flooding. Unlike NFIP policies, which require proof of loss and can take months to process, parametric policies deliver predefined payouts within days of a qualifying event, such as a storm surge exceeding a specified height or rainfall surpassing a threshold.Florida’s adoption of parametric insurance has accelerated since Hurricane Ian (2022), which exposed the delays and complexities of traditional claims processing. Key players, including Swiss Re, Parametric Insurance Company (PIC), and Florida-based insurer Wawanesa, now offer parametric flood products in collaboration with the state. For example:
- Storm Surge Triggers
Policies may stipulate a payout if a National Hurricane Center (NHC) storm surge forecast exceeds 3 feet for a property’s coastal zone. Miami-Dade County has partnered with parametric insurers to provide $50,000 in automatic coverage for residential properties meeting this criterion, with payouts issued within 72 hours of the event.- Rainfall-Based Triggers
Inland areas prone to flash flooding, such as Orlando’s Kissimmee River basin, may trigger payouts if 24-hour rainfall exceeds 12 inches, as measured by NOAA’s Advanced Hydrologic Prediction Service (AHPS). This approach eliminates the need for post-event damage inspections.- Wind-Flood Combinations
Some parametric policies cover both wind and flood damage under a single trigger, such as a Saffir-Simpson Category 2 hurricane making landfall. Everglades Insurance offers a hybrid parametric product where policyholders receive $25,000 for wind damage and $10,000 for flood damage if the storm meets predefined wind speed and surge thresholds.Parametric flood insurance reduces claims processing time by up to 90% compared to traditional policies, according to a 2023 Florida Department of Financial Services (FDS) report.Advantages over traditional policies include:Challenges remain, however, including limited coverage breadth (typically capping payouts at $50,000–$100,000) and data dependency on accurate trigger measurements. Critics argue that parametric policies may not fully compensate for catastrophic losses, but they serve as a critical supplement to traditional coverage in high-risk regions.
- Speed and Certainty
Payouts are automatic upon meeting trigger conditions, reducing disputes and accelerating recovery for policyholders.- Lower Administrative Costs
Insurers avoid the expense of damage assessments, allowing for 15–30% lower premiums in some cases.- Coverage for Underserved Areas
Parametric policies often extend coverage to NFIP gaps, such as secondary flood zones (A, B, C) where traditional insurers are reluctant to underwrite.- Integration with Government Programs
Florida’s Resilient Florida Grant Program now includes parametric insurance as an eligible mitigation measure, incentivizing local governments to adopt these models.
Flood Mitigation Incentives and Their Impact on Insurability
Florida has become a leader in flood mitigation incentives, offering financial and regulatory incentives to property owners, businesses, and municipalities to reduce flood exposure. These programs—funded by state allocations, FEMA grants, and private-public partnerships—directly influence insurability by lowering risk profiles and qualifying properties for premium discounts, coverage expansions, or NFIP escape clauses. The state’s approach combines structural retrofits, ecosystem restoration, and land-use policies to create a more resilient insurance market.Key mitigation strategies and their insurability impacts include:
- Elevation Retrofits and Floodproofing
Florida’s Flood Mitigation Grant Program provides up to $50,000 per property for elevating homes above the Base Flood Elevation (BFE) or installing flood vents to reduce hydrostatic pressure. Properties that meet FEMA’s Community Rating System (CRS) credits (e.g., Class 5 or higher) may qualify for 10–45% premium discounts with private insurers like State Farm or Geico. For example, Pinellas County offers $10,000 in matching funds for homeowners who elevate their structures, with insurers such as
Practical Steps for Florida Residents to Navigate Flood Insurance
Florida homeowners face unique challenges in securing flood insurance due to the state’s high susceptibility to hurricanes, tropical storms, and rising sea levels. Navigating the National Flood Insurance Program (NFIP) and private market options requires a systematic approach to assess risk, compare coverage, document claims, and address disputes. This section provides actionable guidance for residents to make informed decisions, from evaluating flood exposure using FEMA’s tools to appealing denied claims through Florida’s regulatory framework.
Assessing Flood Risk Using FEMA’s Flood Insurance Rate Maps (FIRMs) and NFIP’s Assistance Tool
Florida’s flood risk varies significantly by location, with coastal and low-lying areas facing higher exposure. The FEMA Flood Insurance Rate Maps (FIRMs) classify properties into high-risk (Special Flood Hazard Areas, or SFHAs) and moderate-to-low-risk zones, determining eligibility for NFIP policies and premium costs. The NFIP’s Flood Insurance Assistance Tool further simplifies risk assessment by providing property-specific flood zone designations, base flood elevations (BFEs), and historical flood data.To assess risk accurately, residents should:
- Locate their property on FEMA’s FIRM database (FEMA Map Service Center) by entering the address or parcel ID. Properties in Zone AE, A, or V (high-risk) require NFIP coverage if mortgaged by a federally regulated lender.
- Use the NFIP’s Flood Insurance Assistance Tool (NFIP Assistance Tool) to generate a Flood Insurance Determination Letter, which outlines mandatory coverage requirements, flood zone classification, and estimated premiums.
- Cross-reference with local floodplain management ordinances, as some Florida counties (e.g., Miami-Dade, Hillsborough) impose stricter building codes or additional flood mitigation requirements for high-risk properties.
- Review historical flood data via FEMA’s Flood Map Service Center or the National Weather Service’s Advanced Hydrologic Prediction Service (AHPS) to identify past flood events affecting the area.
Example: A homeowner in Zone V (coastal high-risk) in Fort Lauderdale may face mandatory NFIP coverage with an annual premium of $1,200–$2,500, depending on the structure’s elevation and flood history. Using the NFIP tool reveals that retrofitting with flood vents or elevated utilities could reduce premiums by 15–30% under the Risk Rating 2.0 model.
Comparing Flood Insurance Quotes: NFIP vs. Private Market
Florida residents have two primary options for flood insurance: the NFIP, administered by FEMA, and private insurers participating in the Private Market Flood Insurance (PMFI) program. Private policies often offer broader coverage but may exclude certain risks or impose higher deductibles. A structured comparison ensures homeowners select the most cost-effective and comprehensive plan.Key factors to evaluate when comparing quotes include:
- Coverage Limits:
- NFIP policies cap building coverage at $250,000 and personal property at $100,000, with optional excess flood coverage available.
- Private insurers may offer higher limits (e.g., $500,000+ for buildings) but exclude certain items (e.g., currency, mold, or land improvements).
- Deductibles:
- NFIP deductibles are percentage-based (1–10% of coverage) or flat amounts ($1,000–$10,000).
- Private policies often use flat deductibles ($2,500–$10,000), which may be more predictable for high-value properties.
- Additional Living Expenses (ALE):
- NFIP provides up to $24,000 for temporary housing, while private insurers may offer $50,000–$100,000+ with broader definitions of "necessary expenses."
- Exclusions and Endorsements:
- NFIP excludes land, currency, and certain business property; private policies may cover electronic data recovery or sump pump failure.
- Optional endorsements (e.g., Loss of Use, Increased Cost of Compliance) vary by insurer and should be compared side-by-side.
- Premium Costs and Discounts:
- NFIP premiums are risk-based under Risk Rating 2.0, with discounts for elevated structures, flood-resistant materials, or community participation in mitigation programs.
- Private insurers may offer bundling discounts (e.g., combining home and flood insurance) or mitigation credits for retrofits like flood doors or backflow valves.
Checklist for Comparing Quotes:
1. Verify flood zone classification (NFIP vs. private insurer’s risk assessment).Example Comparison:
2. Confirm coverage limits for buildings, personal property, and ALE.
3. Compare deductible structures (percentage vs. flat) and their impact on out-of-pocket costs.
4. Review exclusions (e.g., mold, sewer backup) and available endorsements.
5. Assess premium affordability and potential discounts (e.g., mitigation upgrades).
6. Check claims service reputation via J.D. Power ratings or Florida Department of Financial Services (FDS) complaint records.
7. Ensure policy renewal terms align with future risk projections (e.g., sea-level rise).
Factor NFIP Policy Private Insurer (e.g., Lloyd’s, Chubb) Building Coverage $250,000 (standard) $500,000 (with excess coverage option) Deductible 2% of coverage ($5,000) $5,000 flat ALE Coverage $24,000 $75,000 (includes hotel upgrades) Mold Coverage Excluded (unless endorsed) $10,000 sublimit included Premium (Annual) $1,800 $2,200 (with 10% discount for flood vents) Documenting Flood Damage for Insurance Claims
Proper documentation is critical for maximizing claim payouts and avoiding disputes with insurers. Florida’s humid climate and frequent storms accelerate damage, making timely and thorough records essential. A structured approach ensures evidence is admissible and aligns with Florida’s Insurance Code (Fla. Stat. § 627) and NFIP claim requirements.Key elements to document include:
- Photographic and Video Evidence:
- Capture pre-flood conditions (e.g., wall cracks, roof wear) and immediate post-flood damage (e.g., water stains, mold growth).
- Use dated timestamps and wide-angle shots to show extent; include measurement references (e.g., ruler beside waterlines).
- Document hidden damage (e.g., behind walls, under floors) by opening drywall or lifting carpet.
- Repair Estimates and Invoices:
- Obtain written estimates from licensed contractors for structural repairs, mold remediation, and content replacement.
- Retain receipts for temporary fixes (e.g., tarps, sump pumps) if not covered under ALE.
- For personal property, create an itemized inventory with purchase dates, serial numbers, and estimated values (use receipts or appraisals).
- Communication Logs:
- Record dates, times, and summaries of all interactions with insurance adjusters, claims representatives, and contractors.
- Note promises made (e.g., "Adjuster will inspect by Friday") and follow-up actions (e.g., "Sent additional photos on [date]").
- Adjuster’s Report:
- Review the insurance adjuster’s findings for accuracy; dispute undervaluations in writing with supporting evidence.
- Request additional inspections if damage is misclassified (e.g., "cosmetic" vs. "structural").
Template for Documenting Flood Damage:
Property Address: [Insert Address]
Policy Number: [NFIP/Private Policy #]
Date of Flood Event: [MM/DD/YYYY]
Insurance Provider: [NFIP or Private Insurer Name]
Adjuster Assigned: [Name, Contact Info]1. Photographic Evidence
- Exterior Damage:
- [Photo 1] – Water intrusion
Florida’s flood insurance framework stands at a pivotal juncture, where policy reforms, technological advancements, and individual actions converge to address escalating risks. The integration of AI-driven risk modeling, parametric insurance solutions, and flood mitigation incentives offers a pathway to resilience, yet these innovations must be paired with equitable access and transparent regulatory oversight. For residents, the path forward begins with informed decision-making—leveraging tools like FEMA’s Flood Insurance Assistance Tool, comparing insurer offerings, and documenting claims meticulously to bridge coverage gaps. As climate change intensifies flood threats, the collaboration between policymakers, insurers, and communities will determine whether Florida can transform vulnerability into preparedness, ensuring that no property—or life—is left unprotected in the face of rising waters.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.