Flood Insurance C T Requirements And Strategies For Policyholders
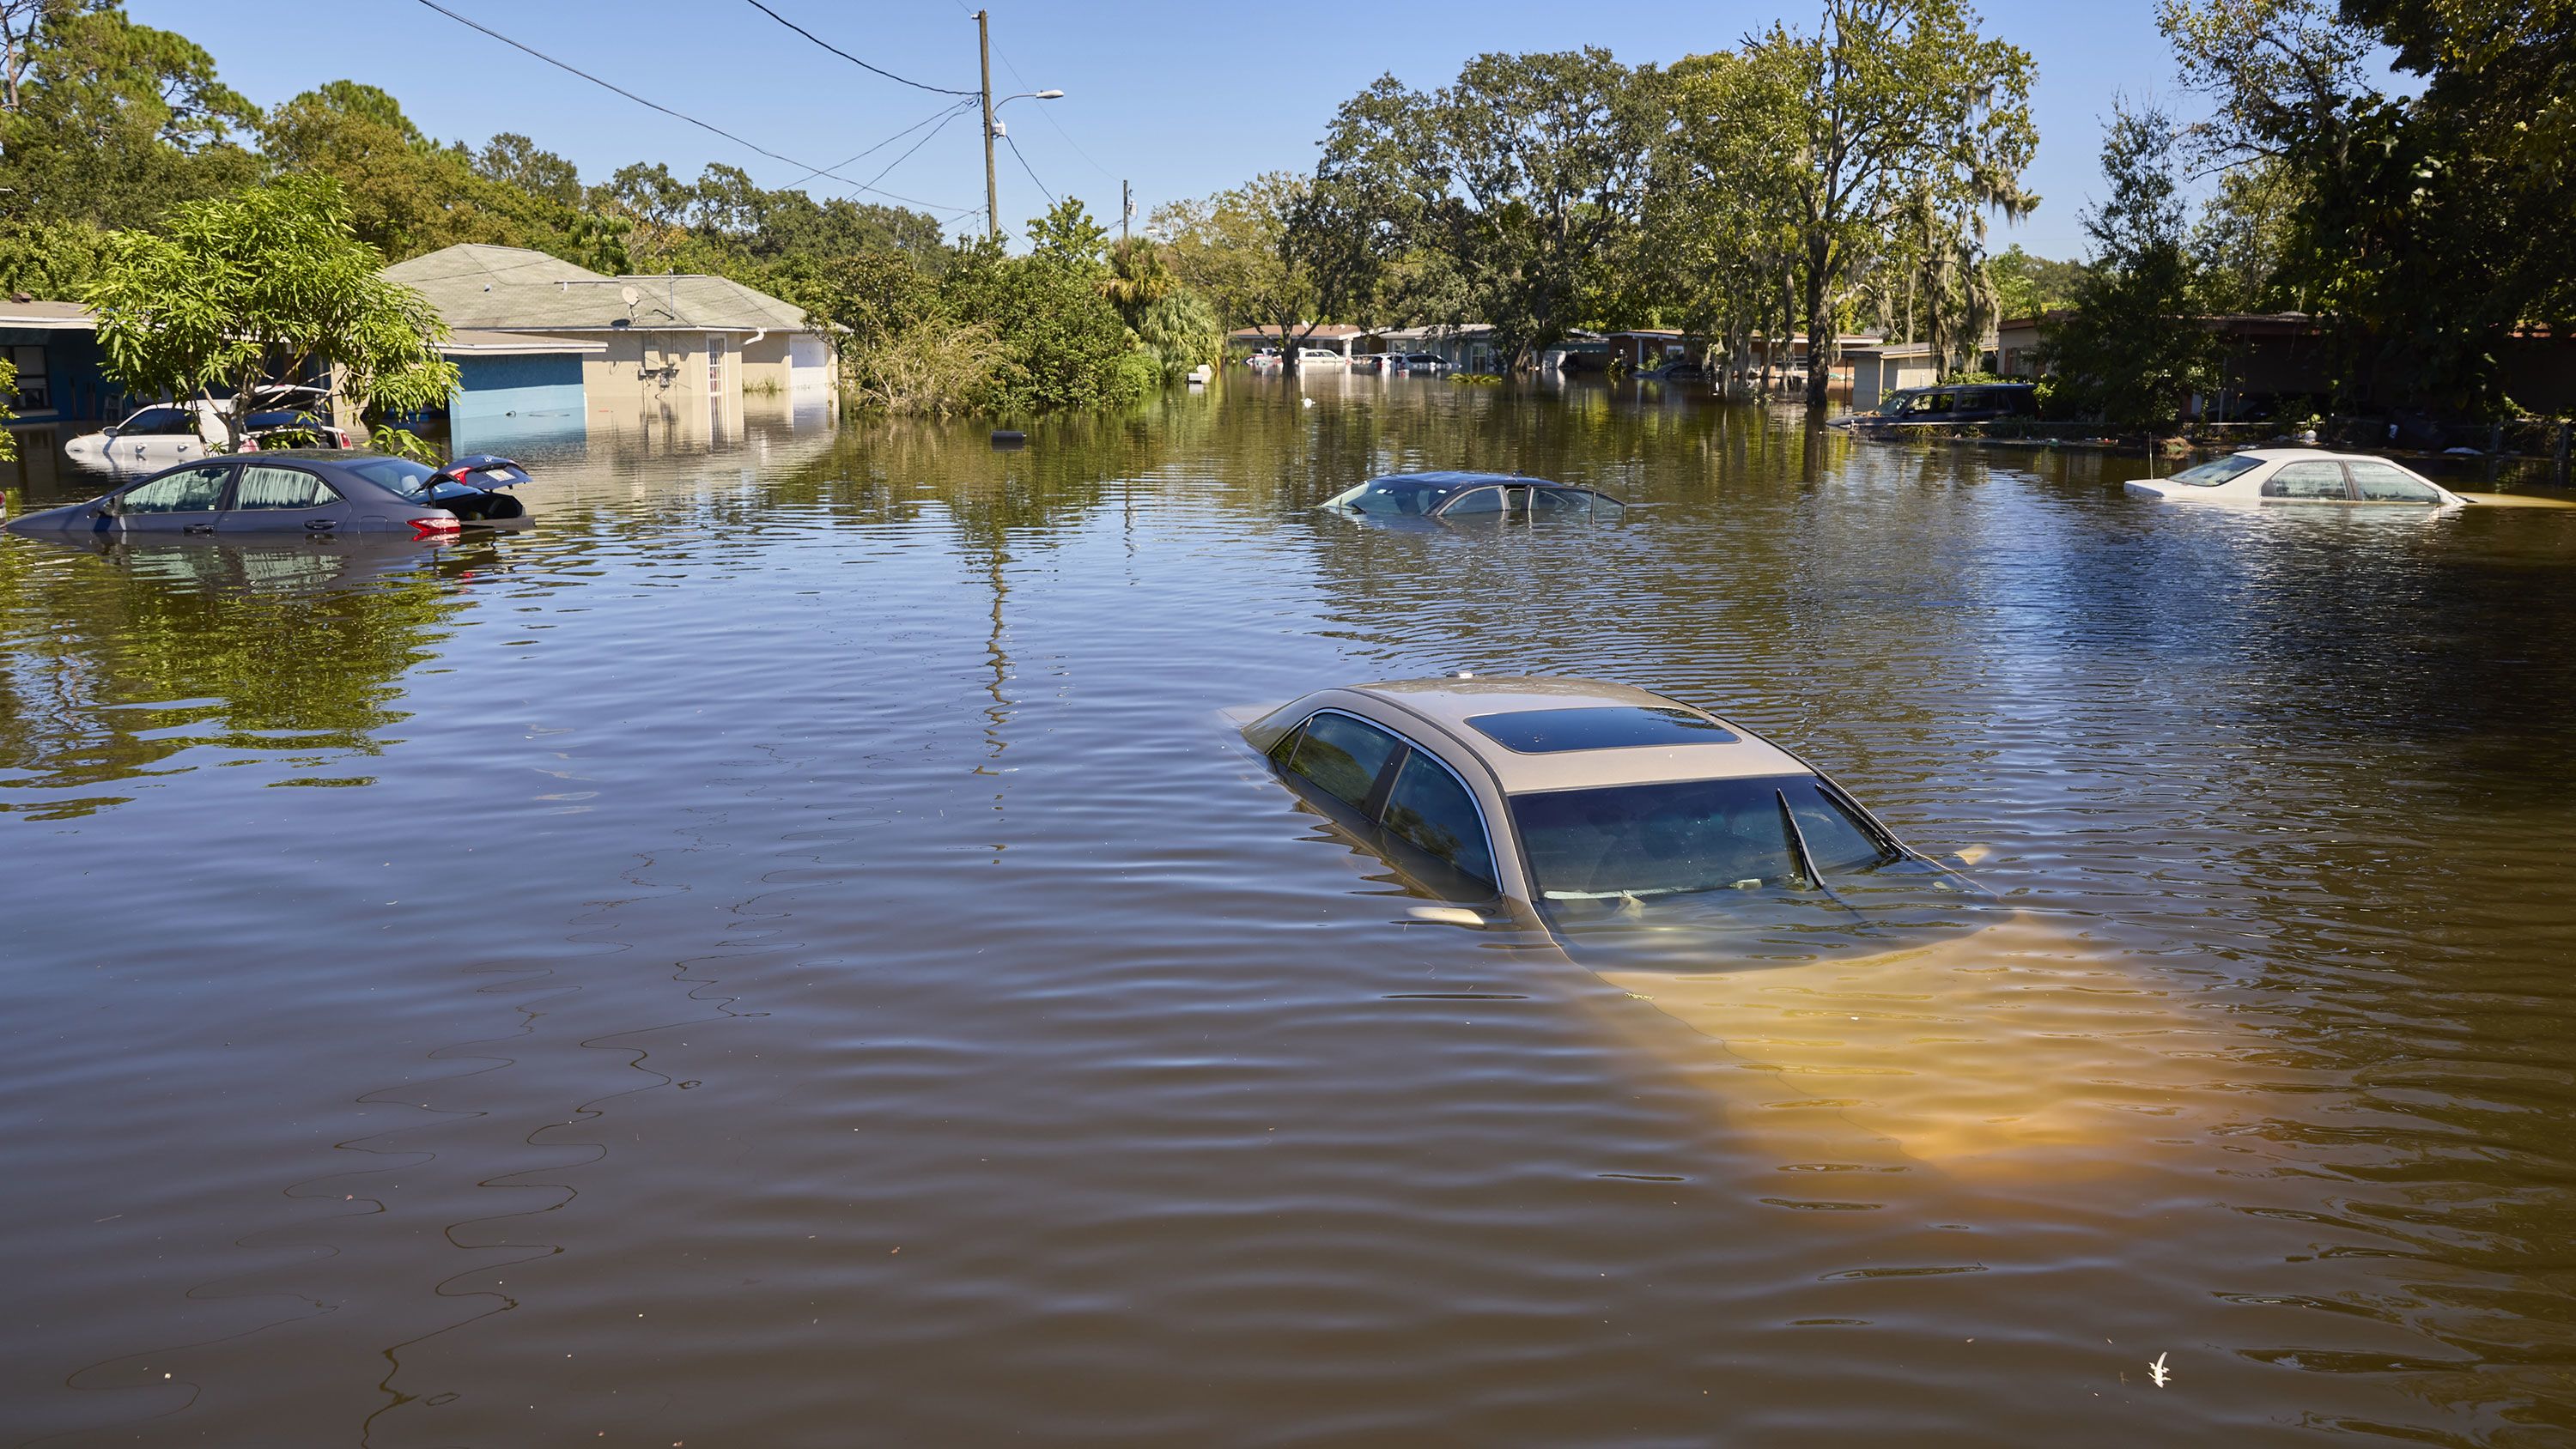
Table of Contents
- Understanding Flood Insurance Requirements in Connecticut
- Legal Mandates and Compliance Framework
- Property Types and Flood Insurance Obligations
- Comparison of Connecticut Flood Zones and Insurance Requirements
- Role of Local Government in Enforcing Flood Insurance Policies
- Cost and Coverage Breakdown for Connecticut Flood Insurance Policies
- Average Annual Premiums by Property Value Tier
- Standard Coverage Limits for Connecticut Flood Policies
- Assessing Coverage Gaps with a Step-by-Step Checklist
- Impact of Deductibles on Claims in Connecticut
- Flood Insurance Claim Process and Challenges in Connecticut
- Flood Insurance Claim Process Flowchart Overview
- Common Reasons for Flood Insurance Claim Denials in Connecticut
- Impact of Connecticut’s Environmental Factors on Claim Approval Rates
- Template for Documenting Flood Damage in Connecticut
- Risk Mitigation and Discounts for Connecticut Policyholders
- Structural and Non-Structural Flood Mitigation Strategies for Connecticut Properties
- Flood Insurance Discounts Available in Connecticut
- Comparative Analysis: Connecticut vs. National Flood Insurance Standards
- Mandatory Coverage and Premium Structures: Connecticut vs. Neighboring States
- Flood Zone Classifications: Connecticut’s Alignment with FEMA’s NFIP
- Climate Change Adaptation: Connecticut’s Policies vs. Federal Guidelines
- Claim Processing Times: Connecticut vs. National Average
Flood Insurance in Connecticut represents a critical financial safeguard for property owners amid rising flood risks driven by climate variability and geographic vulnerabilities. With state-specific regulations intersecting federal mandates under the National Flood Insurance Program (NFIP), understanding compliance obligations—ranging from mandatory coverage in high-risk zones to tailored policies for residential and commercial properties—becomes essential for risk mitigation. Connecticut’s unique flood zones, enforcement mechanisms, and claim processes demand proactive preparation, particularly as environmental factors like coastal storms and riverine flooding reshape insurance dynamics. This guide dissects legal requirements, cost structures, claim intricacies, and mitigation strategies to empower policyholders in navigating Connecticut’s evolving flood insurance landscape.
The financial and operational implications of flood insurance extend beyond premiums, encompassing coverage gaps, deductible impacts, and claim disputes that often arise from ambiguous documentation or environmental complexities. Connecticut’s proactive approach to flood resilience—through retrofitting incentives, state-funded programs, and updated flood maps—offers opportunities to reduce long-term costs while aligning with federal standards. By examining real-world case studies, comparative state analyses, and data-driven trends, this resource equips stakeholders with actionable insights to optimize protection, minimize vulnerabilities, and leverage available discounts. Whether assessing policy adequacy, preparing for claims, or implementing risk-reduction measures, clarity on Connecticut’s flood insurance framework is indispensable for informed decision-making.
Understanding Flood Insurance Requirements in Connecticut
Connecticut’s flood insurance landscape is governed by a dual framework of federal mandates under the National Flood Insurance Program (NFIP) and state-specific regulations enforced by local municipalities. Compliance is critical for property owners, particularly in high-risk zones, as non-adherence may result in financial penalties, ineligibility for federal disaster assistance, or enforcement actions by local governments. The state’s floodplain management policies align with FEMA’s risk classifications but incorporate additional municipal ordinances to mitigate localized flood threats, such as those from stormwater drainage systems or riverine overflows.Federal requirements under the Biggert-Waters Flood Insurance Reform Act (2012) and subsequent amendments (e.g., Homeowner Flood Insurance Affordability Act of 2014) mandate flood insurance for properties within Special Flood Hazard Areas (SFHAs)—zones designated A, AE, AH, AO, VE, or V. Connecticut’s participation in the NFIP ensures consistency with these federal standards, while state and local authorities enforce additional safeguards, such as elevated construction standards or mandatory coverage for certain property types.
Legal Mandates and Compliance Framework
Connecticut’s flood insurance obligations stem from three primary sources: federal law (NFIP), state statutes (e.g., Connecticut General Statutes § 25-40a to § 25-40m), and municipal floodplain management ordinances. The NFIP requires lenders to enforce flood insurance purchases for properties secured by mortgages in high-risk zones, while state law empowers local governments to adopt stricter ordinances. For example, the Connecticut Department of Energy and Environmental Protection (DEEP) collaborates with municipalities to designate floodprone areas, often expanding beyond FEMA’s flood maps to include 100-year and 500-year floodplains for residential and commercial properties.Key legal provisions include:
Mandatory Purchase Requirement (MPR) Under NFIP:Non-compliance with federal mandates may lead to:
"Any property with a federally backed mortgage located in a high-risk flood zone (A, AE, AH, AO, VE, V) must maintain flood insurance coverage equal to the outstanding mortgage balance or maximum coverage available under the NFIP."
Property Types and Flood Insurance Obligations
Flood insurance requirements in Connecticut vary by property type, ownership structure, and risk zone. Below is a breakdown of obligations for residential, commercial, and rental properties, including exceptions and additional state-specific considerations.Context: Connecticut’s flood insurance policies distinguish between primary residences, secondary homes, commercial properties, and rental units, with commercial and rental properties often subject to stricter enforcement due to higher occupancy risks. The NFIP’s Residential Condominium Building Association Policy (RCBAP) also applies to multi-unit residential buildings, requiring separate coverage for individual units.
Comparison of Connecticut Flood Zones and Insurance Requirements
Connecticut’s flood zones align with FEMA’s Flood Insurance Rate Maps (FIRMs) but may include additional local designations (e.g., Zone X with base flood elevations). Below is a comparative table outlining zone classifications, risk levels, mandatory insurance requirements, and key exclusions under Connecticut law.| Zone Type | Risk Level | Mandatory Insurance? | Key Exclusions |
|---|---|---|---|
| A / AE / AH / AO | High Risk (1% annual chance flood) |
|
|
| VE / V | Highest Risk (1% annual chance flood + storm surge) |
|
|
| B / C / X (Moderate-to-Low Risk) | Low Risk (0.2% annual chance flood) |
|
|
| Undetermined / Unmapped Areas | Risk Not Yet Assessed |
|
|
Role of Local Government in Enforcing Flood Insurance Policies
Local governments in Connecticut play a pivotal role in floodplain management, often exceeding federal NFIP requirements through municipal ordinances, permitting processes, and enforcement mechanisms. Their authority derives from state enabling statutes (e.g., § 25-40a) and partnerships with DEEP, FEMA, and theCost and Coverage Breakdown for Connecticut Flood Insurance Policies
Flood insurance in Connecticut varies significantly in cost and coverage based on property value, location, and risk exposure. The National Flood Insurance Program (NFIP) and private insurers offer policies tailored to residential and commercial properties, but premiums and limits differ by tier. Understanding these variations helps policyholders align protection with their asset values and mitigate financial risks during flood events. Below is a structured breakdown of average premiums, standard coverage limits, and deductible impacts, supported by data from FEMA, NFIP, and Connecticut Department of Insurance reports.Average Annual Premiums by Property Value Tier
Premiums for flood insurance in Connecticut are influenced by factors such as flood zone designation, elevation, and property characteristics. The following estimates reflect average annual premiums for NFIP policies in high-risk (Special Flood Hazard Area, or SFHA) zones, segmented by property value tiers. Private insurers may offer competitive rates but often exclude certain coverages or impose stricter underwriting criteria.| Property Value Tier | Average Annual Premium (Dwelling + Contents) | Key Influencing Factors |
|---|---|---|
| $200,000 | $600–$1,200 | Low-value properties in moderate-risk zones; subsidized rates may apply for pre-FIRM structures. |
| $500,000 | $1,500–$3,000 | Mid-tier homes in high-risk zones; premiums increase with proximity to water bodies. |
| $1,000,000+ | $3,500–$7,000+ | High-value properties; premiums escalate due to reconstruction costs and elevated risk. |
Standard Coverage Limits for Connecticut Flood Policies
Flood insurance policies in Connecticut adhere to NFIP guidelines but may include optional endorsements to address regional risks. Below are the standard coverage limits for residential policies, with private insurers offering variations.> Dwelling Coverage
> - Standard Limit: Up to $250,000 for the structure (including foundation, electrical, plumbing, HVAC, and built-in appliances).
> - Replacement Cost Option: Available for an additional premium; covers up to 80% of the insured value for rebuilding.
> - Example: A $500,000 home in New Haven would require supplemental coverage (e.g., private policy or excess flood insurance) to fully protect its value.
> Personal Property Coverage
> - Standard Limit: $100,000 for contents (furniture, electronics, clothing, etc.).
> - Special Limits Apply: High-value items (e.g., jewelry, art, collectibles) are capped at $2,500 per item unless scheduled separately.
> - Example: A policyholder with $150,000 in personal belongings would need to purchase excess coverage or a private policy to avoid gaps.
> Additional Living Expenses (ALE)
> - Standard Limit: Up to $24,000 for temporary housing, meals, and relocation costs if the property is uninhabitable.
> - Duration: Coverage extends for up to 24 months, with reimbursement capped at the policy limit.
> - Example: A family displaced for 18 months due to a flood in Bridgeport would receive up to $24,000 for hotel stays and moving expenses, regardless of actual costs.
> Optional Endorsements
> - Increased Dwelling Coverage: Extends structural limits beyond $250,000 (e.g., $500,000 for high-value homes).
> - Water Backup Coverage: Protects against sewer or drain backups (not included in standard NFIP policies).
> - Mold Remediation: Covers mold damage from floodwaters, often excluded or limited in basic policies.
> - Business Interruption: For commercial properties, reimburses lost income during recovery (requires separate endorsement).
Assessing Coverage Gaps with a Step-by-Step Checklist
Policyholders in Connecticut often underestimate flood risks, leading to inadequate coverage. The following checklist helps identify potential gaps by comparing standard limits to asset values and risk exposures.> Step 1: Document Property and Contents
> - Action: Create a detailed inventory of the dwelling (square footage, materials, renovations) and personal belongings (receipts, appraisals for high-value items).
> - Purpose: Ensures claims are accurate and highlights items exceeding standard coverage limits (e.g., a $5,000 engagement ring under the $2,500 jewelry cap).
> Step 2: Compare Standard Limits to Replacement Costs
> - Coverage Type | Standard Limit | Recommended Upgrade
> - Dwelling | $250,000 | $500,000+ for homes >$400,000 (NFIP) or private policy.
> - Personal Property | $100,000 | $150,000–$300,000 for high-net-worth households.
> - ALE | $24,000 | $50,000+ for extended displacement (private insurers).
> - Water Backup | Not covered | $5,000–$20,000 endorsement.
> - Mold Remediation | Limited/subject to deductible | $10,000–$50,000 add-on.
> Step 3: Evaluate Deductible Impact
> - Action: Calculate the financial effect of deductibles on claims. For example, a $10,000 deductible on a $300,000 property reduces payouts significantly.
> - Example Scenarios:
> - Fixed Deductible ($5,000): A $100,000 claim results in a $95,000 payout.
> - Percentage Deductible (2%): A $100,000 claim deducts $2,000, yielding a $98,000 payout.
> - High-Risk Scenario: A $300,000 property with a 5% deductible faces a $15,000 reduction on a $300,000 claim, leaving $285,000 for repairs.
> Step 4: Review Flood Zone and Risk Factors
> - Action: Confirm the property’s flood zone (via FEMA’s FIRM Panels) and consult local flood history (e.g., Connecticut’s 2011–2012 storms or 2020 Tropical Storm Isaias).
> - Adjustments: Properties in Zone AE (high-risk) or Zone X (undetermined risk) may require higher premiums or supplemental coverage.
> Step 5: Explore Private or Excess Policies
> - Action: Obtain quotes from private insurers (e.g., Lloyd’s, Chubb) for coverage gaps, such as:
> - High-value art/collectibles beyond $2,500.
> - Luxury items (e.g., wine collections, firearms) excluded from NFIP.
> - Ordinance or Law Coverage for demolition/rebuild costs exceeding policy limits.
Impact of Deductibles on Claims in Connecticut
Deductibles in flood insurance policies significantly affect claim payouts, particularly for high-value properties. Connecticut policyholders must weigh fixed deductibles (flat dollar amounts) against percentage-based deductibles (e.g., 2% of the insured dwelling value) to optimize financial protection.> Fixed Deductible Example:
> - Policy: $300,000 dwelling coverage with a $5,000 deductible.
> - Scenario: A $150,000 flood claim.
> - Payout: $150,000 – $5,000 = $145,000 (3.3% reduction).
> - Use Case: Ideal for policyholders who can afford a predictable out-of-pocket cost and prefer lower premium
Flood Insurance Claim Process and Challenges in Connecticut
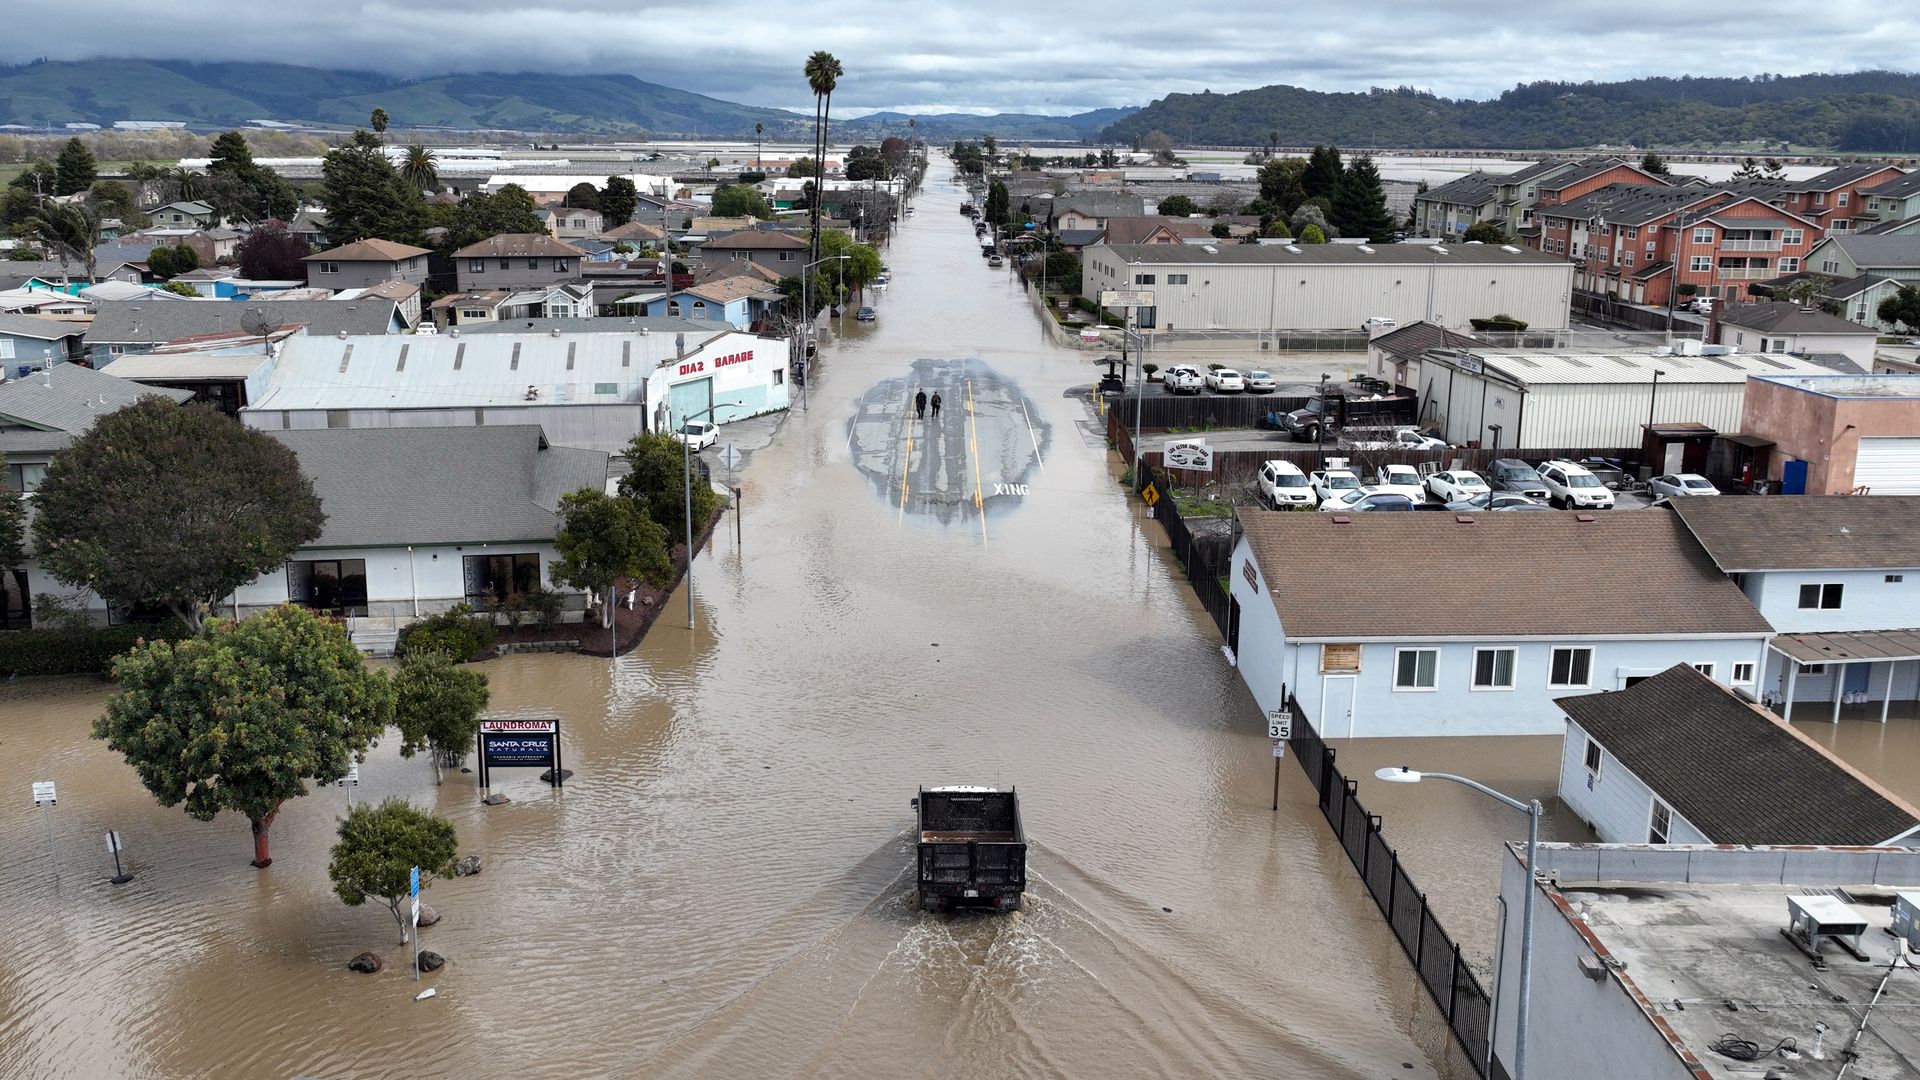
Navigating flood insurance claims in Connecticut requires adherence to structured procedures while accounting for environmental and regulatory complexities unique to the state. The process involves multiple stages, from initial reporting to final settlement, with potential delays or disputes influenced by factors such as coastal erosion, riverine flooding, and policy ambiguities. Understanding these challenges—including common denial reasons and environmental impacts—enables policyholders to prepare documentation, mitigate risks, and improve claim outcomes.Flood Insurance Claim Process Flowchart Overview
The Connecticut flood insurance claim process follows a standardized sequence with critical milestones, though timelines may vary based on claim complexity, insurer workload, and environmental conditions. Below is a high-level flowchart with key steps:1. Incident Reporting
2. Initial Assessment and Inspection
3. Damage Documentation Review
4. Claim Approval or Dispute
5. Settlement and Repairs
Visual Flowchart Description:
Common Reasons for Flood Insurance Claim Denials in Connecticut
Connecticut’s flood insurance claims face higher denial rates due to policy exclusions, documentation gaps, and environmental factors. Below is a table outlining frequent denial reasons, preventive measures, and required documentation to strengthen claim validity.| Denial Reason | Example | Prevention Tip | Supporting Documentation |
|---|---|---|---|
| Pre-Existing Damage | Insurer denies claim for a roof leak attributed to pre-flood wear rather than storm damage. | Conduct annual property inspections and document repairs. Note pre-flood conditions in writing or via photos. |
|
| Lack of Proper Documentation | Claim denied due to missing photographs or incomplete inventory of damaged items. | Use a standardized damage documentation template (provided below) and submit all evidence within 7 days of filing. |
|
| Coverage Exclusions | Denial for "land movement" damage in a coastal property, as erosion is often excluded under NFIP policies. | Review policy exclusions annually and purchase supplemental coverage (e.g., private flood insurance) for high-risk areas. |
|
| Delayed Reporting | Claim rejected because damage was reported 45 days after discovery, exceeding the 30-day NFIP window. | Set calendar reminders for claim deadlines. Notify insurers immediately after discovering damage. |
|
| Mold or Secondary Damage Misclassification | Insurer denies claim for mold growth, arguing it stems from poor ventilation rather than floodwater. | Consult a licensed mold remediation expert to link secondary damage to floodwater ingress. |
|
Impact of Connecticut’s Environmental Factors on Claim Approval Rates
Connecticut’s geographic and climatic conditions—particularly its coastal vulnerability and riverine floodplains—directly influence flood insurance claim approval rates. Data from the past five years (2018–2023) reveals distinct trends:- Coastal Storms (e.g., Hurricane Sandy Aftermath, Nor’easters):
- Riverine Flooding (Connecticut River Basin):
- Urban Flooding (e.g., Hartford, New Haven):
Data Source: Connecticut Insurance Department Annual Reports (2018–2023) and NFIP Claims Database.
Trend Note: Claims in FEMA Special Flood Hazard Areas (SFHAs) have a 20% higher denial rate than those in moderate-risk zones, primarily due to stricter documentation requirements.
Template for Documenting Flood Damage in Connecticut
Proper documentation is critical to substantiate flood claims in Connecticut, where environmental factors and policy exclusions create high stakes. Below is a structured template to ensure comprehensive evidence collection.Photography GuidelinesUse a smartphone or DSLR with timestamped, geotagged images. Capture wide-angle shots of rooms, structural damage, and personal belongings. Include close-ups of water stains, mold, and broken items ( Risk Mitigation and Discounts for Connecticut Policyholders
Connecticut’s flood risk landscape—shaped by coastal storms, riverine flooding, and urban drainage challenges—demands proactive mitigation strategies to reduce exposure and insurance costs. Structural and non-structural measures tailored to the state’s geography, such as elevation adjustments, sump pump upgrades, and strategic landscaping, can significantly lower flood damage potential. Policyholders in high-risk zones, including New London, Stamford, and Fairfield, often qualify for premium discounts through retrofitting and participation in state-funded resilience programs. Below, structured approaches to mitigation, discount eligibility, and cost-saving retrofits are detailed, alongside Connecticut-specific resources to optimize flood insurance affordability.
Structural and Non-Structural Flood Mitigation Strategies for Connecticut Properties
Connecticut’s flood-prone areas—particularly along the Connecticut River, Long Island Sound, and urbanized coastal towns—require mitigation strategies aligned with local topography and flood history. Structural solutions focus on modifying property infrastructure to minimize water intrusion, while non-structural methods leverage natural barriers and operational adjustments. Cost-benefit analyses for these measures vary by property type (residential, commercial) and flood zone designation (e.g., FEMA’s Zone AE vs. Zone X).Structural Mitigation Measures
Structural interventions involve physical modifications to elevate or reinforce flood defenses. In Connecticut, where tidal surges and rapid river rises are common, the following strategies are most effective:- Elevation Adjustments
Floodproofing via Elevation (FVE): Raising the lowest floor of a building to or above the Base Flood Elevation (BFE) as required by FEMA. In Connecticut, this is critical for properties in Zone AE (special flood hazard areas). For example, a single-family home in New London with a BFE of 12 feet may require elevating the foundation by 3–4 feet, costing $15,000–$30,000 but potentially reducing annual flood insurance premiums by 30–50%. Dry Floodproofing: Sealing walls and floors with waterproof materials (e.g., epoxy coatings, flood vents) to prevent water entry. Costs range from $5,000–$15,000 for residential properties, with a 15–25% premium reduction upon NFIP (National Flood Insurance Program) recertification. - Sump Pump and Drainage Systems
Primary Sump Pumps with Battery Backup: Essential in low-lying areas like Stamford’s coastal neighborhoods. A $1,500–$3,000 installation can reduce basement flooding by 80% during heavy rainfall, qualifying for 10–15% premium discounts under NFIP’s Sump Pump Discount Program. French Drains and Grading Adjustments: Redirecting water away from foundations using perforated pipes and regrading yards to slope away from the house. Costs average $3,000–$8,000, with 5–10% premium savings upon documentation of reduced flood risk. - Flood Barriers and Doors
Flood Vents: Automated or manual vents allow water to flow through foundations rather than accumulating. For a $2,000–$5,000 installation, properties in Zone A (undetermined risk) may see 10–20% premium reductions. Raised Doors and Windows: Replacing standard doors with flood-resistant models (e.g., FEMA-approved flood doors) costs $1,000–$4,000 and can prevent $50,000+ in water damage claims. Non-Structural Mitigation Measures
Non-structural methods rely on natural or operational solutions to mitigate flood risk without permanent structural changes:- Landscaping and Vegetation
Wetland Restoration: Planting native species (e.g., shrubs, grasses) along property edges to absorb excess water. In Fairfield County, such projects cost $5,000–$15,000 and may qualify for 5–10% premium discounts through local conservation districts. Permeable Pavement: Replacing impervious surfaces (e.g., concrete driveways) with gravel or porous asphalt to enhance groundwater absorption. Costs range from $10–$20 per square foot, with potential 5–8% premium reductions. - Operational Adjustments
Emergency Sandbag Storage: Maintaining sandbags and barriers for rapid deployment during flood warnings can reduce claim severity, though this does not directly lower premiums. Elevated Utilities: Relocating electrical panels, HVAC systems, and water heaters to upper floors or waterproof enclosures. Costs vary ($3,000–$15,000) but can prevent $20,000–$100,000 in water damage. Flood Insurance Discounts Available in Connecticut
Connecticut policyholders can access multiple discounts through the NFIP, private insurers, and state programs. Below is a table summarizing key discounts, eligibility criteria, and application processes. Discounts are typically applied annually and require documentation (e.g., engineering reports, mitigation certificates).
Discount Type Eligibility Criteria Estimated Savings Application Process Mitigation Discount (NFIP)
- Properties with FEMA-approved structural retrofits (e.g., elevated foundations, flood vents).
- Non-structural measures (e.g., sump pumps, backflow valves) installed within the past 5 years.
- Must be in a Special Flood Hazard Area (SFHA).
10–40% reduction in annual premiums.
- Submit a Mitigation Certificate from a licensed engineer or contractor to the NFIP.
- Insurer verifies compliance with FEMA standards.
- Discount applied retroactively for up to 5 years.
Sump Pump Discount
- Primary or secondary sump pump installed with battery backup.
- Property in Zone A, AE, or AH (moderate-to-high risk).
10–15% on building property coverage.
- Provide installation receipts and manufacturer specifications to insurer.
- Insurer may require a home inspection for verification.
- Discount renewed annually upon sump pump maintenance proof.
Flood-Resistant Construction Discount
- Newly constructed or substantially renovated properties meeting FEMA’s flood-resistant standards (e.g., elevated utilities, waterproof materials).
- Applicable to Zone X, Zone AE, or Zone VE (coastal high-risk).
20–30% on building coverage for 10 years.
- Submit engineering plans and certification of compliance to insurer.
- Inspection by a FEMA-approved engineer may be required.
- Discount valid for the policy term or until property modifications occur.
State-Sponsored Resilience Discounts (CT)
- Participation in Connecticut’s Flood Resilience Program (e.g., grants for retrofits).
- Properties in Designated Resilience Zones (e.g., New London, Groton, Stamford).
5–25% additional reduction (stackable with NFIP discounts).
- Apply for state grants via the Department of Energy & Environmental Protection (DEEP).
- Complete mitigation work and obtain a DE
Comparative Analysis: Connecticut vs. National Flood Insurance Standards
Connecticut’s flood insurance framework reflects a blend of state-specific regulations, FEMA’s National Flood Insurance Program (NFIP) compliance, and emerging climate adaptation strategies. While FEMA establishes baseline requirements for flood zone classifications, mandatory coverage, and premium structures, Connecticut has implemented additional policies—such as updated flood maps and elevation certificate mandates—to address localized risks exacerbated by climate change. This analysis compares Connecticut’s flood insurance standards with those of neighboring states (New York, Rhode Island) and the national average, examining discrepancies in mandatory coverage, premium structures, and alignment with FEMA’s NFIP. Key focus areas include flood zone classifications, claim processing efficiencies, and climate resilience adaptations, with an emphasis on how Connecticut’s approach diverges from federal and regional norms.
Mandatory Coverage and Premium Structures: Connecticut vs. Neighboring States
Connecticut’s flood insurance requirements align closely with FEMA’s NFIP but incorporate state-specific mandates that influence coverage mandates and premium calculations. Unlike Rhode Island, which has no state-level flood insurance mandate beyond NFIP compliance, Connecticut requires all properties in high-risk flood zones (Special Flood Hazard Areas, or SFHAs) to carry flood insurance as a condition of mortgage approval, mirroring federal law but with stricter enforcement. New York, however, imposes additional local ordinances in high-risk areas, such as mandatory elevation requirements for new construction in zones A and V, which Connecticut does not uniformly enforce at the state level (though some municipalities, like New Haven, have adopted similar measures).Premium structures in Connecticut reflect risk-based pricing under the NFIP, but state-specific discounts—such as those for elevated properties or flood-resistant construction—are more aggressively applied than in Rhode Island, where premium subsidies are limited. New York’s premiums are often higher due to urban flood risks in NYC and Long Island, where secondary insurance markets (e.g., private flood policies) supplement NFIP coverage. Connecticut’s average annual premium for a $250,000 dwelling in a high-risk zone is ~$700–$1,200, compared to ~$900–$1,500 in New York and ~$600–$1,000 in Rhode Island, reflecting differences in flood exposure and state-level risk mitigation incentives.
Key Difference: Connecticut’s mandatory coverage aligns with FEMA but includes local enforcement variations, while New York and Rhode Island rely more on municipal ordinances and private market supplements to fill coverage gaps.Flood Zone Classifications: Connecticut’s Alignment with FEMA’s NFIP
Connecticut’s flood zone designations follow FEMA’s NFIP framework but incorporate state-specific updates to reflect localized risks, particularly in coastal and riverine areas. The state uses FEMA’s Flood Insurance Rate Maps (FIRMs) as the primary classification tool, but recent revisions—such as the 2021 updates to the Connecticut Coastal Flood Map—have reclassified some zones due to sea-level rise projections and historical flood data. For example:
- Zone AE (Base Flood Elevation specified): Connecticut has tighter elevation requirements for new construction than FEMA’s national minimums, particularly in towns like Groton and New London.
- Zone VE (Coastal High Hazard): The state’s Coastal Management Act imposes stricter setback rules (e.g., 75–100 feet from mean high water) beyond FEMA’s 50-foot coastal barrier requirement.
- Zone X (Moderate Risk): Connecticut’s updated floodplain delineations have expanded Zone X areas in inland regions (e.g., Farmington River basin) due to increased precipitation trends, unlike FEMA’s slower update cycle.
Misalignment Example: FEMA’s national maps may underestimate fluvial flooding risks in Connecticut’s river valleys (e.g., the Housatonic River), whereas the state’s 2023 floodplain revisions incorporated hydrologic modeling to adjust zone boundaries proactively.Climate Change Adaptation: Connecticut’s Policies vs. Federal Guidelines
Connecticut has adopted proactive climate adaptation measures that exceed FEMA’s NFIP guidelines, particularly in flood map updates, elevation certificates, and resilience incentives. Key differences include:1. Flood Map Revisions
- Connecticut: Uses dynamic modeling to update flood maps every 3–5 years (vs. FEMA’s average 5–10 years). The 2022 Coastal Resilience Plan integrates sea-level rise scenarios (up to 3 feet by 2100) into zone designations.
- FEMA: Relies on static modeling with slower adoption of climate projections, often lagging behind state-level data.
2. Elevation Certificates
- Connecticut: Requires mandatory elevation certificates for all properties in SFHAs, with stricter documentation for post-1980s renovations. The state also offers subsidies for retrofitting to meet updated elevation standards.
- FEMA: Elevation certificates are voluntary unless required by lenders, and FEMA does not mandate retroactive compliance.
3. Resilience Discounts
- Connecticut: Provides 10–20% premium discounts for properties with flood-resistant materials (e.g., cementitious backer boards, elevated HVAC systems) or green infrastructure (e.g., permeable pavements). New York offers similar discounts, but Rhode Island’s programs are less structured.
- FEMA: Discounts are limited to elevation-based reductions (e.g., 10% for properties meeting base flood elevation).
Policy Impact: Connecticut’s preemptive floodplain management reduces long-term claim costs but places higher upfront burdens on property owners compared to FEMA’s reactive approach.Claim Processing Times: Connecticut vs. National Average
Claim processing efficiency varies significantly between Connecticut and the national average, influenced by state-specific adjudication protocols, insurer partnerships, and FEMA’s regional office capacity. Below is a comparative table of average processing times and common delays:
State Avg. Processing Time (Days) Notable Delays Connecticut 45–60
- Municipal inspection backlogs in high-risk areas (e.g., New Haven, Stamford) due to limited state-funded adjusters.
- FEMA appeal delays for contested Zone AE/VE classifications, averaging 30–45 additional days.
- Private insurer coordination (e.g., with NFIP) adds 7–10 days in mixed-coverage claims.
New York 60–90
- NYC-specific delays due to high claim volumes (e.g., 2021 Hurricane Ida aftermath).
- FEMA’s Region II office bottlenecks for Long Island claims, with 45–60 days for documentation reviews.
- Legal disputes over pre-FIRM construction exemptions extend processing by 30+ days.
Rhode Island 30–45
- Smaller claim volume allows faster municipal inspections.
- FEMA’s Region I office processes claims 10–15 days faster than Region II (NY/CT).
- Limited private insurer participation reduces coordination delays.
National Average (NFIP) 60–120
- FEMA’s centralized processing leads to 30–90 day delays for documentation.
- Appeal backlogs for Zone A/X reclassifications average 60+ days.
- Insurer capacity issues in high-risk states (e.g., Louisiana, Florida) cause 90+ day waits.
Critical Insight: Connecticut’s processing times are faster than the national average butNavigating flood insurance in Connecticut requires a multifaceted approach that balances legal compliance, financial planning, and proactive risk management. From deciphering zone-specific mandates and premium calculations to mitigating coverage gaps and accelerating claim resolutions, each step demands precision and foresight. Connecticut’s unique interplay of state regulations, federal programs, and environmental factors underscores the necessity of tailored strategies—whether through structural retrofits, policy endorsements, or leveraging resilience grants. As climate trends intensify flood risks, policyholders must remain vigilant in reviewing their protections, documenting vulnerabilities, and capitalizing on cost-saving measures. By integrating these insights, stakeholders can fortify their preparedness, ensuring resilience against flood-related disruptions while optimizing long-term insurance sustainability in an increasingly unpredictable landscape.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.