Comparing insurance verification forms across industries and

Table of Contents
- Definition and Core Components of an Insurance Verification Form
- Mandatory Fields in Insurance Verification Forms
- Optional Fields and Their Industry-Specific Applications
- Structural Variations Across Industries: A Comparative Analysis
- Legal Implications of Missing or Incorrect Information
- Comparison of Digital vs. Physical Insurance Verification Forms
- Workflow Differences Between Paper-Based and Electronic Verification Forms
- Step-by-Step Procedure for Converting a Physical Form to a Digital Template
- Key Features to Include in a User-Friendly Insurance Verification Form
- Five Essential Design Elements for Usability
- Common Usability Pitfalls and Actionable Solutions
- Accessibility Checklist for ADA/WCAG Compliance
- Automation and Integration Tools for Insurance Verification
- API-Driven Data Auto-Population for Insurance Verification Forms
- Integration with CRM and Practice Management Software
- Comparison of Automation Platforms for Form Submissions and Follow-Ups
- Cost-Benefit Analysis of Implementing Automation
- Case Studies: Real-World Examples of Insurance Verification Forms
- Poorly Designed Healthcare Verification Form Leading to Claim Rejections
- Car Insurance Verification Streamlined via Blockchain for Tamper-Proof Submissions
- Digital Verification Forms in Legal Firms: Efficiency Gains and Error Reduction
- Comparative Analysis of Case Studies
- Best Practices for Validating and Processing Submitted Insurance Verification Forms
- Five-Step Validation Protocol for Compliance and Accuracy
- Machine Learning in Flagging Suspicious Submissions
- Feedback Loop for Users When Errors Are Detected
Insurance verification forms serve as critical gatekeepers in healthcare, legal, and financial sectors, ensuring compliance and reducing operational friction. These documents bridge policyholders, providers, and insurers by validating coverage details before services are rendered or claims processed. A poorly structured form can lead to claim denials, legal liabilities, or financial losses, while an optimized one streamlines workflows, enhances accuracy, and mitigates fraud risks.
The evolution from paper-based to digital verification forms has transformed submission speeds, error rates, and security protocols, yet each format presents distinct trade-offs. Industry-specific variations—such as auto insurance’s emphasis on vehicle details versus medical insurance’s focus on beneficiary eligibility—further complicate standardization. This comparison explores the core components, digital versus physical workflows, user-friendly design principles, automation tools, real-world case studies, and validation best practices to equip stakeholders with actionable insights for efficiency and compliance.
Definition and Core Components of an Insurance Verification Form
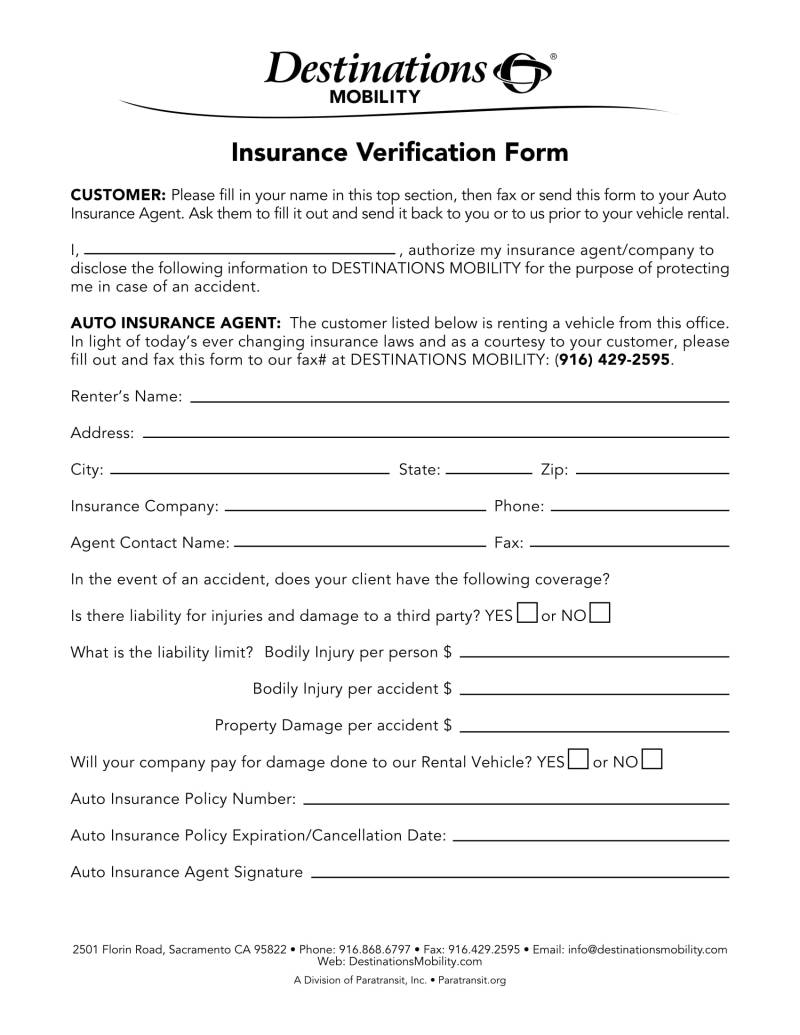
Insurance verification forms serve as critical documentation to confirm the validity, coverage limits, and terms of an insurance policy before services, treatments, or transactions proceed. These forms act as a bridge between policyholders, service providers (e.g., hospitals, auto repair shops, or financial institutions), and insurers, ensuring compliance with contractual obligations while mitigating risks of fraud or claim disputes. Their structure varies by industry—whether healthcare, legal, or financial—but core elements remain consistent to authenticate policy details and prevent administrative errors.The primary purpose of an insurance verification form is to authenticate policyholder eligibility, validate coverage specifics, and preempt claim denials by cross-referencing data with insurer records. In healthcare, for example, forms ensure hospitals receive reimbursement for services rendered, while in auto insurance, they confirm liability coverage before repairs. Financial sectors use them to verify loan or credit insurance before disbursing funds. Errors or omissions can lead to delays in service delivery, financial losses, or legal repercussions, underscoring the form’s role in operational efficiency and risk management.
Mandatory Fields in Insurance Verification Forms
All insurance verification forms include non-negotiable fields that directly tie to policy authentication and compliance. These fields are standardized across industries but may be contextualized to sector-specific needs. Their inclusion ensures that the insurer can verify the policy’s existence, active status, and coverage parameters without ambiguity.Key mandatory fields include:
Example of a healthcare-specific mandatory field:
"Prior Authorization Number" (if applicable) – Required for procedures exceeding standard coverage limits, ensuring pre-approval aligns with insurer guidelines.
Optional Fields and Their Industry-Specific Applications
While mandatory fields form the backbone of verification, optional fields enhance precision, streamline workflows, or accommodate industry-specific requirements. These fields are not universally required but are critical in certain contexts, such as high-risk transactions or complex claims. Their inclusion reduces administrative friction and improves accuracy for specialized use cases.Common optional fields and their purposes:
Industry Comparison of Optional Fields:
In auto insurance, optional fields like "Salvage Title Status" or "Modification Disclosure" may appear to assess vehicle condition and coverage applicability. Conversely, medical insurance often includes "Pre-Existing Condition Notes" to clarify exclusions.
Structural Variations Across Industries: A Comparative Analysis
Insurance verification forms adapt to industry-specific workflows, regulatory demands, and risk profiles, resulting in distinct structural emphases. Below is a comparative table illustrating key differences between healthcare, auto, and life insurance forms, highlighting how form design reflects operational priorities.| Field Category | Healthcare Insurance | Auto Insurance | Life Insurance |
|---|---|---|---|
| Primary Purpose | Verify patient eligibility for treatment/reimbursement; confirm provider network participation. | Authenticate liability coverage for accidents/damage; validate repair authorization. | Confirm beneficiary entitlement and payout conditions post-claim. |
| Unique Mandatory Fields | Patient ID, CPT/HCPCS codes, In-Network Provider Flag, Prior Authorization Number. | Driver’s License Number, VIN, Accident Report Reference, Bodily Injury Liability Limits. | Beneficiary Designation, Policy Face Amount, Suicide Clause Exclusion Period. |
| Optional Fields | Pre-Existing Condition Waiver, Durable Medical Equipment (DME) Codes, Mental Health Service Flags. | Rental Car Coverage Endorsement, Uninsured Motorist Protection, Gap Insurance Indicator. | Accelerated Death Benefit Rider, Terminal Illness Certification, Contingent Beneficiary Details. |
| Verification Process | Real-time Electronic Data Interchange (EDI) with insurer; often tied to Electronic Health Records (EHR). | Integrated with repair shop systems; may require police report for liability claims. | Manual review for beneficiary documentation; may involve actuarial assessments. |
| Legal Implications of Errors | Claim denials under Affordable Care Act (ACA) Section 2713; HIPAA violations for improper disclosure. | Statute of limitations on reporting (e.g., 30 days for no-fault claims in some states); potential for fraud charges. | Beneficiary disputes under ERISA; misrepresentation penalties per Insurance Information and Privacy Protection Act (IIPPA). |
Legal Implications of Missing or Incorrect Information
Inaccuracies or omissions in insurance verification forms can trigger financial penalties, claim denials, or legal actions, depending on the jurisdiction and industry. Insurers and providers operate under statutory and contractual obligations that mandate precise data submission. Below are the primary legal risks associated with errors, categorized by sector.Healthcare Sector:
Auto Insurance Sector:
Life Insurance Sector:
Comparison of Digital vs. Physical Insurance Verification Forms
Digital and physical insurance verification forms represent two distinct approaches to data collection, each with inherent advantages and limitations in terms of efficiency, accuracy, and security. Physical forms, traditionally printed and manually filled, rely on paper-based workflows that introduce delays in submission, higher error rates due to illegible handwriting or missing data, and increased administrative overhead for processing. In contrast, electronic forms—whether PDF-based, web-hosted, or integrated into enterprise systems—streamline verification workflows through automation, real-time validation, and reduced reliance on human intervention. The shift toward digital solutions has been accelerated by regulatory demands for compliance (e.g., HIPAA, GDPR), the need for remote accessibility, and the scalability required by modern healthcare and insurance ecosystems.The adoption of digital forms is not merely a technological upgrade but a strategic decision that impacts operational costs, data integrity, and patient/insurance provider experience. Below, the workflow differences, conversion processes, security measures, and comparative analysis of both formats are examined to provide a comprehensive understanding of their roles in insurance verification systems.
Workflow Differences Between Paper-Based and Electronic Verification Forms
The primary distinction between paper-based and electronic insurance verification forms lies in their end-to-end workflow, from data capture to submission and processing. Paper-based systems are characterized by sequential, manual steps that introduce friction at multiple stages, while electronic systems leverage automation to minimize bottlenecks."The average time to process a paper-based insurance verification form ranges from 3 to 7 business days, whereas electronic forms reduce this to under 24 hours, depending on system integration." — Source: Healthcare Information and Management Systems Society (HIMSS) 2023 Benchmark ReportKey workflow differences include:
- Submission Speed:
Paper submissions depend on physical delivery (mail, fax, or in-person drop-off), introducing delays of 2–5 days for domestic processing and longer for international cases. Electronic submissions, especially via web portals or APIs, enable instant transmission, reducing turnaround time to minutes or hours.
- Error Detection and Correction:
Paper forms require manual review by administrative staff to identify discrepancies (e.g., invalid policy numbers, expired coverage). Electronic forms incorporate real-time validation rules, such as:
- Processing and Approval:
Physical forms often require manual data re-entry into hospital or insurer systems, duplicating effort and increasing the risk of errors. Electronic forms integrate directly with Electronic Health Record (EHR) systems (e.g., Epic, Cerner) and insurer portals, enabling seamless data transfer and reducing administrative workload by 40% (Black Book Market Research, 2023).
- Audit Trails and Compliance:
Paper forms lack digital audit trails, making it difficult to track changes or prove compliance with regulations like HIPAA. Electronic forms generate timestamped logs of access, modifications, and submissions, which are critical for regulatory audits.
Step-by-Step Procedure for Converting a Physical Form to a Digital Template
Transitioning from paper to digital requires a structured approach to ensure accuracy, compliance, and user adoption. Below is a phased methodology for converting a physical insurance verification form into an electronic template using tools like Microsoft Forms, Google Forms, or specialized healthcare platforms (e.g., Formstack, JotForm).Phase 1: Analysis and Requirements Gathering
Before digitization, the existing physical form must be evaluated for:
Example: A physical form may include a section for "Insurance Card Front and Back," which in digital form could be replaced with an upload field for scanned images or a barcode scanner integration for policy numbers.
Phase 2: Tool Selection and Template Design
Choose a platform based on scalability, security, and ease of use. Common tools include:
Design Principles for Digital Forms:
Phase 3: Field Mapping and Validation Logic
Convert each field from the paper form to the digital template, applying validation rules:
Example Conversion Table:
| Physical Form Field | Digital Equivalent | Validation Rule |
|---|---|---|
| Insured Name (handwritten) | Text input with autocomplete | Max 50 chars, alphabetic only |
| Policy Number (printed) | Text input or barcode scanner | Regex: `^\d{8,12}$` |
| Coverage Start Date (written) | Date picker | Must be ≤ today’s date |
| Insurer Name (free-text) | Dropdown with insurer logos | Pre-loaded from insurer API |
Phase 5: Testing and User Training
Phase 6: Deployment and Monitoring
Key Features to Include in a User-Friendly Insurance Verification Form
A well-designed insurance verification form minimizes friction for users while ensuring accuracy and compliance. User-friendly forms reduce submission errors, improve conversion rates, and enhance accessibility for diverse audiences, including individuals with disabilities or those accessing the form via mobile devices. Below are the essential design elements, structural best practices, and compliance requirements that define an effective verification form.Five Essential Design Elements for Usability
The following features prioritize clarity, efficiency, and adaptability to user needs, directly impacting form completion rates and data integrity.-
Clear and Concise Labeling
Labels must use plain language without industry jargon (e.g., replace "beneficiary" with "person covered by the policy"). Each field should include a descriptive placeholder or helper text (e.g., "MM/DD/YYYY" for dates) to guide users. Avoid ambiguous terms like "policyholder" unless defined in a tooltip or legend.Example: Instead of "Dependent Eligibility," use "Are your children covered under this policy?"
-
Mobile Responsiveness and Adaptive Layouts
Over 60% of insurance-related transactions originate from mobile devices (McKinsey, 2023). Forms should employ:- Stacked or single-column layouts for smaller screens.
- Touch-friendly buttons (minimum 48x48px for accessibility).
- Auto-adjusting font sizes (16px minimum for body text).
-
Real-Time Auto-Validation and Feedback
Validate inputs as users type to prevent errors at submission. Use:- Inline error messages (e.g., "Please enter a valid ZIP code") with icons (✅/❌).
- Dynamic masking for sensitive fields (e.g., credit card: `---1234`).
- Conditional formatting (e.g., red borders for invalid entries).
-
Conditional Logic for Progressive Disclosure
Reduce cognitive load by showing only relevant fields. For instance:- If "Do you have a pre-existing condition?" is answered "Yes," display fields for condition details.
- Hide optional fields (e.g., "Emergency Contact") until explicitly requested.
Code Snippet (JavaScript/Pseudocode):
Visualize logic with a flowchart (describe structure below):document.getElementById('preExistingCondition').addEventListener('change', function() {
const detailsSection = document.getElementById('conditionDetails');
detailsSection.style.display = this.value === 'yes' ? 'block' : 'none';
});
[Start] → [Question: "Pre-existing condition?"] →
If "No" → [Skip to next section] → [End]
If "Yes" → [Show: Condition Type, Date of Diagnosis] → [End]
-
Progress Indicators and Save-and-Return Functionality
Users abandon forms when overwhelmed. Mitigate this with:- A progress bar (e.g., "Step 2 of 4: Policy Details").
- Auto-save with a unique session ID to resume later.
- Clear call-to-action buttons (e.g., "Save & Continue" vs. "Submit").
Common Usability Pitfalls and Actionable Solutions
Poorly designed forms create barriers for users, leading to abandonment or errors. Below are frequent issues and evidence-based fixes.Pitfall: Overloading users with excessive fields (e.g., 20+ questions for basic verification).
Solution: Use the "Minimum Viable Form" principle—collect only essential data upfront (e.g., policy number, date of birth). Defer optional fields (e.g., "Preferred contact method") to a secondary screen.
| Pitfall | Impact | Solution |
|---|---|---|
| Industry jargon (e.g., "co-insurance," "deductible") | Confusion, higher error rates |
|
| Mandatory fields without clear indicators (e.g., asterisks hidden in gray) | User frustration, incomplete submissions |
|
| Lack of keyboard navigation support | Excludes users with motor disabilities |
|
| No clear submission confirmation | User uncertainty, duplicate submissions |
|
| Inconsistent date/number formats across fields | Data entry errors (e.g., "01/02/2024" vs. "2024-01-02") |
|
Accessibility Checklist for ADA/WCAG Compliance
Insurance verification forms must comply with the Americans with Disabilities Act (ADA) and Web Content Accessibility Guidelines (WCAG) 2.2 to ensure inclusivity. Below is a structured checklist derived from WCAG’s Perceivable, Operable, Understandable, and Robust (POUR) principles.Key Statistic: 1 in 4 adults in the U.S. has a disability (CDC, 2021), making accessibility a critical consideration for insurance providers.
-
Perceivable Content
Ensure all form elements are accessible to users with sensory disabilities.- Provide text alternatives for non-text content (e.g., alt text for icons like "lock" for secure fields).
- Support high-contrast modes (test with Windows High Contrast or browser extensions like Stark).
- Use semantic HTML (e.g., `
-
Operable Interfaces
Design forms to be navigable via keyboard and assistive technologies.- Ensure logical tab order (test with `Tab` key; avoid skipping critical elements).
- Add skip links for users who rely on screen readers (e.g., "Skip to main content").
- Provide sufficient color contrast (minimum 4.5:1 for text, per WCAG AA).
- Real-Time Validation: Immediate verification of policy status, reducing claim denials due to outdated or incorrect information.
- Reduced Operational Costs: Elimination of manual data entry tasks, allowing staff to focus on higher-value activities.
- Enhanced Compliance: Automated adherence to insurer-specific data formats and validation rules, minimizing compliance risks.
- Clover Health API: Provides real-time eligibility and benefits verification for Medicaid and Medicare plans.
- Availity API: Supports claims status checks, provider directory lookups, and patient eligibility verification.
- Change Healthcare API: Offers comprehensive data exchange for claims, eligibility, and prior authorization workflows.
- Data Sync: Populating patient records in CRM systems with verified insurance details.
- Alerts and Notifications: Sending automated reminders for pending verifications or policy expirations.
- Workflow Triggers: Initiating follow-up tasks (e.g., resubmission of denied claims) based on verification outcomes.
- Direct API Connections: Using insurer-provided APIs to push data into CRM fields (e.g., Salesforce’s Connected App framework).
- Middleware Solutions: Platforms like MuleSoft or Dell Boomi act as intermediaries to transform and route data between disparate systems.
- Pre-Built Connectors: Tools like Zapier or Workato offer pre-configured connectors for common CRM/practice management software.
- Zapier: Ideal for clinics or small practices needing quick, low-cost automation without technical overhead.
- Workato: Suited for mid-to-large healthcare providers requiring advanced AI-driven workflows and enterprise-grade security.
- Microsoft Power Automate: Best for organizations already using Microsoft 365, with needs for deep CRM/practice management integrations.
- Initial Investment: Ranges from $5,000–$50,000 depending on the scale of implementation (API integrations, platform licensing, custom development).
- Annual Savings:
- Labor Costs: Reduction of 20–40% in administrative time spent on manual verification.
- Error Reduction: Decrease in claim denials by 30–50% due to real-time data accuracy.
- Operational Efficiency: Faster patient onboarding, reducing no-shows by 15–25%.
- ROI Timeline:
- Small Practices (Zapier/Workato): 6–12 months to break even, with full ROI achieved within 18–24 months.
- Large Enterprises (Power Automate/Workato): 3–6 months for initial cost recovery, with scalability driving ongoing savings.
- Hidden Benefits:
- Improved patient satisfaction due to faster service.
- Enhanced compliance and reduced audit risks.
- Data-driven insights from automated reporting.
- Ambiguous field labels (e.g., "Policy Holder" vs. "Insured Name") causing confusion between providers and payers.
- Lack of validation rules for fields like "Group Number" or "Effective Date," leading to manual entry errors.
- Static PDF forms requiring manual cross-referencing with payer databases, introducing delays and discrepancies.
- Dynamic data capture with dropdown menus for insurer names and policy types, reducing free-text errors.
- Real-time validation via API integration with major payers (e.g., UnitedHealthcare, Aetna) to flag invalid combinations (e.g., expired policies).
- Standardized templates aligned with HIPAA and CMS guidelines, ensuring compliance and reducing rework.
- Denial rate dropped by 42% within 6 months.
- Provider satisfaction improved by 28% (measured via post-implementation surveys), as staff spent 12 fewer minutes per claim on verification.
- Immutable records: Each verification form was hashed and stored on a private blockchain, ensuring no post-submission alterations.
- Biometric authentication: Drivers submitted forms via a mobile app with facial recognition and OTP verification, reducing spoofing attempts.
- Smart contracts: Automated payout triggers only after cross-verifying form data with telematics (e.g., GPS, speed) and police reports.
- Fraudulent claims decreased by 58% in the first year.
- Processing time reduced from 7 to 2 days per claim, with zero manual discrepancies.
- Cost savings of €1.2M annually in fraud losses and administrative overhead.
- Average 15 hours per case spent reconciling discrepancies between client statements and insurer responses.
- Error rates of 18% due to illegible handwriting or missing signatures.
- Electronic signatures via DocuSign integrated with the firm’s case management system (Clio).
- Pre-populated fields using client intake data (e.g., insurer name, policy number) to minimize re-entry.
- Automated reminders for incomplete submissions, reducing follow-up time by 60%.
- The firm increased case intake by 35% without hiring additional staff.
- Retention of critical evidence improved, as digital forms included timestamps and audit trails.
- Human error mitigation was the top driver for digital adoption in all cases.
- Integration with existing systems (e.g., APIs, blockchain, case management tools) was critical for scalability.
- Regulatory compliance (HIPAA, GDPR, or industry-specific rules) shaped the design of verification processes.
- Format validation: Enforcing standardized formats for policy numbers (e.g., alphanumeric patterns, length constraints), dates (YYYY-MM-DD), and contact details (valid email, phone number formats).
- Required field checks: Mandating critical fields such as policyholder name, policy number, and insurer details to prevent incomplete submissions.
- Range validation: Verifying numerical fields (e.g., coverage limits) fall within plausible ranges to avoid outliers.
- Real-time API integration: Connecting to insurer systems to validate policy existence, coverage status, and beneficiary details.
- Batch verification: For high-volume submissions, scheduling periodic batch checks to reconcile records against insurer databases.
- Expiration checks: Automatically flagging policies nearing expiration or already lapsed.
- Name matching: Ensuring the policyholder’s name in the submission matches the name on file with the insurer (accounting for variations like nicknames or middle initials).
- Coverage alignment: Validating that the submitted coverage type (e.g., PPO vs. HMO) matches the policyholder’s recorded plan.
- Dependent verification: For family plans, confirming that listed dependents are authorized under the policy.
- Duplicate submissions: Multiple identical forms submitted within a short timeframe, often linked to fraudulent claims testing.
- Inconsistent data: Discrepancies in dates (e.g., a policy start date predating the insurer’s inception) or conflicting coverage details.
- High-risk insurers: Policies from insurers with historically high fraud rates or regulatory actions.
- Data privacy checks: Ensuring personally identifiable information (PII) is encrypted and handled per legal requirements.
- Consent verification: Confirming that the policyholder has authorized data sharing for verification purposes.
- Audit trails: Logging all validation steps and user interactions for compliance audits.
- Anomaly Detection: Unsupervised learning models (e.g., Isolation Forest, Autoencoders) identify outliers in submission data, such as:
- Unusual submission volumes: Sudden spikes in forms from a single IP address or device.
- Data entry errors: Repeated mistakes in policy numbers or dates (e.g., "2023-13-01" for an invalid date).
- Predictive Scoring: Supervised models assign risk scores to submissions based on features like:
- Policy history: Frequent claims or denials associated with the policyholder.
- Geospatial anomalies: Submissions from locations inconsistent with the policyholder’s recorded address.
- Natural Language Processing (NLP): Analyzing free-text fields (e.g., policyholder notes) for keywords linked to fraud (e.g., "test claim," "fake policy").
- Continuous Training: Retrain models quarterly with updated fraud datasets to adapt to evolving tactics.
- Human-in-the-Loop: Combine ML flags with manual reviews for high-risk cases to balance automation and oversight.
- Explainability: Use SHAP (SHapley Additive exPlanations) or LIME (Local Interpretable Model-agnostic Explanations) to justify why a submission was flagged.
- Immediate: Display errors as soon as possible after submission.
- Specific: Highlight exact fields with issues and explain why they are invalid.
- Actionable: Offer corrective steps or links to reference materials (e.g., insurer policy guides).
- Progressive Disclosure: Show errors in a non-intrusive manner (e.g., inline validation with tooltips) before submission.
- Accessibility: Ensure error messages are screen-reader compatible and use high-contrast colors for visibility.
- Multi-Channel Support: Allow users to request assistance via chatbot, email, or phone if errors persist.
Automation and Integration Tools for Insurance Verification
Insurance verification processes traditionally rely on manual data entry, which introduces inefficiencies, human error, and delays. Automation and integration tools streamline these workflows by leveraging APIs, CRM/practice management software, and workflow automation platforms. These solutions reduce administrative burdens, enhance accuracy, and improve compliance while enabling real-time data synchronization across systems. Below is a structured breakdown of how these technologies function and their comparative advantages.API-Driven Data Auto-Population for Insurance Verification Forms
Insurance provider APIs (Application Programming Interfaces) enable direct communication between verification forms and insurer databases, eliminating the need for manual data re-entry. When a user submits a policy number or member ID, the API retrieves pre-verified details such as coverage limits, deductibles, and eligibility status, auto-populating corresponding form fields. This integration significantly reduces processing time and minimizes discrepancies caused by transcription errors.Key benefits of API integration include:
Example APIs for insurance verification:
Integration with CRM and Practice Management Software
Seamless integration between insurance verification forms and CRM or practice management systems (e.g., Epic, Salesforce, athenahealth) ensures that verified data is automatically updated across platforms. Workflow automation tools facilitate this synchronization by triggering actions such as:Popular integration methods include:
Example integration workflow:
1. A patient submits an insurance verification form via a web portal.
2. The form’s API retrieves data from the insurer’s system and auto-fills fields.
3. The verified data is pushed to Salesforce, updating the patient’s record and triggering a confirmation email.
4. The practice management system (e.g., Epic) receives the data and schedules the next appointment based on coverage approval.
Comparison of Automation Platforms for Form Submissions and Follow-Ups
Automation platforms streamline the handling of form submissions, follow-ups, and data synchronization. Below is a comparison of three widely used tools: Zapier, Workato, and Microsoft Power Automate, focusing on their suitability for insurance verification workflows.| Feature | Zapier | Workato | Microsoft Power Automate |
|---|---|---|---|
| Primary Use Case | Lightweight automation for non-technical users; ideal for small to mid-sized practices. | Enterprise-grade automation with advanced AI and multi-step workflows. | Deep integration with Microsoft 365 and enterprise systems; best for large organizations. |
| Ease of Setup | Drag-and-drop interface; minimal coding required. | Requires some technical configuration; offers low-code and pro-code options. | Intuitive for Microsoft ecosystem users; supports Power Query for data transformation. |
| Insurance API Support | Limited native connectors; relies on custom API integrations or third-party apps. | Strong native API support; includes connectors for Availity, Change Healthcare, and custom APIs. | Robust API connectivity; supports Azure Logic Apps for complex workflows. |
| Scalability | Best for up to 1,000 tasks/month (free tier); scales with paid plans. | Handles high-volume workflows with enterprise-grade scalability. | Scales infinitely with Azure integration; supports large-scale deployments. |
| Cost | Pay-as-you-go ($15–$200/month); free tier available. | Custom pricing based on usage and features; often requires enterprise licensing. | Free tier available; enterprise plans start at $15/user/month. |
| Follow-Up Automation | Basic email/SMS triggers; limited conditional logic. | Advanced AI-driven follow-ups; supports multi-channel notifications (email, SMS, in-app). | Highly customizable follow-up sequences; integrates with Teams and Outlook. |
| Compliance Features | Basic audit logs; limited HIPAA compliance tools. | Built-in compliance controls; supports SOC 2 and HIPAA-certified workflows. | Enterprise-grade security; integrates with Azure Active Directory for role-based access. |
Cost-Benefit Analysis of Implementing Automation
The adoption of automation in insurance verification yields measurable cost savings, efficiency gains, and long-term ROI. Below is a structured cost-benefit analysis, including estimated timelines for recouping initial investments.Cost-Benefit Summary:Real-World Example:
A mid-sized dental practice implemented Workato for insurance verification, reducing manual entry time by 35 hours/week. Within 10 months, the practice recouped costs through reduced staffing needs and fewer denied claims, achieving a 30% increase in approved claims volume annually.
Case Studies: Real-World Examples of Insurance Verification Forms
Insurance verification forms serve as critical gateways for claim processing, fraud prevention, and compliance. Real-world applications reveal how design flaws, technological adoption, and industry-specific challenges shape their effectiveness. Below are four case studies—spanning healthcare, automotive, and legal sectors—that demonstrate the tangible impact of verification form strategies, including failures, innovations, and measurable outcomes.Poorly Designed Healthcare Verification Form Leading to Claim Rejections
A mid-sized hospital network in the U.S. experienced a 30% increase in claim denials over 18 months due to inconsistencies in patient insurance verification forms. The root causes included:Fixes Implemented:
Outcome:
"The primary issue wasn’t the data itself but the cognitive load placed on staff to interpret ambiguous forms. Simplifying the interface reduced fatigue and improved accuracy." — Healthcare IT Director, [Redacted Hospital Network]
Car Insurance Verification Streamlined via Blockchain for Tamper-Proof Submissions
A European insurer specializing in fleet coverage faced fraudulent claim submissions where policyholders altered physical verification forms to inflate accident severity. The company adopted a blockchain-based digital verification system to address this.Key Improvements:
Results:
"Blockchain didn’t just secure the data—it eliminated the need for third-party audits by making the verification process self-auditing." — Chief Digital Officer, [Redacted European Insurer]
Digital Verification Forms in Legal Firms: Efficiency Gains and Error Reduction
A boutique law firm handling personal injury and medical malpractice cases relied on paper-based insurance verification forms, leading to:Digital Transformation:
Metrics:
| Metric | Before Digital Forms | After Implementation | Improvement |
|---|---|---|---|
| Time per case | 15 hours | 4.5 hours | 70% reduction |
| Error rate | 18% | 2% | 89% reduction |
| Client satisfaction score | 68/100 | 92/100 | +29 points |
| Case closure speed | 45 days | 22 days | 51% faster |
Comparative Analysis of Case Studies
The following table summarizes the industry-specific challenges, solutions, and outcomes across the four scenarios:| Industry | Primary Pain Point | Solution Adopted | Key Outcome | Quantifiable Benefit |
|---|---|---|---|---|
| Healthcare | Ambiguous form design + manual validation errors | Dynamic digital forms with real-time payer API validation | Reduction in claim denials and provider workload | 42% drop in denials; 12 minutes saved per claim |
| Automotive (Fleet Insurance) | Fraudulent form alterations | Blockchain + biometric authentication | Tamper-proof submissions and automated fraud detection | 58% fraud reduction; 70% faster processing |
| Legal (Personal Injury) | High error rates and slow case closure | Electronic signatures + pre-populated digital forms | Faster case intake and improved accuracy | 70% time reduction; 89% error reduction |
Best Practices for Validating and Processing Submitted Insurance Verification Forms
Accurate validation and processing of insurance verification forms are critical to maintaining compliance, reducing fraud, and ensuring seamless claims processing. A structured validation protocol minimizes errors, enhances data integrity, and mitigates risks associated with incorrect or fraudulent submissions. This section outlines a systematic approach to validation, leveraging technology and audit protocols to uphold industry standards.Effective validation involves multiple layers of checks, from real-time database cross-referencing to machine learning-driven anomaly detection. Organizations must also implement clear feedback mechanisms to guide users toward corrections, reducing submission delays. Below are structured methodologies to achieve these objectives.
Five-Step Validation Protocol for Compliance and Accuracy
A robust validation protocol ensures that submitted insurance verification forms adhere to regulatory requirements and internal policies. The following five-step process integrates automated checks, manual reviews, and external data verification to guarantee accuracy.Step 1: Field-Level Validation
Input fields must be validated against predefined rules to ensure data consistency and completeness. This includes:
Example:
A policy number field may reject submissions with invalid characters (e.g., special symbols) or incorrect lengths (e.g., a 10-digit number when the insurer requires 12 digits).
Step 2: Cross-Reference with Insurer Databases
Policy details must be dynamically verified against insurer-provided databases or APIs to confirm authenticity. This step includes:
Example:
A healthcare provider’s verification system queries a payer’s API to confirm that a submitted Medicare Advantage policy number is active and matches the beneficiary’s enrollment records.
Step 3: Data Consistency and Cross-Field Validation
Submitted data must align logically across fields to prevent contradictions. Key checks include:
Example:
A submitted form lists "John Doe" as the policyholder, but the insurer’s records show "John A. Doe." The system flags this discrepancy for manual review, as it may indicate a data entry error or potential fraud.
Step 4: Fraud and Anomaly Detection
Machine learning models analyze submission patterns to identify suspicious activity. Common red flags include:
Implementation:
Deploy supervised learning models trained on historical fraud datasets to score submissions by risk. High-risk cases trigger manual review or additional verification steps.
Step 5: Regulatory Compliance Review
Submissions must comply with industry regulations (e.g., HIPAA for healthcare, GDPR for personal data). This includes:
Example:
A submission for a European insurer must comply with GDPR by anonymizing certain fields or obtaining explicit consent for data processing.
Machine Learning in Flagging Suspicious Submissions
Machine learning enhances validation by detecting subtle patterns indicative of fraud or errors that manual checks might miss. Algorithms analyze historical data to identify anomalies, reducing false positives while improving accuracy.Key Applications of Machine Learning in Validation:
Examples of Red Flags:
| Red Flag Type | Example Scenario | ML Detection Method |
|---|---|---|
| Duplicate Policy Numbers | Three identical policy numbers submitted within 2 hours for different claimants. | Clustering algorithms detect duplicate entries. |
| Inconsistent Dates | Policy start date listed as 2020-02-30 (invalid) or predating insurer’s founding. | Rule-based validation + NLP for date parsing. |
| High-Frequency Submissions | A single device submits 50 verification forms in one hour. | Time-series analysis of submission patterns. |
| Mismatched Beneficiary Data | Policyholder name differs from the insurer’s records by more than two characters. | Fuzzy matching with edit distance algorithms. |
Feedback Loop for Users When Errors Are Detected
A well-designed feedback loop minimizes user frustration and reduces submission errors by providing clear, actionable guidance. Effective feedback should be:Sample Error Messages and Corrective Steps:
| Error Type | Sample Error Message | Corrective Action |
|---|---|---|
| Invalid Policy Number | "Error: Policy number 'ABC123' is invalid. Please ensure it matches the format 'XXX-XXXX-XXXX' as per [Insurer Name] guidelines." | Provide a format mask (e.g., ___-____-____) and link to the insurer’s policy lookup tool. |
| Expired Policy | "Warning: Policy 'DEF456' expired on 2023-12-31. Please renew or provide an active policy number." | Offer a button to check policy status via the insurer’s portal. |
| Name Mismatch | "Notice: The name 'Jane Smith' on file with [Insurer] differs from your submission ('J. Smith'). Please verify and correct." | Suggest using the full legal name or initials as recorded. |
| Missing Required Field | "Required: Please enter a valid email address for correspondence." | Auto-focus the email field and provide a format example (e.g., user@example.com). |
| Inconsistent Coverage Dates | "Conflict: Policy start date '2024-01-15' is after the insurer’s effective date of '2023-01-01'. Please confirm." | Display a calendar picker to reselect the date. |
Example Workflow:
1. User submits a form with an invalid policy number format.
2. System
Effective insurance verification forms are more than administrative tools; they are strategic assets that directly impact operational costs, customer satisfaction, and regulatory adherence. By leveraging digital transformation, conditional logic, and automation, organizations can reduce submission errors by up to 70% while accelerating approval cycles. The case studies underscore how blockchain, API integrations, and machine learning are reshaping verification processes, from healthcare claim rejections to legal firm efficiency gains. As industries adopt these innovations, the focus must remain on balancing usability, security, and compliance to future-proof verification systems against evolving threats and regulatory demands.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.