Agents in Insurance Evolution Trends and Strategic Insights
Published

agents in insurance - Kesimpulan
Table of Contents

The insurance industry has undergone a profound transformation, with agents serving as pivotal intermediaries bridging complex policies and client needs. From traditional brokers to digitally empowered intermediaries, their role has evolved alongside technological advancements, reshaping how risk is assessed, policies are sold, and claims are processed. This shift demands a nuanced understanding of historical milestones, regulatory frameworks, and emerging tools that redefine agent effectiveness in an increasingly competitive landscape.

Modern agents must navigate a dynamic ecosystem where data-driven personalization, ethical compliance, and seamless technology integration dictate success. Whether through consultative selling, AI-enhanced workflows, or compliance-driven transparency, their ability to adapt directly influences customer trust and operational efficiency. Exploring these dimensions reveals how agents not only survive but thrive in an industry where innovation and adherence to best practices are non-negotiable.

Role and Evolution of Agents in the Insurance Industry

The insurance agent has undergone a profound transformation since its inception, evolving from a primarily transactional role to a strategic advisor embedded in both traditional and digital ecosystems. Historically, agents served as brokers connecting insurers with clients, relying on interpersonal relationships and manual processes. Today, technological integration, regulatory shifts, and changing consumer expectations have redefined their responsibilities, shifting focus toward data-driven decision-making, automation, and hybrid service models. This evolution reflects broader industry trends, including the decline of traditional commission-based models, the rise of direct-to-consumer (D2C) platforms, and the adoption of AI-driven tools that enhance efficiency while demanding higher skill sets from agents.

The trajectory of insurance agents mirrors the industry’s broader digital disruption, where legacy systems coexist with innovative solutions. Key milestones—such as the emergence of independent agents in the 1970s, the dominance of captive agents in the 1990s, and the current proliferation of digital intermediaries—highlight how external forces, including economic crises and technological breakthroughs, have reshaped agent roles. Meanwhile, advancements like blockchain for smart contracts, AI for risk assessment, and cloud-based CRM systems have not only streamlined operations but also introduced new competencies required for modern agents. Understanding these shifts is critical for insurers, agents, and consumers alike, as the industry navigates toward a future where human expertise and digital tools converge.

Historical Progression of Insurance Agents

The role of insurance agents has evolved through distinct phases, each shaped by economic conditions, regulatory frameworks, and technological capabilities. Early agents, active in the 18th and 19th centuries, functioned as brokers facilitating policy sales and claims, often operating within tightly knit communities. The Great Depression (1930s) marked a turning point, as insurers sought to stabilize operations by employing captive agents—exclusive representatives tied to a single carrier—reducing reliance on independent brokers. Post-World War II, the 1950s and 1960s saw the rise of independent agents, who could sell policies from multiple insurers, fostering competition and client-centric advisory services.

The 1980s and 1990s introduced significant structural changes with the advent of direct-writing models, where insurers bypassed agents entirely, selling policies through telemarketing, mail-order, and early internet platforms. This period also witnessed the commercialization of insurance, where agents increasingly focused on high-net-worth clients and complex risk management solutions. By the 2000s, the digital revolution accelerated with the launch of comparison websites (e.g., Compare.com, Insure.com) and insurtech startups, which challenged traditional agent-based distribution channels. Today, agents operate within a multi-channel ecosystem, balancing digital tools with personalized service to retain relevance in a competitive market.

Technological Advancements and Operational Transformation

Technological innovations have fundamentally altered the operational capabilities of insurance agents, enabling greater efficiency, accuracy, and scalability. Artificial Intelligence (AI) and Machine Learning (ML) now underpin critical functions such as underwriting automation, where algorithms assess risk profiles in real time, reducing reliance on manual reviews. For example, LexisNexis Risk Solutions uses AI to evaluate credit scores and fraud risks, while Guidewire’s AI tools automate claims triage, expediting payouts by up to 40% in some cases.

Blockchain technology has introduced transparency and security to policy administration, particularly in parametric insurance and smart contracts. Platforms like Etherisc and AIG’s blockchain-based claims system enable instant, tamper-proof settlements triggered by predefined conditions (e.g., weather events). Cloud computing has further democratized access to data, allowing agents to leverage real-time analytics and predictive modeling through tools like IBM Watson or SAS Insurance Analytics. Meanwhile, customer relationship management (CRM) systems (e.g., Salesforce Insurance Cloud, PolicyAdmin) integrate AI chatbots, automated workflows, and mobile access, enabling agents to manage portfolios and client interactions seamlessly.

The adoption of these technologies has also introduced hyper-personalization, where agents use data insights to tailor policies to individual needs. For instance, usage-based insurance (UBI) models, powered by telematics (e.g., Progressive’s Snapshot, Allstate’s Drivewise), adjust premiums based on real-time driving behavior, a function previously impossible without digital integration.

Comparative Analysis of Agent Roles Across Insurance Sectors

Insurance agents’ responsibilities and revenue models vary significantly across sectors, reflecting the distinct complexities and regulatory environments of life, health, property, and casualty (P&C) insurance. Below is a structured comparison:
Sector Primary Agent Role Key Responsibilities Revenue Model Technological Dependencies Unique Challenges
Life Insurance Financial Advisor & Trust Builder
  • Policy customization (term, whole, universal life).
  • Estate planning and retirement solutions.
  • Client education on tax implications and beneficiaries.
  • Cross-selling ancillary products (e.g., annuities).
  • High commission rates (30–100% of first-year premium).
  • Renewal commissions (1–10% annually).
  • Fee-based advisory for high-net-worth clients.
  • AI-driven financial planning tools (e.g., Fidelity’s Life Insurance Calculator).
  • Blockchain for beneficiary verification.
  • CRM integration with robo-advisors.
  • Regulatory compliance (e.g., SEC, FINRA for variable products).
  • Long sales cycles and emotional client resistance.
  • Legacy underwriting biases in mortality tables.
Health Insurance Navigational Guide & Compliance Specialist
  • ACA marketplace enrollment and subsidy qualification.
  • Network provider negotiations.
  • Claims advocacy and appeals.
  • Integration with employer benefit plans.
  • Commission-based (varies by state, often capped).
  • Fee-for-service for small business plans.
  • Salary-plus-bonus for broker-dealer models.
  • HealthTech integrations (e.g., Oscar Health’s API for real-time eligibility checks).
  • Predictive analytics for high-risk pools.
  • Telehealth coordination tools.
  • Complex regulatory landscapes (e.g., ACA, HIPAA).
  • High customer churn due to policy changes.
  • Data privacy concerns in electronic health records (EHR) sharing.
Property & Casualty (P&C) Risk Manager & Claims Liaison
  • Risk assessment and loss prevention consulting.
  • Policy bundling (auto, home, business).
  • Claims filing and dispute resolution.
  • Commercial risk engineering (e.g., workplace safety audits).
  • Commission split (e.g., 80/20 agent-carrier).
  • Flat fees for commercial policies.
  • Retention bonuses for high-value clients.
  • Drones and IoT for property inspections (e.g., Verisk’s 3D modeling).
  • AI fraud detection (e.g
    The evolution of agent-customer dynamics in the insurance industry has shifted from transactional exchanges to relationship-driven, consultative engagements. This transformation is underpinned by technological advancements, changing customer expectations, and a deeper understanding of personalized service delivery. Agents now leverage data-driven insights and digital tools to enhance engagement, while maintaining the human touch that differentiates them from automated systems. Below, key trends, best practices, and strategic frameworks are examined to illustrate how agents can optimize interactions at every stage of the customer journey.

    Shift from Transactional to Consultative Selling

    The traditional insurance sales model, characterized by product-centric transactions, has given way to consultative selling, where agents act as trusted advisors. This shift aligns with the growing demand for transparency, customization, and proactive risk management. Firms adopting this approach have reported 20–30% higher customer retention rates (McKinsey, 2022) and a 40% increase in cross-selling opportunities (Deloitte, 2021) by positioning agents as problem-solvers rather than mere policy sellers.

    Case Studies of Successful Adoption:

  • Allianz: Implemented a "Risk Consultant" model where agents conduct in-depth risk assessments for SMEs, offering tailored solutions beyond standard policies. This approach increased policy uptake by 28% in pilot regions (Allianz Annual Report, 2023).
  • State Farm: Launched "Agent-Led Digital" initiatives, combining AI-driven risk profiling with agent-led consultations. Agents use pre-filled risk assessments to focus discussions on gaps, reducing sales cycles by 35% (Forbes Insights, 2023).
  • AXA: Deployed "AXA Advisor" programs, where agents partner with customers to create personalized risk management plans, including cybersecurity and health wellness modules. This strategy boosted renewal rates by 22% (AXA Sustainability Report, 2022).
  • Key Drivers of the Shift:

  • Customer Expectations: 73% of policyholders prefer advisors who understand their unique risks over those selling generic products (PwC, 2023).
  • Regulatory Pressures: Compliance requirements (e.g., GDPR, Dodd-Frank) mandate transparency, pushing agents toward advisory roles.
  • Competition from Insurtechs: Digital-first firms (e.g., Lemonade, Hippo) offer speed and convenience, forcing traditional agents to differentiate through expertise.
  • Data Analytics and Customer Segmentation for Personalized Recommendations

    Data analytics enables agents to move beyond generic product pitches by identifying risk profiles, coverage gaps, and behavioral patterns specific to each customer. Segmentation tools categorize clients into clusters (e.g., high-risk entrepreneurs, health-conscious families) to tailor recommendations. Metrics such as claims history, asset exposure, and digital footprint (e.g., online behavior) are analyzed to refine strategies.

    Examples of Metrics Used:

    CategoryKey MetricsApplication in Insurance
    Risk AssessmentCredit score, industry classification, past claims frequencyAdjust premiums or recommend niche policies (e.g., professional liability for consultants).
    Coverage GapsPolicy expiration dates, uninsured assets (e.g., jewelry, collectibles)Propose add-ons (e.g., scheduled personal property coverage).
    Customer BehaviorPolicy interaction frequency, digital engagement (app usage, chatbot queries)Trigger proactive check-ins or educational content (e.g., "Your home insurance expires soon").
    Lifestyle FactorsAge, location, hobbies (e.g., skiing, home renovation projects)Offer bundled policies (e.g., travel + medical for adventure seekers).
    Tools Enabling Personalization:
  • Predictive Modeling: AI platforms (e.g., Guidewire, Duck Creek) analyze claims data to predict future risks, allowing agents to preemptively address vulnerabilities.
  • Customer Relationship Management (CRM) Systems: Tools like Salesforce Insurance Cloud integrate with underwriting systems to pull real-time risk scores during consultations.
  • Behavioral Analytics: Firms use Google Analytics or Segment to track how customers interact with digital touchpoints (e.g., time spent on policy pages), guiding agents on where to focus discussions.
  • Best Practices for Implementation:

  • Ethical Data Use: Ensure compliance with privacy laws (e.g., CCPA) and obtain explicit consent for data collection.
  • Agent Training: Equip agents with data literacy skills to interpret analytics without over-reliance on automation.
  • Feedback Loops: Continuously refine segmentation models based on agent-customer interaction outcomes (e.g., which recommendations led to conversions).
  • Step-by-Step Guide to Conducting Effective Needs Assessments

    A structured needs assessment ensures agents uncover latent risks and align solutions with customer priorities. Below is a 5-phase framework, incorporating probing questions and active listening techniques to guide the process.

    Phase 1: Establish Rapport and Context
    Agents begin by building trust through open-ended questions that explore the customer’s current insurance landscape and risk perception. This phase sets the tone for a collaborative discussion.

    Probing Questions:
  • "Walk me through your current insurance coverage. What feels like it’s working well, and where do you see gaps?"
  • "What keeps you up at night when you think about protecting your assets or loved ones?"
  • "How do you typically prepare for unexpected events (e.g., emergencies, legal issues)?"
  • Phase 2: Identify Core Risks and Priorities
    Customers often underestimate risks due to familiarity or complacency. Agents use risk exposure frameworks to surface blind spots.
    Key Techniques:
  • The "What-If" Scenario: "If your primary income source were disrupted for 6 months, how would you manage?"
  • Asset Inventory: "Let’s list your high-value items. Which ones aren’t fully covered under your current policy?"
  • Behavioral Triggers: "Do you frequently travel internationally, or have you recently renovated your home?"
  • Phase 3: Quantify Needs with Data-Driven Insights
    Leverage pre-analyzed data (e.g., risk scores, industry benchmarks) to validate customer statements and propose tailored solutions.
    Example Workflow:
    1. Agent inputs customer details into CRM → System flags high-exposure risks (e.g., "Your business operates in a flood-prone zone").
    2. Agent asks: "Based on your location, have you considered flood insurance? Here’s how it could protect your inventory." 3. Use visual aids (e.g., side-by-side coverage comparisons) to highlight gaps.
    Phase 4: Align Solutions with Customer Values
    Customers are more likely to commit to policies that resonate with their goals and pain points. Agents explore:
  • Financial Objectives: "Are you saving for a milestone (e.g., college, retirement) that we should factor into your coverage?"
  • Lifestyle Changes: "You mentioned your child is joining a sports team—have you reviewed liability coverage for recreational activities?"
  • Digital Habits: "How do you handle online transactions? Cyber insurance might be relevant if you store customer data."
  • Phase 5: Close with a Personalized Action Plan
    Summarize findings, present options, and co-create a roadmap. Use the "Feel-Felt-Found" technique to address objections:

    "I understand you feel this policy is expensive. Others felt the same, but found that the 24/7 claims support saved them thousands in downtime after a loss."
    Tools to Support Assessments:
  • Digital Checklists: Mobile apps (e.g., Insurance Nexus) guide agents through standardized questions.
  • Voice-of-Customer (VoC) Analytics: Transcribe and analyze past consultations to identify recurring gaps (e.g., "80% of SMEs overlook cyber risks").
  • Comparison of Traditional vs. Digital Engagement Strategies

    The choice between face-to-face and digital interactions depends on customer preferences, complexity of the sale, and agent bandwidth. Below is a comparative analysis of both approaches, focusing on acquisition, retention, and operational efficiency.

    Traditional Face-to-Face Sales
    Pros:

  • Trust Building: 68% of customers trust agents more after in-person meetings (Insurance Journal, 2023).
  • Complex Sales: Ideal for high-value, multi-product policies (e.g., estate planning, commercial insurance).
  • Relationship Depth: Agents can read non-verbal cues and adapt discussions dynamically.
  • Cons:

  • Time-Consuming: Average consultation duration is 45–90 minutes, limiting agent capacity.
  • Geographic Constraints: Rural or mobile customers face accessibility barriers.
  • Higher Costs: Office rent, travel, and in-person materials (e.g., brochures) increase overhead.
  • Digital Engagement Strategies
    Pros:

  • Scalability: Chatbots and
  • Regulatory and Ethical Considerations for Insurance Agents

    The insurance industry operates within a tightly regulated framework designed to protect consumers, ensure market integrity, and uphold professional standards. Insurance agents must navigate a complex landscape of legal and ethical obligations, balancing compliance with evolving industry expectations. Regulatory bodies enforce licensing, conduct rules, and anti-fraud measures, while ethical dilemmas—such as conflicts of interest or data privacy—demand proactive adherence to fiduciary principles. Non-compliance exposes agents to legal penalties, reputational harm, and industry sanctions, underscoring the need for structured adherence to guidelines and transparent client interactions.

    Regulatory oversight ensures agents meet minimum competency standards and operate within defined boundaries, while ethical frameworks guide decision-making in ambiguous scenarios. Below, key regulatory authorities, ethical challenges, compliance requirements, and strategies for transparency are examined to equip agents with actionable insights.

    Primary Regulatory Bodies and Their Mandates

    Insurance agents in the U.S. are subject to oversight by state insurance departments, the National Association of Insurance Commissioners (NAIC), and federal agencies where applicable (e.g., FINRA for variable products). These bodies establish licensing protocols, enforce conduct rules, and standardize compliance across jurisdictions.

    The NAIC develops model laws and regulations, such as the Insurance Agents and Brokers Licensing Model Act, which many states adopt to harmonize licensing requirements. State departments, such as the California Department of Insurance (CDI) or Texas Department of Insurance (TDI), issue licenses, investigate complaints, and impose disciplinary actions. Federal agencies like the Securities and Exchange Commission (SEC) or Federal Trade Commission (FTC) intervene in cases involving securities-linked products or deceptive practices.

    Key NAIC Model Regulations:
  • Model Regulation 260 (Licensing) – Defines eligibility, exam requirements, and continuing education (CE) mandates.
  • Model Regulation 275 (Unfair Trade Practices) – Prohibits misrepresentation, coercion, and unfair discrimination.
  • Model Regulation 280 (Market Conduct) – Requires agents to act in clients’ best interests and maintain proper records.
  • State-specific variations exist; for example, Florida’s Office of Insurance Regulation enforces stricter CE requirements for flood insurance agents, while New York’s Department of Financial Services (DFS) mandates annual ethics training for life and health agents.

    Ethical Dilemmas and Resolution Frameworks

    Insurance agents frequently encounter ethical conflicts, particularly in product recommendations, commission disclosure, and handling sensitive client data. Common dilemmas include:
  • Conflict of Interest in Policy Selection: Recommending a high-commission product over a more suitable but lower-paying option.
  • Data Privacy Violations: Unauthorized sharing of client medical or financial information.
  • Twisting or Churning: Inducing policy replacements to generate renewals without client benefit.
  • Misrepresentation of Policy Terms: Omitting exclusions or exaggerating coverage to secure sales.
  • Resolution frameworks rely on fiduciary duty principles, NAIC’s Code of Ethics, and state-specific conduct rules. Agents must:
    1. Prioritize Client Welfare: Align recommendations with the client’s needs, not commissions (e.g., disclosing that a whole-life policy may not be ideal for a term insurance candidate).
    2. Maintain Transparency: Provide clear, written explanations of policy exclusions, premium structures, and agent compensation.
    3. Uphold Confidentiality: Adhere to GDPR-equivalent state laws (e.g., California’s CCPA) and secure client data with encryption and access controls.
    4. Document Interactions: Keep records of client communications, especially when discussing complex products or declines.

    Fiduciary Duty in Insurance:
    "An agent owes undivided loyalty, full disclosure, and reasonable care to the client’s interests, even when conflicting with personal or employer incentives." —NAIC Model Regulation 275 (Unfair Trade Practices)
    Case Example: In 2021, an Arizona agent faced disciplinary action for recommending a universal life policy to elderly clients without disclosing high fees, leading to policy lapses. The Arizona Corporation Commission fined the agent and mandated ethics retraining, citing violations of Arizona Revised Statutes § 20-1411.

    Compliance Checklist for Insurance Agents

    Adherence to regulatory and ethical standards requires systematic compliance with licensing, education, and conduct requirements. Below is a structured checklist, categorized by priority:
    Category Requirement Frequency/Deadline Authority
    Licensing Pass state-specific exam (e.g., Property & Casualty, Life & Health). One-time (initial licensing). State Insurance Department / NAIC Model Act 260.
    Submit fingerprints for background check (where required). During application. FBI / State Criminal Records.
    Renew license before expiration (varies by state: biennial/annual). Every 1–2 years (e.g., Texas: biennial; New York: annual). State Insurance Department.
    Continuing Education (CE) Complete CE credits (e.g., 24 hours every 2 years for California). As mandated (e.g., 24–36 hours per renewal cycle). State CE Provider / NAIC Model Act 260.
    Include ethics training (e.g., 3 hours on anti-fraud annually in Florida). Annual/renewal-specific. State Insurance Department.
    Anti-Fraud and Conduct Report suspected fraud to state Fraud Bureau (e.g., Texas: TDI Fraud Unit). Immediate (within 30 days of suspicion). State Insurance Department / NAIC Model Regulation 280.
    Maintain records of client interactions (e.g., policy applications, complaints) for 5+ years. Ongoing (retention period varies by state). State Insurance Department / NAIC Model Regulation 275.
    Disclose commissions in writing (e.g., via NAIC’s Model Commission Disclosure Form). At time of sale or renewal. State Insurance Department / NAIC Model Regulation 260.
    Data Privacy and Security Implement HIPAA-compliant safeguards for health-related data (if applicable). Ongoing (annual risk assessments). HHS (Federal) / State Privacy Laws (e.g., CCPA).
    Use encryption for electronic client records and limit access to authorized personnel. Ongoing (audited annually). State Insurance Department / GLBA (Gramm-Leach-Bliley Act).
    Note: Requirements vary by state; agents must consult their state insurance department for jurisdiction-specific rules. For example, Massachusetts requires agents to complete annual cybersecurity training, while Illinois mandates bilingual disclosures for non-English-speaking clients.

    Consequences of Non-Compliance

    Failure to meet regulatory or ethical standards results in legal penalties,

    Technology Integration: Tools and Platforms for Insurance Agents

    Modern insurance agents leverage technology to streamline operations, enhance customer engagement, and improve decision-making. Tools such as Customer Relationship Management (CRM) systems, underwriting software, and claims management platforms automate repetitive tasks, provide real-time data insights, and integrate seamlessly with insurtech innovations. APIs and third-party integrations further enable agents to offer personalized, data-driven services, including dynamic pricing adjustments and automated risk assessments. Below, the functionality of these tools is explored, alongside a comparative analysis of leading platforms, implementation strategies for AI-driven solutions, and a structured approach to digital marketing for lead generation.

    Functionality of Modern Agent Tools: CRM, Underwriting, and Claims Management

    CRM systems like Salesforce Insurance Cloud and HubSpot centralize customer interactions, policy details, and communication history, enabling agents to track client journeys and personalize outreach. Underwriting software such as Duck Creek and Guidewire automates risk evaluation, policy generation, and compliance checks, reducing manual errors and accelerating approvals. Claims management platforms (e.g., Eliica, Apollo) digitize claim submissions, fraud detection, and payout processing, improving transparency and reducing resolution times.

    APIs and integrations bridge these tools with insurtech solutions, such as:

  • Real-time risk assessment tools (e.g., Trov’s API for property risk scoring).
  • Dynamic pricing engines (e.g., Lemonade’s AI-driven pricing).
  • Blockchain-based verification (e.g., SettleMint for fraud prevention).
  • These integrations allow agents to embed innovative features into their workflows without disrupting existing processes.

    Comparison of Leading Agent Productivity Tools

    The following table evaluates key tools based on mobile accessibility, automation capabilities, and cost-effectiveness, with data sourced from vendor documentation and industry benchmarks (2023–2024).
    Tool Primary Use Case Mobile Accessibility Automation Features Integration Capabilities Cost (Annual, Per User) Key Differentiator
    Salesforce Insurance Cloud CRM & Policy Management Native mobile app (iOS/Android) AI-driven lead scoring, automated policy renewals Seamless with Duck Creek, Guidewire, and 3,000+ APIs $150–$300 (varies by edition) Unified 360° customer view with Einstein AI
    HubSpot CRM Lead Generation & Client Tracking Mobile-optimized dashboard Automated email sequences, chatbots Zapier, Salesforce, Mailchimp $20–$3,200 (scalable tiers) User-friendly for SMB agents
    Duck Creek Underwriting & Policy Admin Mobile-responsive web interface Automated underwriting rules, e-signatures APIs for insurtech partners (e.g., Trumbull) $50,000–$200,000 (enterprise pricing) Specialized for P/C insurers
    Guidewire Claims & Billing Mobile claims portal Automated fraud detection, dynamic workflows Integrates with Salesforce, ServiceNow $100,000+ (custom pricing) Real-time analytics for claims teams
    Eliica Claims Processing Mobile app for adjusters AI-assisted claim triage, document auto-extraction APIs for insurers (e.g., Allstate, State Farm) $50–$200 per claim (pay-per-use) Reduces claim resolution time by 40%
    Note: Costs reflect enterprise-level pricing; SMB tools (e.g., InsureFusion) may offer lower entry points.

    Implementation of AI-Driven Tools: Chatbots, Predictive Analytics, and Training Requirements

    AI tools enhance agent productivity by automating routine tasks and providing data-driven insights. Key implementations include:
  • Chatbots for FAQs: Platforms like IBM Watson Assistant or ManyChat handle policy inquiries, eligibility checks, and appointment scheduling, reducing agent workload by 30–50% (McKinsey, 2023).
  • Predictive Analytics for Cross-Selling: Tools such as SAS Customer Intelligence analyze customer behavior to recommend complementary policies (e.g., bundling auto with home insurance).
  • Voice Assistants: Google Assistant or Amazon Alexa integrations enable agents to check policy statuses via voice commands.
  • Implementation Process:
    1. Assessment: Identify pain points (e.g., high call volumes, manual data entry) where AI can add value.
    2. Tool Selection: Choose vendor-agnostic platforms (e.g., Microsoft Azure AI) or insurtech-specific solutions (e.g., Shift Technology’s AI underwriting).
    3. Integration: Use APIs to connect AI tools with existing CRM/underwriting systems (e.g., Salesforce + Einstein AI).
    4. Training: Conduct role-based training (e.g., agents learn to interpret AI-generated risk scores) and provide shadowing sessions with tech teams.
    5. Pilot Testing: Deploy AI in a controlled environment (e.g., one branch) and measure KPIs like response time reduction or policy issuance speed.
    6. Scaling: Gradually expand based on pilot results, with change management strategies such as:

  • Gamification: Reward agents for adopting new tools (e.g., leaderboards for fastest AI-assisted policy issuance).
  • Peer Mentorship: Assign "AI champions" to guide colleagues.
  • Feedback Loops: Use surveys to refine tool usability.
  • Training Requirements:

  • Technical Skills: Basic proficiency in navigating AI dashboards (e.g., adjusting chatbot responses).
  • Soft Skills: Adaptability to trust AI suggestions while retaining human oversight (critical for claims disputes).
  • Ethical Training: Compliance with GDPR or CCPA when using AI for data analysis.
  • Step-by-Step Guide to Leveraging Digital Marketing for Lead Generation

    Digital marketing tools enable agents to attract and convert leads efficiently. Below is a structured approach using email campaigns, SEO, and LinkedIn, optimized for insurance-specific audiences.

    1. Email Campaigns for Nurturing Leads
    Email remains a high-conversion channel for insurance leads, with an average ROI of 36:1 (Litmus, 2023). Key steps:

  • Segmentation: Use CRM data to categorize leads by:
  • Policy Type (e.g., auto vs. life).
  • Engagement Level (e.g., opened past emails vs. new prospects).
  • Lifecycle Stage (e.g., quote requesters vs. policyholders).
  • Automation Workflow:
    1. Welcome Series: Send a 3-email sequence within 7 days of lead capture, including:
    2. Email 1: Policy comparison guide (e.g., "Term vs. Whole Life Insurance").
    3. Email 2: Case study (e.g., "How Agent X Saved Client Y $500/Year").
    4. Email 3: Limited-time offer (e.g., "Free Risk Assessment").
    5. Drip Campaigns: Schedule monthly emails with:
    6. Educational Content: "5 Signs Your Auto Policy Needs an Update."
    7. Social Proof: Client testimonials or agent success stories.
    8. CTAs: "Book a 15-Minute Consultation."
    9. Trigger-Based Emails:

      The future of insurance agents hinges on their capacity to merge traditional expertise with cutting-edge tools, ensuring compliance while delivering unparalleled value. By leveraging data analytics for tailored recommendations, embracing digital engagement strategies, and upholding ethical standards, agents position themselves as indispensable advisors in an era of rapid change. The evolution of their role underscores a critical truth: success lies not in resistance to transformation, but in strategic integration of technology, regulation, and client-centric practices to sustain relevance and growth.

      FAQ

      What is an insurance agency and how does it work?

      An insurance agency is a business licensed to sell, service, and administer insurance policies on behalf of one or more insurance companies. Agents or brokers working at the agency help clients find coverage, file claims, and manage policies. Agencies may represent a single insurer (captive) or multiple companies (independent). They earn commissions or fees for their services.

      What does an insurance agent do and what is their role?

      An insurance agent is a licensed professional who sells insurance policies, advises clients on coverage options, and assists with claims processing. Their role includes assessing customer needs, explaining policy terms, and ensuring compliance with regulations. Agents may specialize in areas like auto, home, life, or health insurance and work for agencies, brokerages, or directly for insurers.

      How does an insurance agency differ from an insurance company?

      An insurance agency is a middleman that sells policies from one or more insurance companies and provides customer service, while the insurance company is the underwriter that assumes financial risk and pays claims. Agencies don’t hold the company’s funds but act as distributors, whereas companies issue policies, set premiums, and manage reserves. Agencies rely on commissions from the insurer for revenue.

      What are AI agents in insurance, and how are they being used?

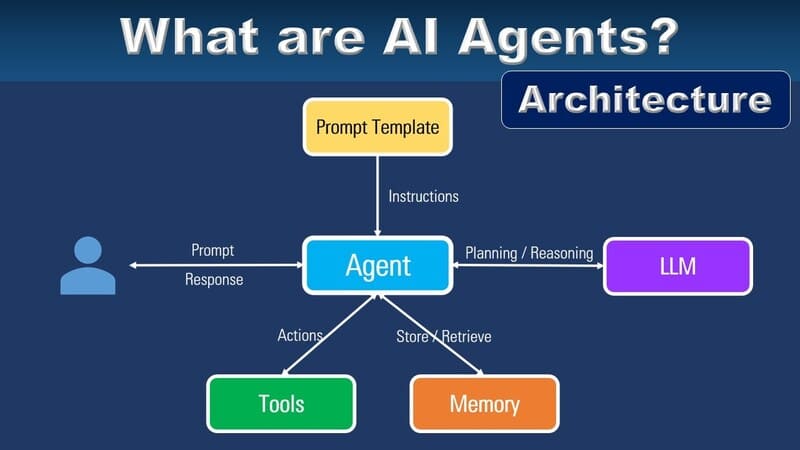
      AI agents in insurance are automated systems using artificial intelligence to handle tasks like underwriting, claims processing, customer service (via chatbots), and risk assessment. They analyze data faster than humans, detect fraud patterns, and personalize policy recommendations. Companies use AI to reduce costs, improve efficiency, and enhance the customer experience without replacing human agents entirely.

      What are independent insurance agents, and how do they operate?

      Independent insurance agents are licensed professionals who work for themselves or with independent agencies and can sell policies from multiple insurance companies. They offer clients a broader range of options compared to captive agents and earn commissions from the insurers they represent. Their independence allows them to tailor coverage to client needs rather than pushing a single company’s products.

      Where can I find insurance agents near me?

      To find insurance agents near you, start by searching online directories like the National Association of Insurance Commissioners (NAIC) or the Independent Insurance Agents & Brokers of America (IIABA). Local business listings (Google Maps, Yelp), insurance company websites, or referrals from friends/family can also help. Verify the agent’s license through your state’s insurance department to ensure legitimacy.

agents in insurance - Kesimpulan

agents in insurance - Kesimpulan

Leave a Comment

Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of viralcontentbee.com.